Author: fittslawfirm

man reviewing documents and check from envelope outside brick residential home

18% Penalty Interest: How Texas Law Handles Late Home Insurance Payouts

When Your Insurer Drags Its Feet: Understanding Texas Penalty Interest

Key Takeaways: When a Texas home insurance payout arrives late, state law can force insurers to pay extra, with penalties reaching 18 percent annual interest on top of what is owed. Under Tex. Ins. Code § 542.060(a), an insurer violating Chapter 542’s prompt-payment rules must pay this interest plus reasonable attorney’s fees stacked on underlying claim benefits. Interest accrues from the date of the statutory violation until judgment is rendered in the trial court, so delay grows increasingly costly. Insurers must meet firm deadlines, including 15-day acknowledgment requirements, and cannot deny claims without reasonable explanation or investigation. For weather-related claims under Chapter 542A, a simple-interest calculation may replace the flat 18 percent rate. Houston windstorm claims generally must be filed within one year of the loss. Because outcomes depend on policy language and facts, reviewing a delayed or denied claim with counsel can help protect your recovery.

If your Texas home insurance payout arrives late, state law can force your insurer to pay extra. Texas imposes a penalty on carriers that violate prompt-payment rules, reaching 18 percent annual interest on top of what you are owed. For Houston homeowners recovering from hail, wind, or hurricane losses, this rule turns an insurer’s delay into a meaningful financial consequence.

If your storm claim has stalled, the team at Fitts Law Firm, PLLC is ready to help you understand your options. Call our office at 713-871-1670 or reach us through our confidential case review form to discuss what a delayed payout may mean for you.
Texas Insurance Code prompt payment document and Texas Property Casualty check on desk with circled calendar dates

How the 18% Penalty Interest Rule Actually Works

The 18 percent figure comes directly from the Texas Insurance Code, not from a courtroom formula.
Tex. Ins. Code § 542.060(a) requires insurers not in compliance with Chapter 542’s prompt-payment subchapter to pay 18 percent annual interest as damages, plus reasonable and necessary attorney’s fees.

This penalty stacks on top of the benefits you were already entitled to receive.
The penalty is in addition to underlying claim benefits and attorney’s fees, and does not preclude recovery of ordinary prejudgment interest, giving policyholders layered remedies for delay.

The interest is not a flat, one-time charge that stops accruing.
The 18 percent interest begins running from the date of the statutory violation and continues until judgment is rendered in the trial court, so the longer the insurer stalls, the more it owes. Post-judgment interest under the Texas Finance Code may apply thereafter. The full statutory framework appears in the Texas Insurance Code on prompt payment.

💡 Pro Tip: Keep a dated log of every phone call, email, and letter from your insurer. Because penalty interest can be tied to specific deadlines, a clear timeline often becomes the backbone of a delayed-payout dispute.

Deadlines Insurers Must Meet Under the Prompt Payment Act

Texas law sets firm clocks that insurers must follow once you file a first-party claim.
Subchapter B codifies the Texas Prompt Payment of Claims Act, setting deadlines for acknowledging, investigating, and paying first-party claims whose violation triggers the 18% penalty.

One of the earliest triggers is the acknowledgment requirement.
The statute establishes strict claim-handling deadlines, including a 15-day acknowledgment requirement under Tex. Ins. Code § 542.055, that trigger the penalty when missed.

A different provision addresses what happens when payment lands very late.
Under Tex. Ins. Code § 542.058, an insurer that delays payment more than 60 days after receiving all reasonably requested proof of loss becomes liable for the claim amount plus the 18 percent penalty interest and attorney’s fees under § 542.060.

Common Delay and Denial Tactics the Law Targets

The Insurance Code does more than police missed deadlines; it also addresses how insurers communicate and investigate.
Insurers may not fail to promptly give a policyholder a reasonable explanation for a denial under Tex. Ins. Code § 541.060(a)(3), and may not refuse to pay a claim without first conducting a reasonable investigation under § 541.060(a)(7).

Texas also treats certain settlement conduct as an unfair practice.
Tex. Ins. Code § 541.060(a)(2) makes it unlawful for an insurer to fail to attempt in good faith to reach a prompt, fair, and equitable settlement once the insurer’s liability has become reasonably clear. Homeowners can review these unfair-settlement provisions in the Texas statute on settlement practices.

Common warning signs of an improperly handled claim include:

  • Repeated requests for documents you already provided
  • A denial letter that never explains the policy basis for the decision
  • An adjuster who goes silent for weeks after a site inspection
  • A settlement offer far below your independent repair estimates

💡 Pro Tip: Ask your insurer to put every coverage position in writing. A written denial that lacks a clear policy explanation may itself point to a statutory violation.

Special Rules for a Houston Storm Damage Claim

Not every property claim uses the same flat 18 percent calculation.
For weather-related property claims governed by Chapter 542A, Section 542.060(c) substitutes a simple-interest calculation, set at 5 percent plus the rate determined under Section 304.003 of the Finance Code (which is the prime rate, floored at 5% and capped at 15%), rather than the flat 18% rate. The statute does not contain an explicit 20 percent cap, though the mathematical maximum of the combined rate is 20 percent. This is an important distinction for Houston hail, wind, and storm claims.

Because Houston sits in hurricane and hail country, this carve-out matters for many local homeowners. Texas Insurance Code Chapter 542, Processing and Settlement of Claims, is the authoritative foundation for how insurers must handle late home insurance payouts in Texas. You can read the full text of Subchapter B through this Justia summary of prompt payment law.

Whether the flat rate or the simple-interest method applies depends on the specific facts of your loss. Because the distinction turns on how a claim is characterized under Chapter 542A, outcomes can vary. This is one reason many homeowners choose to review their policy and denial with counsel before assuming which penalty interest calculation applies.

Filing Deadlines You Cannot Afford to Miss

Texas windstorm coverage carries a hard filing deadline that surprises many homeowners.
Under Tex. Ins. Code § 2210.205(a), a windstorm and hail insurance policy must require an insured to file a claim not later than the first anniversary of the date the property damage occurred, meaning Houston-area homeowners generally have one year from the storm to file.

That one-year window is not completely rigid, but extensions are limited and discretionary.
On a showing of good cause by the insured, the commissioner may extend the one-year period by up to an additional 180 days under Tex. Ins. Code § 2210.205(b). The full windstorm framework appears in the Texas windstorm association statute.

Separate from these filing rules, Texas recognizes broader deadline concepts that can end a claim entirely.
A statute of repose imposes an absolute cutoff on lawsuits regardless of when harm is discovered. Courts generally interpret exceptions such as tolling and discovery rules narrowly, applying only in limited circumstances.

💡 Pro Tip: Treat the storm date, not the date you noticed damage, as your starting point for deadline planning. Hidden hail or wind damage can push homeowners dangerously close to the one-year windstorm filing cutoff.

Why a Houston Storm Damage Attorney Can Strengthen Your Position

Understanding penalty interest is one thing; proving a violation is another. A Houston storm damage attorney focuses on documenting the insurer’s timeline, establishing coverage and causation, and connecting missed deadlines to statutory penalties. Because these disputes are fact-intensive, the strength of your evidence often shapes the outcome.

Independent documentation frequently makes the difference in a delayed claim. Homeowners benefit from photographs, dated repair estimates, and independent inspections that rebut an insurer-retained engineer’s report. This policyholder-focused approach is central to how firms handle denied insurance claims in Houston, Texas and other first-party property disputes.

No lawyer can promise a specific result, because coverage outcomes depend on your policy language and the facts of your loss. Still, knowing your rights under the Texas prompt payment penalty framework helps you respond with confidence. You can learn how Texas 18% interest works before deciding on your next step.

💡 Pro Tip: Do not sign a release or accept a "final" payment while you are still repairing damage. Accepting a settlement may complicate your ability to pursue additional benefits or penalty interest later.

Frequently Asked Questions

1. Does the 18 percent penalty apply automatically to every late payout?

Not automatically. The penalty generally applies when an insurer violates the prompt-payment deadlines in Chapter 542, Subchapter B. Whether a violation occurred depends on the facts and specific timeline of acknowledgment, investigation, and payment.

2. Is the penalty always a flat 18 percent for storm claims?

Not necessarily. For weather-related claims governed by Chapter 542A, Section 542.060(c) can substitute a simple-interest calculation instead of the flat 18 percent rate. The correct method depends on how your claim is characterized.

3. How long do I have to file a Houston windstorm claim?

Generally one year from the date the damage occurred. Under Tex. Ins. Code § 2210.205(a), windstorm and hail policies must require filing by the first anniversary of the loss, though the commissioner may extend that period by up to 180 days on a showing of good cause.

4. Can I recover more than just the penalty interest?

Often, yes. Under Tex. Ins. Code § 542.060(a), the penalty interest is in addition to your claim benefits and reasonable attorney’s fees, and does not prevent an award of ordinary prejudgment interest in appropriate cases.

5. What if my insurer denied my claim without explaining why?

That may signal a statutory problem. Tex. Ins. Code § 541.060(a)(3) prohibits failing to promptly provide a reasonable explanation for a denial, and § 541.060(a)(7) bars refusing to pay without a reasonable investigation.

Protecting Your Recovery After a Delayed Payout

Texas gives policyholders real leverage when insurers ignore prompt-payment deadlines. Between the 18 percent penalty interest, the unfair-settlement protections, and the layered remedies that stack on top of your original benefits, the law is designed to discourage unreasonable delay. For Houston homeowners facing a late insurance payout after a storm, understanding these rules is the first step toward holding a carrier accountable.

If your storm claim has been delayed, underpaid, or denied, the team at Fitts Law Firm, PLLC is ready to review your options. Call us today at 713-871-1670 or request your consultation online to take the next step toward the recovery you may be owed.
woman reviewing tabbed legal documents beside large stacks of paperwork in kitchen

Is Repeated Document Requests a Stalling Tactic by Houston Insurers?

How Houston Homeowners Can Spot a Document Request Used as a Delay Tactic

Key Takeaways: Repeated document requests by Houston insurers can be legitimate, but a pattern of serial, repetitive demands unrelated to new findings may signal unlawful stalling. Under the Texas Prompt Payment of Claims Act, insurers must request all required items within 15 days and decide a claim within 15 business days after receiving everything. Excessive paperwork demands used to avoid reasonable investigation or timely coverage decisions can amount to bad faith under Chapter 541. Red flags include re-requests for documents already provided, demands unrelated to your loss, and repeated extensions without new findings. Texas offers remedies including statutory penalty interest (generally 18%, though storm claims under Chapter 542A use a different rate), actual damages, attorney’s fees, and up to treble damages for knowing violations. Careful documentation and acting before deadlines are the best ways to protect a stalled claim.

Repeated document requests can legitimately be part of an insurer’s investigation, but a pattern of serial, repetitive demands may signal a deliberate stalling strategy. When a Houston homeowner files a storm or property claim, Texas law sets firm timelines. If your carrier keeps asking for the same paperwork, sends new requests each time you respond, or never seems satisfied, the behavior may cross from diligent investigation into unlawful delay. Understanding the difference is the first step in knowing what to do if insurance company is stalling in Texas.

If you believe your carrier is using excessive documentation requests to wear you down, the team at Fitts Law Firm, PLLC is ready to help. Call our office at 713-871-1670 or reach out through our online case review form to discuss your situation with a Houston attorney focused on policyholder rights.

stacked legal documents labeled Sept 20, Oct 5, Nov 1 beside desk calendar with circled deadlines

The Texas Prompt Payment Rules That Limit Insurer Delay

Texas law requires insurers to act quickly and front-load their document requests rather than spread them out over months. Under the Prompt Payment of Claims Act, Section 542.055 requires insurers to acknowledge receipt, commence investigation, and request all required items within 15 days of receiving notice. Carriers must identify the documents they reasonably need at the outset, not piecemeal over time.

The statute allows follow-up requests, but only within a narrow exception. Section 542.055(b) permits additional requests if, during the investigation of the claim, the additional requests are necessary. By contrast, a steady drip of repetitive demands unrelated to any actual discovery suggests the carrier is manufacturing reasons to keep the clock from stopping. You can review these provisions in the Texas Insurance Code’s prompt payment of claims chapter.

Once an insurer has everything it needs, the decision deadline begins to run. Section 542.056 requires the insurer to notify the claimant of acceptance or rejection not later than the 15th business day after receiving all required items, and it may request a single 45-day extension. Case law holds that if sufficient information has been provided for a claim determination, the deadline may have begun despite outstanding requests. An insurer generally cannot reset the clock simply by sending another request.

💡 Pro Tip: Keep a dated log of every document request and response. A clear timeline showing when you provided "all items, statements, and forms" can be powerful evidence that the statutory deadline has started.

When Repeated Document Requests Become Bad Faith Insurance Delay

Texas treats certain stalling behaviors not just as missed deadlines but as unfair settlement practices. Chapter 541 of the Texas Insurance Code protects policyholders from insurer misconduct. Among prohibited conduct, the statute lists failing within a reasonable time to affirm or deny coverage, failing to provide a reasonable explanation for denial, and refusing to pay without conducting a reasonable investigation.

An insurer cannot substitute endless paperwork demands for genuine investigation. Chapter 541 prohibits refusing to pay a claim without conducting a reasonable investigation, so a carrier that hides behind excessive documentation instead of evaluating your loss may be exposed to liability. Repeated requests used to circumvent the duty to affirm or deny coverage within a reasonable time can fit this pattern. You can read the provisions in the Texas Insurance Code’s unfair settlement practices chapter.

The statute is meant to be read in favor of prompt payment. Section 542.054 states the subchapter shall be liberally construed to promote prompt payment of insurance claims. Courts may consider this directive when an insurer argues ongoing document requests excuse delayed decisions.

Common red flags that a request may be a stalling tactic include:

  • New requests for documents you already submitted, with no explanation of deficiencies
  • Demands for records unrelated to the cause or scope of your loss
  • Repeated extensions sought without any new investigative finding
  • Refusal to issue a coverage decision long after you supplied everything reasonably required

If you recognize these patterns, it may be worth learning how an insurer can misuse delay tactics to avoid payment before your statutory deadlines slip away.

💡 Pro Tip: Respond to every request in writing, even if only to note that the requested item was already provided on a specific date. Written communication creates a paper trail documenting the insurer’s conduct.

What to Do if Insurance Company Is Stalling in Texas

Knowing what to do if insurance company is stalling in Texas starts with documentation and ends with understanding your legal remedies. Texas gives policyholders real financial tools to push back against insurance delay tactics in Houston. The penalties are designed to make stalling expensive for the carrier and compensate homeowners who endured delay.

The financial consequences of delay can be significant. Under Section 542.058, if an insurer delays payment beyond 60 days after receiving all requested items, it shall pay damages as provided by Section 542.060. For most first-party claims that penalty interest is 18% per annum, but for weather-related property claims governed by Chapter 542A, the rate is tied to the judgment rate under Finance Code Section 304.003 plus five percent. Additionally, Chapter 541 provides a private action, and Section 541.152 allows a prevailing plaintiff to recover actual damages, court costs, and reasonable attorney’s fees, and on a finding that the defendant knowingly committed the act, up to three times the amount of actual damages.

The table below summarizes remedies that may apply to a denied home insurance claim in Texas involving delay:

Statutory Basis Conduct Addressed Potential Remedy
Section 542.058 / 542.060 Payment delayed beyond 60 days after all items received 18% annual penalty interest (a different statutory rate applies to storm claims under Chapter 542A) plus attorney’s fees
Section 541.060 Unfair settlement practices, including unreasonable delay Actual damages and attorney’s fees
Section 541.152 Knowing violation of Chapter 541 Up to three times actual damages

These remedies depend on proof. A policyholder must show the insurer’s conduct violated the statute and, for enhanced damages, that the violation was "knowing." The treble damages provision serves as a powerful deterrent against insurers who deliberately use repeated document requests to wear down Houston homeowners.

💡 Pro Tip: Texas deadlines for filing suit are limited and courts interpret tolling exceptions narrowly. Do not assume ongoing negotiations or pending document requests will extend your time to act.

Practical Steps to Protect a Stalled Homeowners Claim

Protecting your claim is largely about preserving evidence and acting before deadlines pass. When you suspect homeowners claim stalling in Texas, organizing your file early can make a meaningful difference if litigation becomes necessary. Independent documentation often becomes the foundation for rebutting an insurer’s reports.

Consider gathering and preserving the following while your claim is open:

  • Copies of your full policy, including declarations and endorsements
  • Dated photos and videos of the damage and any temporary repairs
  • All correspondence, emails, and the dated log of document requests
  • Independent inspection reports or estimates that support the cause and scope of loss

Carefully maintained records help establish coverage, causation, and measurable damages. If you want a deeper understanding of your options, our overview of denied home insurance claim representation explains how these disputes are typically handled.

💡 Pro Tip: When an insurer’s engineer or adjuster blames pre-existing conditions or wear and tear, an independent inspection can directly counter that conclusion and strengthen your position.

Frequently Asked Questions

1. How long does an insurer have to decide my claim in Texas?

Generally, the carrier must act on a tight statutory schedule. Under Section 542.056, an insurer must notify the claimant of acceptance or rejection not later than the 15th business day after receiving all required items and may request a single 45-day extension.

2. Can an insurer keep requesting documents to avoid the deadline?

Not without limits. Additional requests are permitted if, during the investigation, the additional requests are necessary. A pattern of repetitive demands unrelated to new information may indicate bad faith insurance delay.

3. What damages can I recover if my insurer stalls?

Texas provides several remedies depending on the facts. These may include penalty interest under Section 542.060, 18% per annum for most claims or a rate tied to the judgment rate plus five percent for weather-related property claims under Chapter 542A, actual damages and attorney’s fees under Chapter 541, and up to treble damages for knowing violations.

4. Is repeated documentation always a sign of bad faith?

No, and that distinction matters. Some requests are legitimate parts of reasonable investigation. The concern arises when excessive documentation requests appear designed to delay a decision rather than evaluate the loss.

5. Should I keep responding to the requests?

In many cases, yes, while documenting everything. Continuing to respond in writing, while noting items already provided, preserves your cooperation and builds a record. Consulting an insurance claim attorney in Houston can help you decide your next step.

Moving Forward Against Insurance Delay Tactics

Repeated document requests are not always improper, but when they become a tool to avoid a timely coverage decision, Texas law offers Houston homeowners real protection. Between the prompt payment deadlines, the unfair settlement practices provisions, and the availability of penalty interest and enhanced damages, policyholders have meaningful leverage against carriers who stall. The strength of your position depends on careful documentation and a clear understanding of the governing statutes.

If you are facing a home insurance dispute in Texas and suspect your carrier is delaying payment, Fitts Law Firm, PLLC is prepared to review your claim and explain your options. Call us today at 713-871-1670 or schedule your consultation online to take the next step toward resolving your stalled claim.

Temporarily Closed sign taped to glass door of brick storefront building

What Is Business Interruption Insurance and Why Are Claims Denied?

Understanding the Lifeline of Business Interruption Coverage

Key Takeaways: Business interruption insurance replaces income lost when covered events like fires or storms force operations to pause, covering ongoing expenses such as rent, payroll, and lost profits. Claims are frequently denied when insurers dispute the cause of loss, argue exclusions apply, claim income loss is unproven, or contend the restoration period has expired. Texas law offers strong protections, including unfair settlement practices statutes, prompt-payment deadlines, and remedies like treble damages and 18% interest. Houston policyholders facing wrongful denials or underpayments have statutory avenues to challenge insurers. Because outcomes depend on specific facts and strict deadlines apply, timely action is essential. An experienced denied commercial insurance claim lawyer can review your denial and help build a stronger record.

Business interruption insurance replaces income lost when covered events force operations to pause. When fire, storm, or disaster shuts down your storefront, this coverage helps pay ongoing expenses like rent, payroll, and lost profits during recovery. Claims are frequently denied when insurers dispute the cause of loss, argue policy exclusions, or claim income loss is unproven. Understanding why your claim was rejected is the first step toward protecting your recovery.

If your business income claim was wrongfully denied, you do not have to fight alone. The team at Fitts Law Firm, PLLC helps Houston policyholders challenge unfair denials and pursue promised compensation. Call us at 713-871-1670 or reach out through our secure contact page to discuss your options.

man handing stack of legal folders to staff member at office counter

What Business Interruption Insurance Is Built to Cover

Business interruption coverage steps in when physical damage to your property halts or reduces normal operations. Most commercial policies tie this coverage to a covered peril, meaning the shutdown cause must already be insured under your property coverage. This typically includes fire, wind, hail, or vandalism, though flood and certain risks often require separate endorsements.

The Core Losses This Coverage Replaces

This insurance typically reimburses income your business would have earned had the disruption never occurred. It may also cover fixed operating costs that continue regardless of whether your doors are open, such as lease payments, loan obligations, and certain wages. Some policies extend to "extra expense" coverage, which helps pay added costs of operating from a temporary location. Because terms vary widely, precise scope depends on your specific contract language.

💡 Pro Tip: Keep two years of profit-and-loss statements, tax returns, and sales records in a secure, off-site location. These documents become essential evidence when calculating income loss.

Common Reasons Houston Business Interruption Claims Get Denied

Insurers deny business interruption claims for various reasons, some legitimate and some that may cross into unfair practices. A carrier might argue the cause of loss is excluded, the interruption period has ended, or your financial records fail to substantiate claimed losses. Disputes over dollar amounts are especially common, even when coverage itself is not questioned.

Frequent grounds for business interruption insurance denial include:

  • Disputes over whether the triggering event qualifies as a covered peril
  • Allegations that financial documentation does not prove loss amount
  • Claims that the "period of restoration" has expired
  • Assertions that flood or excluded causes produced the damage
  • Arguments that the policyholder failed to mitigate ongoing losses

Even when insurers accept claims in principle, fights over valuation frequently arise. Where claims involve the Texas Windstorm Insurance Association, Texas Insurance Code § 2210.574 provides dispute-resolution and appraisal frameworks for resolving coverage-amount disagreements. Most commercial policies separately contain appraisal provisions, giving Houston business owners statutory and contractual avenues to challenge underpayments. This protection is significant because underpayment can be just as damaging as flat rejection.

Texas Laws That Protect Policyholders From Unfair Denials

Texas law explicitly prohibits insurers from engaging in unfair settlement practices. Under Texas Insurance Code § 541.060(a), insurers who misrepresent policy provisions, fail to conduct reasonable investigation, refuse to pay clearly valid claims, or fail to promptly explain denials can be held liable. Houston business owners whose commercial interruption claims are wrongfully denied may have legal recourse under this statute. Review the full text of the Texas unfair settlement practices statute through the state’s official code library.

When an Insurer’s Liability Becomes Reasonably Clear

Texas law bars insurers from delaying settlements when liability is reasonably clear. Under Texas Insurance Code § 541.060(a)(2), carriers may not fail to attempt in good faith to effectuate prompt, fair, and equitable settlement once liability becomes reasonably clear. If an insurer stalls or refuses to settle an undisputed business interruption claim, that conduct may constitute an actionable unfair practice.

Penalties That Deter Bad-Faith Conduct

The Texas Insurance Code provides meaningful consequences for insurers that knowingly break the rules. If an insurer knowingly violates Chapter 541, policyholders may recover up to treble damages on actual damages, creating strong deterrent against bad faith denials. Chapter 541 also includes Subchapter D, allowing policyholders to sue insurers directly for violations. These remedies generally apply when insurers misrepresent provisions, fail to explain denials, or refuse to pay without reasonable investigation.

💡 Pro Tip: Request every denial reason in writing. Written explanation often reveals whether the insurer followed the law.

Deadlines Insurers Must Follow Under Texas Prompt Payment Rules

Texas imposes strict timelines on insurers handling commercial claims, and missed deadlines carry real penalties. Chapter 542 of the Texas Insurance Code requires carriers to acknowledge claims, investigate, and respond within defined windows. A claimant must be notified in writing of acceptance or rejection within 15 business days after receiving all items necessary to confirm conclusive proof of loss.

Insurer Obligation Governing Provision General Deadline
Acknowledge claim and begin investigation § 542.055 15 days from notice
Accept or reject the claim § 542.056 15 business days after full documentation
Pay an approved claim § 542.057 5 business days after approval
Outer limit for determination and payment Chapter 542 60 days

Delays beyond these windows can entitle you to added compensation. If an insurer is liable for delaying claim payout in Texas, the claimant may be entitled to interest on unpaid amounts, historically 18%, though for many claims the rate is now 5% above judgment interest rate, along with reasonable attorney’s fees in certain cases. The Texas Department of Insurance offers general guidance on the claims process. Keeping a dated log of every communication helps establish when deadlines were triggered.

💡 Pro Tip: Save voicemails, emails, and letters with timestamps. A clear timeline is often key to proving prompt-payment violations.

How a Denied Commercial Insurance Claim Lawyer Can Help

A denied commercial insurance claim lawyer focuses on holding insurers accountable to policy and governing statutes. A knowledgeable attorney can review your denial letter, gather independent documentation, and determine whether the carrier violated Texas law. Involving counsel early helps preserve evidence and prevents insurers from running out the clock.

Building a Stronger Record Against the Insurer

An attorney can help document causation, coverage, and measurable damages, the three pillars of any insurance recovery. This often involves independent estimates, financial analysis, and careful comparison of policy language against the insurer’s stated reasons. A skilled insurance denial attorney in Houston may also identify whether denial reflects a pattern of bad-faith conduct. Learn what a bad-faith denial involves and how a Houston attorney can help.

Timing matters, particularly when bad-faith damages are involved. A claim for recovery of punitive, exemplary, extracontractual, or bad-faith damages awarded in court judgment against an insured or insurer is not a covered claim under the Texas guaranty fund, per Texas Insurance Code § 462.210. Businesses generally must pursue bad-faith claims directly against the insurer while it remains solvent, making prompt action after wrongful denial important.

💡 Pro Tip: Before accepting any settlement that feels low, have figures reviewed independently. Once you sign a release, you may lose rights to pursue additional amounts.

Frequently Asked Questions

  1. Can my insurer cancel my policy after I file a claim?

Generally, no, not without specific legal grounds. Under Texas Insurance Code § 551.052(a)-(c), an insurer may not cancel a renewal commercial property policy, or one past 60 days into its initial term, except for limited reasons like fraud, nonpayment, increased hazard, or loss of reinsurance.

  1. What if my insurer accepted my claim but paid too little?

Underpayment can be challenged just like a denial. For Texas Windstorm Insurance Association claims, Texas Insurance Code § 2210.574 provides a framework for resolving amount disputes, and appraisal provisions in most commercial policies give Houston policyholders paths to contest settlements they believe fall short.

  1. How long does my insurer have to decide on my claim?

Texas law sets clear windows. Insurers generally must accept or reject claims within 15 business days after receiving all required proof of loss, and pay approved claims within 5 business days under § 542.057. The outer deadline is generally 60 days.

  1. What can I recover if my insurer acted in bad faith?

Remedies may include more than the original claim amount. Where an insurer knowingly violates Chapter 541, policyholders may recover up to treble damages, and delayed payments can carry additional statutory interest plus attorney’s fees, subject to proof and case facts.

  1. Do I need a lawyer to fight a denied business interruption claim?

You are not required to hire counsel, but it often helps. Texas insurance disputes involve complex statutes, strict deadlines, and detailed financial proof. Working with experienced counsel can help preserve evidence and present the strongest possible claim.

Protecting Your Business After a Wrongful Denial

A denied business interruption claim does not have to be the final word. Texas law gives policyholders substantial protections, from prompt-payment deadlines to remedies for bad-faith conduct, but those protections require timely and well-documented action. Whether your claim was rejected, underpaid, or delayed, understanding the statutes governing your insurer puts you in a stronger position. Learn more about the firm’s approach to denied insurance claims in Texas.

When an insurer treats your valid claim unfairly, decisive action protects your livelihood. The team at Fitts Law Firm, PLLC is ready to review your denial, explain your rights, and help you pursue the recovery your policy promises. Call 713-871-1670 today or visit our website to get started.

man standing beside large ground fissure cracking yard in front of brick house

What Is the Earth Movement Exclusion in Houston Flood Claims?

Understanding Why Insurers Cite "Earth Movement" After Houston Floods

Key Takeaways: The earth movement exclusion lets insurers deny coverage for damage from shifting, sinking, or settling soil, even when flood caused that movement. In Houston’s expansive clay soils, it’s a leading reason valid flood claims get reduced or denied, often affecting foundations, slabs, and anchorage systems. The exclusion appears in nearly every Texas property and NFIP policy, yet Texas law requires insurers to investigate reasonably, avoid misrepresenting coverage, and settle in good faith. NFIP disputes proceed through federal processes, with coverage capped at $250,000 for structure and $100,000 for contents at Actual Cash Value, plus a strict 60-day proof-of-loss deadline. Thorough documentation and independent engineering evidence on causation are essential to protecting your recovery.

The earth movement exclusion is a policy provision that allows insurers to deny coverage for damage caused by shifting, sinking, or settling soil, even when a flood triggered that movement. In Houston, where expansive clay soils and frequent storms create foundation problems, this exclusion becomes one of the most common reasons valid claims get reduced or rejected. When an adjuster labels foundation cracks, slab heaving, or soil settlement as "earth movement," the result can be a denied or underpaid flood insurance claim that leaves homeowners covering repairs out of pocket.

If your claim was reduced or denied based on this language, the policyholder-focused team at Fitts Law Firm, PLLC can help you evaluate your options. Call us at 713-871-1670 or reach out through our secure contact page to discuss your situation.

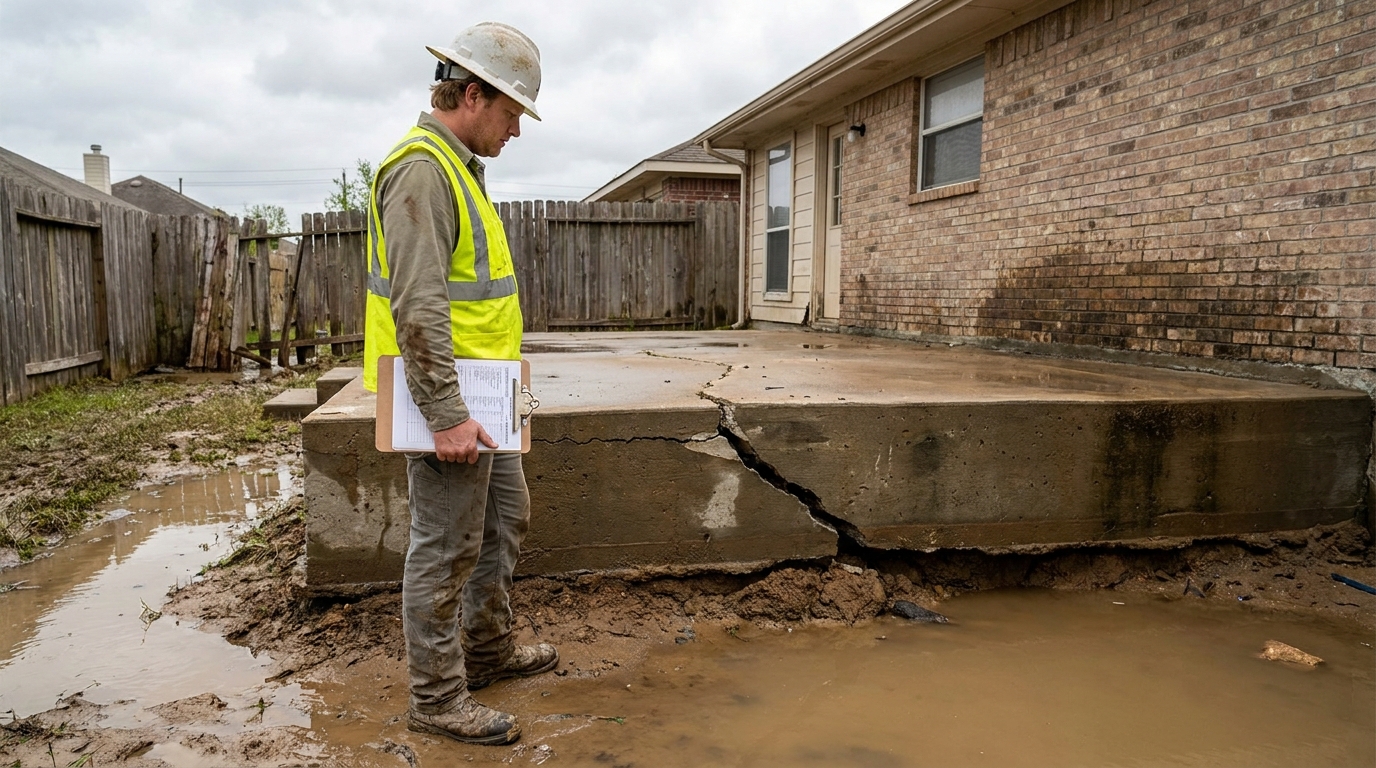
inspector with clipboard examining cracked concrete foundation near flooded residential property

How the Earth Movement Exclusion Actually Operates

The earth movement exclusion appears in nearly every property and flood policy sold in Texas, but its scope is broader than homeowners expect. Under the National Flood Insurance Program, earth movement is excluded even if the earth movement is caused by flood. A flood can saturate the ground, the soil can shift, and the resulting structural damage may fall outside coverage entirely.

This exclusion targets structural elements most vulnerable to flooding. The NFIP identifies foundation walls, anchorage systems, and staircases as insured building property, but it also contains a separate general earth movement exclusion that bars coverage for any loss caused directly by earth movement, even if the earth movement is caused by flood. For Houston homeowners dealing with flood foundation damage, this is where disputes arise.

Commercial property owners face parallel language. Texas special form commercial policies cover most causes of loss except those specifically listed, typically excluding floods, earth movement, war, nuclear disaster, wear and tear, and insects or vermin. The overlap between flood and earth movement exclusions can leave business owners doubly exposed.

💡 Pro Tip: Before accepting an "earth movement" denial, ask your insurer in writing to identify the exact policy language and specific evidence supporting its causation finding. A vague reference to "soil movement" is not documented engineering evidence.

When an Earth Movement Denial May Be an Underpaid Flood Insurance Claim

Not every earth movement denial holds up, and Texas law gives policyholders meaningful tools to challenge improper use of the exclusion. An insurer cannot simply attach the "earth movement" label to avoid paying. Under Texas Insurance Code Section 541.060(a)(7), it is an unfair settlement practice to refuse to pay a claim without conducting a reasonable investigation. An adjuster who classifies damage as earth movement without thorough, site-specific inspection may be acting outside the law.

Misrepresenting policy coverage is also prohibited. Under Texas Insurance Code Section 541.060(a)(1), it is an unfair settlement practice to misrepresent a material fact or policy provision relating to coverage. If your insurer overstated the earth movement exclusion to justify a low payout, that may form the basis of a claim.

Insurers also carry a duty to act in good faith. Under Texas Insurance Code Section 541.060(a)(2)-(3), insurers must attempt in good faith to effectuate a prompt, fair, and equitable settlement once liability has become reasonably clear, and must promptly provide a reasonable explanation for any denial. You can review the full Texas unfair settlement practices statute to understand these protections. These provisions give Houston homeowners a path to dispute an exclusion used as a pretext.

An NFIP policy changes the playing field. Federal flood policies are not governed by the same state consumer-protection rules because federal law preempts state law for NFIP policies. Policyholders disputing an earth movement exclusion denial under an NFIP policy must navigate federal, not state, appeals and dispute processes. Knowing which set of rules applies is essential.

💡 Pro Tip: Independent evidence matters. A licensed engineer’s report distinguishing flood-driven damage from pre-existing soil settlement can be the difference between a denied claim and a fair payout.

Coverage Limits That Compound an Earth Movement Reduction

Even when coverage applies, NFIP limits and valuation rules can shrink what you recover. You can insure a residential building for up to $250,000, and belongings up to $100,000. When an earth movement exclusion carves out part of the structural damage, these ceilings leave even less room for full recovery.

Contents valuation often surprises homeowners. Belongings are covered at Actual Cash Value, their value at the time of damage, not original cost, with no option for full replacement value. Combined with an exclusion that reduces structural payout, this valuation rule can deepen the financial gap.

Deadlines under the NFIP are strict and unforgiving. You must give prompt written notice and submit a signed and sworn proof of loss form within sixty days. Missing this deadline can defeat an otherwise valid claim.

Coverage Element NFIP Limit Key Limitation
Residential building Up to $250,000 Earth movement excluded
Residential contents Up to $100,000 Actual Cash Value only
Proof of loss Required 60-day filing deadline

What Every Houston Homeowner Should Know About Flood Disclosures

Many Houston homeowners don’t realize their standard policy excludes flood damage until it’s too late. Texas law addresses this through a mandatory disclosure. Under Texas Insurance Code Section 2002.103(c), an insurer that issues or renews a property policy without flood coverage must include a conspicuous written statement warning that the policy does not cover flood damage even if hurricane winds and rain caused the flood.

That disclosure rule has a critical limit protecting insurers. A missing warning does not erase an exclusion. Under Texas Insurance Code Section 2002.103(e), an insurer’s failure to comply does not invalidate any exclusion in a policy. You cannot void an earth movement or flood exclusion simply because the insurer failed to warn you.

Standard homeowner’s coverage rarely covers flood losses. Standard homeowner’s insurance policies generally cover damage from sudden and accidental leaks but not flooding. The Texas Department of Insurance offers helpful Texas flood insurance basics that explain these distinctions.

Timing your coverage matters. There is a 30-day waiting period after you buy a flood policy before coverage goes into effect. Planning ahead of storm season is essential.

Key steps to protect your flood rights:

  • Document damage thoroughly with photos, video, and dated records
  • Request the insurer’s written basis for any earth movement denial
  • Obtain an independent engineering assessment of causation
  • Track every deadline, including the NFIP proof-of-loss window

If your claim has been rejected, learn how to appeal a denied flood insurance claim.

💡 Pro Tip: Keep a written log of every call, email, and adjuster visit. Documentation is often decisive when challenging a bad-faith or underpaid flood claim.

How a Houston Flood Damage Attorney Can Help

A policyholder-focused attorney can test whether an earth movement exclusion was applied correctly to your loss. Causation in flood cases is frequently disputed, and the difference between flood damage and soil movement is fact-dependent. An attorney can coordinate independent inspections, demand the insurer’s investigation file, and identify whether the carrier met its statutory duties.

Outcomes depend on specific facts, policy language, and evidence. No two flood claims are identical, and conditional rules under state and federal law may apply differently depending on your policy type. Working with an experienced Houston flood damage attorney helps ensure your rights are evaluated under the correct framework.

Frequently Asked Questions

1. Can my insurer deny my entire claim using the earth movement exclusion?

Not necessarily. While the exclusion can limit structural recovery, an insurer must investigate and may not misrepresent coverage. Improper use may support a dispute under Texas Insurance Code Section 541.060.

2. Does the earth movement exclusion apply to NFIP flood policies?

Yes. The NFIP excludes damage caused by earth movement, even if flood-caused. However, disputes over NFIP policies proceed through federal processes rather than Texas state remedies.

3. What if my insurer never warned me that flood damage was excluded?

A missing disclosure does not undo an exclusion. Under Texas Insurance Code Section 2002.103(e), an insurer’s failure to provide the required flood warning does not invalidate a flood or earth movement exclusion.

4. How long do I have to file my proof of loss under the NFIP?

Generally sixty days. You must submit a signed and sworn proof of loss form within sixty days of the loss. Missing this deadline can jeopardize an otherwise valid claim.

5. Is foundation damage from a flood ever covered?

It depends on the facts. Many foundation losses fall under the earth movement exclusion, but independent evidence showing a covered flood cause may support coverage in limited circumstances. Causation is often the central issue.

Protecting Your Recovery After a Houston Flood

The earth movement exclusion is one of the most powerful tools insurers use to reduce or deny Houston flood claims, but it is not unlimited. Texas law imposes duties of good faith, reasonable investigation, and honest communication, and federal NFIP rules create their own deadlines and dispute paths. When an insurer leans on this exclusion to justify an underpaid flood insurance claim, careful documentation, independent evidence, and clear understanding of governing statutes can make the difference.

If you believe your earth movement denial was unfair, the team at Fitts Law Firm, PLLC is ready to review your claim and explain your options. Call us today at 713-871-1670 or send us a message through our online contact form to take the next step toward protecting your home and your recovery.

man seated at desk reviewing printed documents and file folders in office

Is an Insurer Acting in Bad Faith if It Ignores Evidence?

When Your Insurer Looks the Other Way: Understanding Bad Faith in Texas

Key Takeaways: An insurer acts in bad faith when it ignores submitted evidence, contractor estimates, storm damage reports, or photographs, and denies a valid claim, since insurers may not disregard clear proof once liability becomes reasonably clear. Bad faith is a specific legal concept requiring proof the insurer knew or should have known coverage was clear; mere erroneous denial is insufficient. Chapters 541 and 542 of the Texas Insurance Code require reasonable investigations, prompt settlements, explanations, and 15-day acknowledgment. Carriers cannot hide behind biased expert reports, as courts scrutinize both independence and substance. Successful claims can recover actual damages, attorney’s fees, and up to treble damages when insurers knowingly violated the law.

An insurer can be acting in bad faith when it ignores the evidence you submit and denies your claim anyway. Texas law prohibits insurance companies from disregarding contractor estimates, storm damage reports, or photographs without reasonable basis. When a Houston homeowner provides proof of a covered loss and the carrier ignores it, that conduct may constitute actionable bad faith, opening the door to remedies beyond policy limits.

If your homeowner’s claim was denied after you submitted clear documentation, you have legal options. The team at Fitts Law Firm, PLLC helps Texas policyholders hold insurers accountable. Call us at 713-871-1670 or reach out through our online contact page to discuss your situation.

Insurance policy document stamped Claim Denied on law office conference table

What "Bad Faith" Actually Means Under Texas Law

Bad faith is a specific legal concept, not just frustration with a slow or stingy adjuster. Under Texas law, an insurer breaches its duty of good faith and fair dealing when it fails to settle a claim if the insurer knew or should have known that coverage was reasonably clear. The Dallas Court of Appeals confirmed this standard in State Farm Lloyds v. Hamilton, 265 S.W.3d 725 (Tex. App., Dallas 2008).

Not every wrong decision counts as bad faith. Texas courts recognize in Hamilton, 265 S.W.3d at 734, that mere erroneous denial does not equate to bad faith. There must be something more, such as unreasonable reliance on evidence that was not objectively prepared. This nuance protects insurers who make honest mistakes while giving policyholders recourse when carriers act unreasonably.

💡 Pro Tip: Keep every email, letter, and voicemail from your insurer. A documented timeline of when you submitted evidence and how the carrier responded is often the backbone of a bad faith insurance denial Houston case.

The Statutory Framework That Protects Houston Homeowners

The Texas Insurance Code gives policyholders concrete legal tools when an insurer disregards proof of loss. Chapter 541 lists specific prohibited practices, and the unfair settlement practices provisions of Chapter 541 are where most evidence-related bad faith claims begin.

First, the law requires insurers to investigate before they deny. Under Tex. Ins. Code § 541.060(a)(7), refusing "to pay a claim without conducting a reasonable investigation with respect to the claim" is an unfair settlement practice. When a Houston homeowner submits photos, contractor estimates, or independent reports and the insurer denies anyway, that statute provides direct legal grounds for a claim.

Second, insurers must act when liability becomes clear. Tex. Ins. Code § 541.060(a)(2) prohibits "failing to attempt in good faith to effectuate a prompt, fair, and equitable settlement of a claim with respect to which the insurer’s liability has become reasonably clear." If compelling evidence of a covered loss exists and the carrier refuses to settle, that refusal can constitute bad faith.

The carrier also owes you an explanation and a timely answer. Under Tex. Ins. Code § 541.060(a)(3), an insurer must promptly provide a reasonable explanation for denial, grounded in policy terms and facts. A denial letter with boilerplate language that ignores your evidence may itself be actionable.

Deadlines: How the Prompt Payment Rules Reinforce Your Rights

The Texas Prompt Payment of Claims Act sets firm timelines that work in a policyholder’s favor. Chapter 542 of the Texas Insurance Code establishes mandatory deadlines for insurers to acknowledge, investigate, and accept or reject claims. You can review the prompt payment provisions in Chapter 542.

One deadline is particularly useful when an insurer stalls. Under Tex. Ins. Code § 542.055(a), not later than the 15th day after receiving notice, the insurer must acknowledge receipt, commence investigation, and request reasonably required items. An insurer that sits on a claim without investigating may already be violating this statute.

💡 Pro Tip: Send your claim and supporting documents in a way that creates proof of delivery. Establishing the exact date the insurer received notice starts the statutory clock and can expose delayed or absent investigation.

Insurer Obligation Governing Provision What It Requires
Reasonable investigation § 541.060(a)(7) No denial without investigating the claim
Prompt, fair settlement § 541.060(a)(2) Settle when liability is reasonably clear
Reasonable explanation § 541.060(a)(3) Explain the denial under policy and facts
15-day acknowledgment § 542.055(a) Acknowledge, investigate, and request items

When an Insurer Hides Behind a Biased Expert Report

Carriers often deny storm claims by pointing to an engineering or causation report, but that report is not automatically a shield. Citing State Farm Lloyds v. Nicolau, 951 S.W.2d 444, 448 (Tex. 1997), Texas courts have held that an insurer may still be liable for bad faith if there is evidence the report was not objectively prepared or the insurer’s reliance was unreasonable.

The Hamilton case shows what lack of independence looks like. Evidence showed the insurer’s engineer was on the carrier’s approved list, that the insurer had retained the engineer on 1,440 claims and paid him more than $3.3 million over four years, and that the engineer had never testified against the insurer’s interests. From these facts, the court recognized in Hamilton, 265 S.W.3d at 735, that a jury could question the engineer’s objectivity.

A jury can also scrutinize the report’s substance. As noted in Hamilton, 265 S.W.3d at 736, 37, a jury may find that the report contained conflicts, didn’t state adequate grounds for conclusions, or failed to address alternative causes of damage. This is why independent documentation matters when challenging an insurer ignoring evidence.

Building a Record an Insurer Cannot Easily Dismiss

Strong, organized evidence is your best defense against a dismissive carrier. Policyholders who succeed generally create a documented file that an insurer must address directly. Consider preserving:

  • Dated photographs and video of damage before and after temporary repairs
  • Written estimates from licensed contractors and roofers
  • Independent inspection or engineering reports addressing causation
  • Complete log of every communication with the insurer and its adjuster

Even a thorough file does not guarantee a particular outcome. Bad faith claims are highly fact-dependent, and courts evaluate the reasonableness of the insurer’s conduct based on the specific record. A skilled Houston insurance dispute lawyer can help assess whether your facts support a viable claim. For more guidance, our denied insurance claims resource page explains how these cases are typically built.

What a Bad Faith Insurance Attorney in Houston Can Pursue for You

A successful bad faith claim can deliver remedies beyond the disputed policy amount. Tex. Ins. Code § 541.151 gives any person who sustains actual damages the right to bring a direct action against an insurer for unfair or deceptive practices. A Houston homeowner doesn’t need to wait for a government agency to act.

Recoverable damages can be substantial. Under Tex. Ins. Code § 541.152(a), a prevailing plaintiff may obtain actual damages plus court costs and reasonable attorney’s fees, along with other relief the court determines proper. Where the trier of fact finds the insurer knowingly committed the act complained of, Tex. Ins. Code § 541.152(b) permits an award of up to three times actual damages.

💡 Pro Tip: A reasonable explanation violation can stand on its own. As one federal court observed in S. Tex. Med. Clinics v. CNA Fin. Corp. (S.D. Tex. 2008), lack of coverage doesn’t automatically bar recovery for violating Chapter 541’s reasonable explanation provision.

Working with a Texas insurance bad faith attorney early helps preserve your evidence and options. A lawyer can evaluate whether the carrier’s investigation was genuine, whether any expert report was objectively prepared, and whether statutory deadlines were missed. You can find additional articles on insurer conduct and policyholder rights on our insurance law blog.

Frequently Asked Questions

1. Does ignoring my contractor’s estimate always mean my insurer acted in bad faith?

Not automatically. While disregarding credible evidence can support a bad faith finding, Hamilton makes clear that erroneous denial alone is insufficient. Courts look for something more, such as unreasonable investigation or reliance on a non-objective report.

2. How quickly must my insurer respond after I file a homeowner’s claim?

Generally within 15 days. Under Tex. Ins. Code § 542.055(a), the insurer must acknowledge the claim, commence investigation, and request needed items. A carrier that does nothing may be violating the Prompt Payment of Claims Act.

3. Can I sue my insurance company directly for bad faith in Texas?

Yes. Tex. Ins. Code § 541.151 allows a person who suffers actual damages to file a private lawsuit. You don’t have to wait for a regulator, though outcomes depend on specific facts.

4. What if my insurer relied on its own engineer’s report to deny me?

That report can be challenged. Under Nicolau, an insurer may face liability if the report was not objectively prepared or its reliance was unreasonable. Independent expert evidence is often key to rebutting it.

5. Are treble damages guaranteed if I win a bad faith case?

No. Enhanced damages under Tex. Ins. Code § 541.152(b) require a finding that the insurer knowingly committed the act, and the additional award is discretionary, not automatic.

Protecting Your Claim When the Carrier Won’t Listen

An insurer that ignores your evidence is not simply being difficult; it may be violating Texas law. When a carrier denies a claim without reasonable investigation, hides behind a biased report, or fails to provide real explanation, Chapters 541 and 542 give you meaningful recourse. The strongest cases pair thorough documentation with clear-eyed understanding that every result depends on the facts.

If you believe your Houston homeowner claim was ignored or wrongfully denied, don’t face the insurance company alone. Contact a dedicated bad faith insurance attorney Houston homeowners rely on at Fitts Law Firm, PLLC by calling 713-871-1670 or sending us a message through our secure contact form to learn how we can help.