Category: Insurance Disputes

This is a sample category description, which can be used to boost SEO rankings. Make sure you have enabled this from the Edit Category screen in your dashboard.

bank teller stamping signed check and document at wooden counter

How Long Can a Mortgage Company Hold an Insurance Check in Texas?

Why Your Insurance Money May Be Stuck With Your Lender

Key Takeaways: Texas law does not give a lender one blanket period to hold an insurance check, but it does set specific deadlines. Under Texas Insurance Code Chapter 557, a lender holding proceeds for repairs must notify the homeowner of its requirements within 10 days of receiving the proceeds. Within 10 days of a release request, it must either release the funds, if it has sufficient evidence of compliance, or explain in writing why it is refusing and what is still required. If a lender fails to give required notice, 10% annual interest may begin on the date it received the proceeds. Insurers have separate deadlines under the Texas Prompt Payment of Claims Act, so lender delays and insurer delays raise different legal issues. Homeowners can speed up a release by requesting the lender’s requirements in writing, documenting every submission with proof of delivery, and scheduling inspections early.

Texas Insurance Code Chapter 557 sets 10-day deadlines for what a lender must do once it receives your homeowners insurance proceeds and once you ask for them to be released. For Houston homeowners repairing storm, hail, or hurricane damage, a mortgage company holding an insurance check can leave a roof uncovered and a family displaced. Knowing these rules can help you push back.

If your lender is holding up your repair funds, or your insurer has delayed or underpaid your claim, Fitts Law Firm, PLLC can review your situation and explain your options. Call 713-871-1670 or contact us now to talk about your claim.
office worker reviewing manila folders and spreadsheet at desk with Texas mug

Why Lenders End Up With Your Insurance Check

Your lender is often on the check because your loan documents require it. Property insurance payments are often issued as two-party checks naming both the homeowner and the mortgage lender, because the mortgage agreement and the policy’s mortgage clause name the lender as a payee. The check generally needs endorsements from both payees before the money can be used.

This arrangement is common after disasters across the Houston area. After a hurricane or major hailstorm, many homeowners learn they cannot simply deposit their claim check. The lender may deposit it into a loss draft account, then release money in stages as repairs progress. That can make sense, but it can also cause long delays that leave repairs unfinished.

Similar Rules Apply in Other Ownership Arrangements

Texas uses joint payment in more situations than standard mortgages. If you are buying a home through a contract for deed, Texas Property Code § 5.078(b) requires the insurer to issue proceeds jointly to the purchaser and the seller. Under § 5.078(c)-(d), both parties must make sure the proceeds are used to repair, remedy, or improve the property. Failing to do so is a deceptive act under Texas Business and Commerce Code § 17.46 and may support a claim under the Texas Deceptive Trade Practices Act, depending on the circumstances.

Houston condominium owners face a different structure. Under the Texas Uniform Condominium Act, Texas Property Code § 82.111 generally requires the association or insurance trustee to hold proceeds from the association’s policy in trust for unit owners and lienholders. That money generally must go first to repairing damaged common elements and units, subject to limited exceptions. This explains why a condo owner may never get a direct check.

What Texas Law Requires of a Mortgage Company Holding an Insurance Check

Texas generally does not let a lender hold insurance money for as long as it wants. Texas Insurance Code Chapter 557 imposes two core duties on lenders that hold insurance proceeds for damaged residential property while repairs are pending: notice to the homeowner under §§ 557.002 and 557.003, and release of the proceeds under § 557.003 once the lender has sufficient evidence that the homeowner met its stated requirements.

The Notice Obligation

The lender must tell you what it needs before it releases your money. Under § 557.002, the lender must notify you of each requirement for release within 10 days after it receives the proceeds. That notice typically lists required documents, such as signed contractor agreements, repair estimates, lien waivers, or inspection results. Without it, homeowners often guess at what the lender wants, creating more delay. A lender that skips this step may owe interest under the statute.

The Release Obligation

Once you satisfy the lender’s requirements, the lender must release the funds. Under § 557.003, within 10 days after receiving your request for release, the lender must either release the requested proceeds, if it has sufficient evidence of compliance, or send notice that specifically explains why it is refusing and what you still need to do. Many disputes start here. Homeowners often send documents several times, only to hear that something is missing. A dated record of every submission can matter a great deal if the lender later disputes when it received your proof.

When Interest Starts Running on Withheld Funds

Texas Insurance Code § 557.004 requires a lender that violates these duties to pay interest at 10% a year on the proceeds it holds, and § 557.005 sets when that interest starts. The table below summarizes the statutory triggers.

Lender’s Failure When Interest Begins When Interest Stops
Failed to give required notice (§ 557.002 or § 557.003) Date the lender received the insurance proceeds, per § 557.005(a) Date the lender complies, per § 557.005(c)
Failed to release proceeds after homeowner met requirements (§ 557.003) Date the lender received sufficient evidence of compliance, per § 557.005(b) Date the lender complies, per § 557.005(c)

The longer a lender improperly holds the money, the more interest it may owe. Under § 557.006, interest is generally not required on proceeds properly applied to reduce the loan balance. Whether interest applies in your case depends on the facts, including what the lender asked for and when it received your documentation.

💡 Pro Tip: Send documents by a method that creates proof of delivery, such as certified mail or a servicer portal that issues confirmation receipts. Under § 557.005(b), the date the lender received sufficient evidence can control when interest begins.

How Insurer Delays Fit Into the Picture

Before money ever reaches your lender, your insurer has its own deadlines. The Texas Prompt Payment of Claims Act, Texas Insurance Code Chapter 542, Subchapter B (§§ 542.051 through 542.061), sets timelines for insurers to acknowledge, investigate, accept or reject, and pay covered claims. For example, § 542.055 generally requires an insurer to acknowledge a claim, begin investigating, and request needed information within 15 days of notice (30 days for eligible surplus lines insurers), with extended deadlines possible after a declared weather-related catastrophe. If an insurer violates these deadlines and is liable for the claim, it may owe statutory interest and reasonable attorney’s fees under § 542.060, subject to the limits that apply to many weather-related claims under Chapter 542A.

Lender delays and insurer delays raise different legal issues. A lender’s duties come mainly from Chapter 557 and your loan documents. Your insurer’s duties come from your policy, Chapter 542, and other provisions of the Insurance Code. Many Houston homeowners face both problems at once: an underpaid claim and a slow release. A mortgage company holding insurance check lawyer can help sort out which party may be responsible for which delay.

Where Regulators Come In

State and federal agencies oversee both sides of this process, but complaints to them work separately from lawsuits. The Texas Department of Savings and Mortgage Lending regulates many residential mortgage servicers, though other agencies oversee banks and credit unions. Servicers must also follow federal rules such as RESPA. The Texas Department of Insurance oversees insurers. A regulatory complaint can create a paper trail, but it generally does not replace a civil claim for money owed.

Practical Steps to Speed Up a Texas Insurance Check Release

Organized documentation is often the strongest tool a homeowner has. Consider these steps:

  • Ask your servicer in writing for its complete list of requirements for releasing loss draft funds.
  • Keep copies of every check, endorsement, estimate, and contractor contract.
  • Write down the date, method, and recipient of every document you send.
  • Request written confirmation each time the lender receives your materials.
  • Get independent repair estimates if your insurer’s estimate seems too low.

Watch for a common trap: the shifting checklist. Some servicers add new requirements after a homeowner has already complied. If that happens, ask in writing why the new item is needed and save the response. Section 557.003 requires a refusal notice to explain the reason specifically, so that record may matter to any later claim for interest. You can find more guidance in our homeowners insurance claim articles.

💡 Pro Tip: If your lender releases funds in stages, schedule required inspections as early as you can. Inspection backlogs after major Houston storms often cause more delay than the paperwork does.

Frequently Asked Questions

1. Is there a fixed number of days a lender can hold my insurance check in Texas?

There is no single overall holding period, but Chapter 557 sets 10-day deadlines. The lender must give notice of its requirements within 10 days of receiving the proceeds, and respond within 10 days of your release request by releasing the funds or explaining in writing why it won’t. Interest at 10% a year may accrue under §§ 557.004 and 557.005 if it fails to do so.

2. Can my lender apply my insurance check to my loan balance instead of repairs?

That depends on your loan documents and the facts, including whether the loan is in default. Chapter 557 does not prohibit this, and § 557.006 generally excuses interest on proceeds applied to reduce the loan. Reviewing your mortgage contract is an important first step.

3. What counts as "sufficient evidence" that I met the lender’s requirements?

This usually means the documents the lender listed in its notice, such as contractor bids, signed contracts, or inspection reports. The statute does not define the term, so disputes depend on the facts. Keeping proof of delivery can matter.

4. Does the Texas Prompt Payment of Claims Act apply to my mortgage company?

Generally, no. The Act governs insurers rather than lenders. Lender obligations come mainly from Chapter 557, your loan agreement, and federal servicing rules.

5. What if my insurer underpaid the claim and my lender is also delaying?

These may be two separate problems with separate remedies. An underpayment may support a breach of contract or Prompt Pay claim against the insurer, while a lender delay may trigger interest under Chapter 557.

Moving Your Repair Funds Forward

Texas law may give homeowners useful tools when their insurance proceeds get stuck. Chapter 557 requires lenders to give timely notice and release funds once homeowners comply, and it imposes 10% annual interest for certain failures. Your results will depend on your loan terms, your policy, and how carefully you document each step.

If your lender is holding your claim money or your insurer has delayed, denied, or underpaid your claim, Fitts Law Firm, PLLC can help you understand your rights under Texas law. Call 713-871-1670 or schedule your consultation today.

Disclaimer: This content is for informational purposes only and is not legal advice. Every case is unique, and results may vary. Consult an attorney about your specific circumstances.
man holding clipboard gesturing toward brick house roof during property inspection

How the 10% Adjuster Commission Limit Protects Houston Homeowners

What Every Houston Policyholder Should Know Before Signing With a Public Adjuster

Key Takeaways: Texas Insurance Code § 4102.104(a) caps a public insurance adjuster’s total commission at 10 percent of the insurance settlement. Under 28 Tex. Admin. Code § 19.708(b)(11), expenses and direct costs fold into that ceiling so charges cannot be stacked. Additional safeguards include a 72-hour carve-out barring percentage commissions when an insurer promptly pays policy limits under Tex. Ins. Code § 862.053, a requirement that the insured be named as payee, and a prohibition on adjusters endorsing claim checks. Every adjuster must use a TDI-prescribed written contract executed in duplicate. Red flags include commissions above 10 percent, off-form contracts, waiver language, and pressure to sign immediately. Because a fee cap does not fix an improper denial and adjusters cannot practice law, denied or underpaid claims may require an attorney’s review.

After a hailstorm or hurricane damages your Houston home, public adjusters often arrive quickly, offering to handle your claim for a percentage of the settlement. Texas law limits that percentage. Under Texas Insurance Code § 4102.104(a), a licensed public insurance adjuster’s total commission may not exceed 10 percent of the insurance settlement.

If your storm claim has been denied, underpaid, or stalled, the team at Fitts Law Firm, PLLC is available to review your situation. Call 713-871-1670 or reach out through our contact page to discuss your options.

woman seated at wooden table reviewing legal documents with pen in hand

The Statutory Fee Ceiling in Texas Chapter 4102

Texas Insurance Code Chapter 4102 governs who may act as a public insurance adjuster and how they may be paid. Section 4102.104(a) permits several compensation structures, hourly fee, flat rate, percentage, or another method, but the 10 percent adjuster commission ceiling applies regardless of structure.

You can read the full Texas public insurance adjuster statute to see how compensation provisions fit within the licensing framework.

Expenses and Costs Count Toward the Cap

The cap is not a base-fee cap with room for add-ons. Under 28 Tex. Admin. Code § 19.708(b)(11), the total commission payable to the public insurance adjuster, including expenses, direct costs, or any other costs accrued, must not exceed 10 percent of the insurance settlement. Mileage, photography, estimating software, and administrative fees cannot be stacked on top of the commission.

Many homeowners are surprised when contracts separate "fee" from "costs." A careful contract review often reveals that the combined figure exceeds the regulatory limit.

Why the Public Adjuster Fee Cap Texas 4102.104 Rule Exists

Statutory fee limits exist because policyholders negotiate from urgency and information asymmetry. Chapter 4102 pairs licensing requirements with detailed limits on compensation, solicitation, and contract form. A homeowner who has just lost a roof rarely has time to comparison-shop or evaluate whether a proposed percentage is customary.

The public adjuster fee cap texas 4102.104 framework removes the highest-risk term from the bargaining table.

The 72-Hour Policy Limit Carve-Out

One carve-out protects homeowners on claims the insurer would have paid quickly. Under Tex. Ins. Code § 4102.104(b), if the insurer pays or commits in writing to pay the policy limit within 72 hours after the loss is reported in accordance with Tex. Ins. Code § 862.053, the public adjuster may not receive a percentage-based commission and is instead entitled to reasonable compensation based on time spent and expenses incurred.

Consider a total-loss fire where the carrier immediately tenders limits. A percentage commission would transfer substantial recovery for minimal adjusting work.

Payment Safeguards Beyond the Percentage

Chapter 4102 also controls how settlement money moves. Section 4102.104(c) generally requires that persons paying policy proceeds include the insured as a payee. Section 4102.104(e) provides that a public adjuster may not sign and endorse any payment draft or check on behalf of an insured, regardless of authorization.

These provisions prevent funds intended for repairs moving without the owner’s knowledge. Chapter 4102 also restricts referral-related payments, including accepting fees for referring insureds to attorneys, contractors, or salvage companies.

Protection Authority What It Means for You
10% total commission cap Tex. Ins. Code § 4102.104(a) Adjuster fees cannot exceed 10% of the settlement
Expenses included in cap 28 Tex. Admin. Code § 19.708(b)(11) No stacking costs on top of the commission
No percentage on fast limits payment Tex. Ins. Code § 4102.104(b) Time-based pay only if limits paid within 72 hours
Insured named on payments Tex. Ins. Code § 4102.104(c), (e) Your endorsement is required; adjuster cannot sign
Approved written contract required 28 Tex. Admin. Code § 19.708(a), (d) Oral or off-form agreements are not permitted

The Written Contract Requirement Is Not a Formality

A public adjuster cannot legally operate in Texas without a signed written contract. Under 28 Tex. Admin. Code § 19.708(a), a public insurance adjuster may not act within this state without first entering into a written contract executed in duplicate by the licensee and the insured. The duplicate-execution requirement means you receive your own signed copy.

The contract must use a form prescribed by the Texas Department of Insurance: either the standard form FIN 535 developed by the department, or a contract filed with and approved by the department before use. Under 28 Tex. Admin. Code § 19.708(c)-(d), the contract must not limit or nullify any Insurance Code requirements.

💡 Pro Tip: Photograph every page of the signed contract, including the signature page and attachments, on the day you sign. Contemporaneous documentation is more persuasive than memory if disputes arise.

Required Consumer Notice and Complaint Channel

Every compliant contract must tell you where to go if something goes wrong. Under 28 Tex. Admin. Code § 19.708(b), the contract must include "IMPORTANT NOTICE" language directing insureds to contact the Texas Department of Insurance at 1-800-252-3439 to learn about consumer rights or file a complaint. The rule also requires disclosure of your right to cancel.

A regulatory complaint is separate from any civil lawsuit against your insurer. Our guide on strengthening a TDI complaint explains how to build a record regulators can act on.

Enforcement and Deceptive Practice Exposure

Contract rules carry real consequences for adjusters who ignore them. Under 28 Tex. Admin. Code § 19.708(f), failure to use a properly authorized and approved contract may result in suspension, nonrenewal, revocation of the adjuster’s license, or other administrative penalty.

Texas consumer law adds another layer. Under the Texas Deceptive Trade Practices Act, specifically Tex. Bus. & Com. Code § 17.46(b)(32), it is a prohibited practice for a licensed public insurance adjuster to solicit employment for an attorney or enter into a contract primarily to refer the homeowner to an attorney without intending to perform normal adjusting services.

Warning Signs in a Post-Storm Adjuster Contract

Certain patterns should prompt a closer look before you sign:

  • A commission figure above 10 percent, or a percentage plus separate "expense" or "administrative" charges
  • Anything other than a department-prescribed or department-approved form, or a contract missing the TDI notice and phone number
  • Language purporting to waive rights under the Insurance Code or department rules
  • A request that the adjuster be allowed to endorse or deposit claim checks
  • Pressure to sign immediately, before you have read the document or kept a copy

💡 Pro Tip: If an adjuster’s percentage was applied to a settlement including amounts the carrier had already committed to pay before the adjuster was retained, ask for a written breakdown of how the commission was calculated.

Where a Denied or Underpaid Claim Fits Into the Picture

Fee-cap questions often surface only after the underlying claim goes sideways. A homeowner hires an adjuster, the carrier denies or substantially underpays, and suddenly the arithmetic of who gets paid becomes urgent. The adjuster’s compensation rules under Chapter 4102 are distinct from your rights against the insurer, which arise under your policy and the Insurance Code’s claim-handling and prompt-payment provisions.

That distinction matters. Capping an adjuster’s fee does not fix an improper denial, and Tex. Ins. Code § 4102.156 prohibits a public adjuster from engaging in the practice of law, so an adjuster cannot represent you in court or file suit on your behalf. If your insurance claim has been denied, delayed, or disputed after a hail, wind, or hurricane loss, working with a denied claim help attorney can clarify whether appraisal, a regulatory complaint, or litigation is the appropriate route.

Frequently Asked Questions

1. Can a Houston public adjuster charge more than 10 percent if I agree in writing?

No. Tex. Ins. Code § 4102.104(a) caps the total commission at 10 percent of the insurance settlement, and 28 Tex. Admin. Code § 19.708(c) provides that contracts must not contain terms limiting or nullifying Insurance Code requirements.

2. Does the adjuster fee limit in Texas include costs like drone inspections or estimating fees?

Yes. Under 28 Tex. Admin. Code § 19.708(b)(11), the total commission including expenses, direct costs, or any other costs accrued must not exceed 10 percent of the settlement.

3. What happens if my insurer pays policy limits within days of the storm?

If the insurer pays or commits in writing to pay the policy limit under Tex. Ins. Code § 862.053 within 72 hours after the loss is reported, Tex. Ins. Code § 4102.104(b) provides that the adjuster may not receive a percentage commission and is instead entitled to reasonable compensation based on time spent and expenses incurred.

4. Can a public adjuster deposit my insurance settlement check?

No. Tex. Ins. Code § 4102.104(e) provides that a public adjuster may not sign and endorse any payment draft or check on behalf of an insured, even if the insured purported to authorize it, and § 4102.104(c) generally requires that proceeds payments include the insured as a payee.

5. Is a public adjuster the same as a lawyer for a denied claim?

No. A public adjuster assists with valuing and presenting a claim and is barred from practicing law under Tex. Ins. Code § 4102.156, while breach-of-contract and bad-faith claims against a carrier involve legal representation.

Protecting Your Recovery After a Texas Storm Loss

The 10 percent ceiling in Tex. Ins. Code § 4102.104(a) is deliberately simple. Combined with the mandatory written contract under 28 Tex. Admin. Code § 19.708, the inclusion of expenses within the cap, the 72-hour carve-out for prompt limits payments, and the payment-endorsement safeguards, Chapter 4102 gives Houston homeowners defined protections that do not depend on negotiating skill. Understanding these rules before you sign helps ensure that more of a storm claim settlement stays with the property owner paying for repairs.

If you are dealing with a denied, underpaid, or delayed property insurance claim in the Houston area, Fitts Law Firm, PLLC is prepared to review your policy and your options. Call 713-871-1670 or schedule a consultation today to get started.

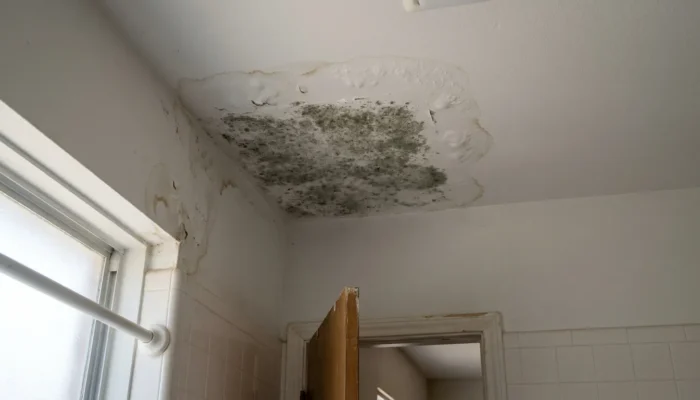
mold growth and water damage on interior ceiling of residential bathroom

What Is a Mold Remediation Coverage Limit on a Houston Homeowners Policy?

Understanding the Dollar Cap Insurers Place on Mold Cleanup in Houston Homes

Key Takeaways: A mold remediation coverage limit is the maximum amount a homeowners policy will pay to remove, clean, and treat mold after a covered loss, typically a small sublimit in Texas rather than your full dwelling limit. Texas Occupations Code § 1958.001(6) defines mold remediation broadly, covering removal, cleaning, sanitizing, demolition, and preventive work. After Texas Department of Insurance rulemaking reshaped homeowners forms, many policies now exclude mold generally, then carve back coverage for ensuing mold from sudden and accidental water discharge, while separately limiting or excluding remediation and testing costs. Baseline sublimits typically start near $5,000, while purchased endorsements can raise coverage to higher amounts or, on some forms, full policy limits. Coverage disputes turn on causation, policy wording, deductibles, and valuation method. Section 544.303 restricts how insurers use prior mold claims in underwriting when its conditions are met, though the subchapter’s definition of "insurer" excludes surplus lines carriers, TWIA, and the FAIR Plan. Careful documentation, a full policy copy with endorsements, and independent assessment are the most effective responses to denied or underpaid mold claims.

A mold remediation coverage limit is the maximum dollar amount your homeowners policy will pay to remove, clean, and treat mold after a covered loss, and in Texas that number is usually far smaller than your dwelling limit. Under Texas Occupations Code § 1958.001(6), "mold remediation" means the removal, cleaning, sanitizing, demolition, or other treatment, including preventive activities, of mold or mold-contaminated matter that was not purposely grown at that location. That definition matters because a policy cap written around that category reaches more than the visible patch of drywall, though what your policy covers depends on its defined terms. Many Houston policies pay for ensuing mold damage from sudden and accidental water discharge while separately capping, or excluding, remediation and testing costs.

If your insurer has denied, delayed, or underpaid a mold claim, the team at Fitts Law Firm, PLLC can review your policy language and the adjuster’s findings. Call 713-871-1670 or contact us now to discuss your options with a Houston insurance claim attorney.

Tyvek-suited inspector using moisture meter near mold-damaged wall with caution tape

How the Texas Department of Insurance Shaped Mold Coverage Limits

The caps on your policy did not appear at random. After costly mold litigation in the early 2000s, Texas regulators and the Legislature moved away from promulgated homeowners forms, allowing carriers to file their own forms rather than carry the broad water and mold exposure the standard forms had required. The Texas Department of Insurance acknowledged that consumers may be offered policies with substantially reduced water damage and mold damage coverage compared with what was previously available. That regulatory shift is why modern Houston homeowners policies commonly contain mold sublimits rather than full dwelling-limit protection.

Mandatory endorsement language does much of the work. The TDI mold endorsement language generally excludes loss caused by mold, then carves back coverage for ensuing mold damage from sudden and accidental discharge of water, while stating the policy does not cover remediation costs, including testing, unless remediation coverage is added. Reading those provisions together is where most disputes begin. A carrier may concede the water loss was covered yet argue the decontamination invoice falls outside the policy or above the sublimit.

What the Limit Typically Looks Like

Texas mold policy limits are usually expressed as a flat dollar figure or a percentage of Coverage A. Regulators developed approaches permitting insurers to provide a minimum level of mold remediation coverage, such as $5,000, unless the policyholder purchases broader coverage. Homeowners who want more protection buy it through an approved endorsement, with specific options varying by carrier and filed form.

Coverage Approach What It Generally Means
Baseline sublimit A modest built-in cap, often around $5,000
Purchased endorsement Higher selected caps, such as $15,000, $25,000, or $50,000
Full policy limits option Available on some approved forms, subject to underwriting
No remediation coverage Testing and decontamination excluded entirely

Why Your Mold Remediation Coverage Limit Texas Homeowners Rely On May Not Apply

A sublimit only helps if the underlying loss is covered. Mold that develops as a secondary problem from covered water damage may qualify for remediation payment, making the cause of loss the central battleground. Insurers frequently argue the moisture came from long-term seepage, maintenance failure, or flooding rather than a sudden pipe break. Our discussion of policy exclusions in Houston claims walks through the mechanics.

Policy type also influences the analysis. Some property policies are written on an all-risk basis, where the insured proves a covered loss and the insurer bears the burden of proving an exclusion applies. Most forms contain exclusion lists covering mold, rot, corrosion, wear and tear, and faulty workmanship. Many Texas homeowners forms also exclude perils such as sewer backup and dry rot absent an endorsement. Whether a particular exclusion defeats your claim depends on specific wording and causation evidence.

  • Sudden and accidental discharge: generally the strongest posture for ensuing mold coverage
  • Long-term leak: frequently disputed and often excluded, subject to policy wording
  • Flood or surface water: typically outside a standard homeowners policy altogether
  • Construction or repair defects: commonly excluded, though ensuing loss clauses may matter

💡 Pro Tip: Photograph and date every stage of the water intrusion before remediation begins. Once affected material is removed, proving the moisture was sudden rather than gradual becomes considerably harder.

Texas law limits how carriers may treat prior mold history. Under Tex. Ins. Code § 544.303, an insurer may not make an underwriting decision regarding a residential property insurance policy based on previous mold damage or a mold damage claim if all statutory conditions are met: the applicant has property eligible for coverage, the property had mold damage, mold remediation was performed, and the property was either remediated as evidenced by a certificate of mold remediation issued under § 1958.154 of the Occupations Code, or inspected by an independent assessor who determined the property does not contain evidence of mold damage. Because the test is conjunctive, missing documentation can defeat the protection.

That protection does not reach every carrier. Section 544.301 defines "insurer" for the subchapter in a way that excludes eligible surplus lines insurers under Chapter 981, the Texas Windstorm Insurance Association under Chapter 2210, and the FAIR Plan Association under Chapter 2211. Houston homeowners placed with those entities may not receive the same statutory shield. Confirming which type of insurer holds your policy is a practical first step.

Reading Your Renewal Documents Carefully

Limits can change at renewal. Consumer advocates advise reviewing your policy after renewal to see whether mold coverage limitations have been inserted. A carrier may reduce a $25,000 Texas mold endorsement to a baseline sublimit, subject to any notice requirements that apply to policy changes. Prior water damage claims can also make coverage harder or costlier to obtain, and Section 544.353 separately restricts how water damage claims history may be used.

Practical Steps When a Houston Mold Claim Is Denied or Underpaid

Documentation drives outcomes in mold disputes. Because causation is fact-dependent, independent evidence often carries the day. Consider the following before accepting a denial or a payment capped at the sublimit:

  • Request the full policy, including every endorsement and declarations page
  • Obtain the insurer’s engineering or industrial hygiene report in writing
  • Retain an independent moisture or mold assessor to evaluate causation
  • Keep dated invoices separating structural repair from remediation and testing
  • Preserve written communications, including claim-handling correspondence

💡 Pro Tip: Ask the adjuster in writing to identify the exact policy provision and sublimit relied upon. A vague denial is much harder to defend once specific language is demanded.

How Deductibles and Valuation Interact With the Sublimit

Your deductible generally applies before the mold cap is reached. A deductible is the amount you must absorb after a loss before the insurer’s payment obligation begins. Valuation matters too: replacement cost, actual cash value, and guaranteed replacement cost each produce different payouts, and replacement cost policies often pay actual cash value until repairs are completed. Consumer resources explaining homeowners insurance basics can help you place a sublimit in context. In many cases, homeowners recover less than expected because the deductible and mold cap both reduce payment on a single loss.

Frequently Asked Questions

1. Does every Houston homeowners policy include mold remediation insurance?

Not necessarily. Many Texas forms exclude remediation costs unless a mold endorsement was purchased, so the answer depends on your declarations page and attached endorsements.

2. Can I raise my mold coverage limit?

Generally yes, subject to underwriting and availability. TDI-approved endorsements permit homeowners to select higher amounts, and some forms allow coverage up to policy limits, though options vary by carrier.

3. My insurer paid the water damage but refused the remediation invoice. Is that allowed?

It may be, depending on wording. Common language covers ensuing mold from sudden and accidental discharge while separately limiting remediation and testing costs, so the distinction is often legitimate but also frequently applied too broadly.

4. Can an insurer refuse to renew because of an old mold claim in Houston?

Section 544.303 restricts underwriting decisions based on prior mold damage or claims when remediation was completed and documented as the statute requires. It does not apply to insurers excluded from the subchapter’s definition, such as surplus lines carriers, TWIA, and the FAIR Plan.

5. How long do I have to challenge a denial?

Deadlines depend on your policy’s suit limitation provision and applicable Texas statutes of limitations. Courts generally construe tolling exceptions narrowly. Prompt review by counsel is advisable rather than assuming an extension applies.

Protecting the Coverage You Actually Paid For

A mold remediation coverage limit in Texas is a regulated, negotiated sublimit that reflects how Texas law and Department of Insurance rulemaking reshaped the mold exposure carriers assume. Understanding your endorsement, the ensuing-loss language, and the causation evidence gives you a realistic view of what your policy should pay. Every claim turns on its own facts, policy wording, and documentation.

If a carrier has capped, delayed, or denied your remediation payment, a mold remediation coverage limit texas lawyer at Fitts Law Firm, PLLC can evaluate your claim. Call 713-871-1670 or reach out today to get started.

man examining insurance check and envelope standing outside brick home

Can Houston Homeowners Demand Appraisal After an Underpaid Home Claim?

Understanding Your Right to Appraisal in Houston Home Insurance Disputes

Key Takeaways: Yes, Houston homeowners can demand appraisal after an underpaid home claim. Texas law gives policyholders the right to challenge the amount an insurer proposes to pay when coverage is accepted but the dollar amount is disputed, not when coverage is denied outright. Under new legislation, Texas residential policies issued or renewed on or after January 1, 2026 must include an appraisal provision with conspicuous notice of deadlines and binding effect of any award. The process follows strict deadlines, including a 60-day window to demand appraisal in the TWIA context and a four-year statute of limitations for breach-of-contract lawsuits. Homeowners retain remedies beyond appraisal, such as bad-faith and Chapter 541 claims. Acting quickly and identifying whether your dispute is about amount or coverage is essential.

Yes, Houston homeowners can generally demand appraisal after an underpaid home claim, and Texas law now makes that right clearer than ever. When your insurer accepts your claim but offers less than your loss is worth, appraisal provides a structured way to challenge that figure. This tool addresses disagreements over dollars, not whether coverage exists.

If your storm, hail, wind, or roof claim came back lower than expected, you do not have to accept the insurer’s number without a fight. Fitts Law Firm, PLLC helps policyholders across the region push back on lowball offers. Reach the firm through its main office website, by calling 713-871-1670, or by using the firm’s online case review form.

Texas Homeowner's Policy document, appraisal demand letter, and Houston Texas map on wooden table

When an Underpaid Claim Triggers the Appraisal Process

Appraisal applies when an insurer has accepted coverage but disputes the payment amount. Under the Texas Windstorm Insurance Association framework, appraisal applies when the association has accepted coverage for a claim, in full or in part, and the claimant disputes the amount of loss the association will pay. Appraisal resolves the "how much" question, not the "is it covered" question.

The scope of appraisal is intentionally narrow. Texas statute confirms the provision is intended to provide dispute resolution solely to determine the amount of loss when that amount is disputed between the policyholder and insurer. If your dispute concerns causation or a full denial, appraisal alone may not resolve it.

💡 Pro Tip: Before demanding appraisal, read your insurer’s decision letter closely. If it accepts the claim but pays too little, appraisal likely fits. If it denies coverage outright, you may need a different legal strategy.

Appraisal Is a Required Policy Provision in Texas

Texas now requires residential property insurance policies to include an appraisal provision. This applies to personal residential property policies delivered, issued for delivery, or renewed in Texas on or after January 1, 2026. Under Tex. Ins. Code Sec. 1813.003(a), an insurance policy described by Section 1813.001(a) must contain an appraisal provision that complies with this chapter. This chapter applies to personal automobile and residential property policies but does not reach commercial policies or the Texas Windstorm Insurance Association, which follows its own appraisal regime. You can review the full text through the Texas appraisal clause statute.

Policies must also provide conspicuous notice of these rights. In the TWIA context, Texas requires policies to contain conspicuous notice about dispute resolution, including processes and deadlines for appraisal under Section 2210.574 and the binding effect of appraisal. An appraisal outcome may bind both parties as to loss amount, subject to limited exceptions such as fraud or material mistake.

How the Texas Appraisal Framework Works

Once you demand appraisal, the process follows a defined, deadline-driven sequence. The steps below reflect the Texas Windstorm Insurance Association rules for TWIA policyholders; standard residential policies follow deadlines set under Chapter 1813. After a homeowner demands appraisal, the insurer must acknowledge the demand in writing not later than the 10th day after receipt, and both parties must each hire an independent, qualified appraiser.

The appraisers then work toward a valuation within bounded timelines. Appraisers must disclose fees and agree on an umpire within 15 days, and for residential claims agree on the loss amount within 90 days of the date by which both appraisers were named. This overview of the Houston home insurance appraisal process breaks down each step.

The insurer carries an affirmative duty to explain your options in writing. The association must include an explanation of the appraisal process and the process for requesting a supplemental payment with each acceptance/replacement-cost notice. You can read the current text in the published version of the Texas appraisal administrative rule.

💡 Pro Tip: Keep every letter, email, and estimate from your insurer in a dated folder. A clear paper trail often makes the difference when an appraisal or lawsuit turns on who said what and when.

These rules reflect current, recently updated Texas law. The Texas Windstorm Insurance Association appraisal rule reflects Texas legislation requiring a defined time period for completing appraisals, adopted by the Texas Department of Insurance to implement House Bill 3310, 88th Legislature, 2023, effective January 22, 2024. The broader appraisal requirement for personal residential and auto policies was added by Acts 2025, 89th Leg., R.S., Ch. 899 (S.B. 458), Sec. 1, creating Insurance Code Chapter 1813, which applies to policies issued or renewed on or after January 1, 2026.

Deadlines Every Houston Homeowner Should Track

Timing controls almost everything in an underpaid home insurance claim dispute. Under the TWIA framework, if a claimant disputes the loss amount the association will pay, the claimant may demand appraisal not later than the 60th day after receiving the notice. Deadlines to demand appraisal differ for standard residential policies under Chapter 1813, so always check your policy, but the practical takeaway is the same: act quickly.

A separate and longer clock governs lawsuits based on your policy. Texas applies a four-year statute of limitations to lawsuits based on contractual obligations under Texas Civil Practice and Remedies Code Sec. 16.051.

Letting a deadline pass generally forecloses your day in court. If a lawsuit is not filed during the statute of limitations period, a claimant will likely be unable to pursue the claim in court. Courts interpret tolling and discovery-rule exceptions narrowly, so no homeowner should assume a deadline will be extended.

Here are key deadlines Houston homeowners commonly encounter:

Action General Deadline Governing Authority
Demand appraisal after loss notice 60 days (TWIA context) Tex. Ins. Code Sec. 2210.574(b)
Insurer acknowledges appraisal demand 10 days 28 Tex. Admin. Code § 5.4211(c)
Appraisers agree on umpire 15 days 28 Tex. Admin. Code § 5.4211(e)
Agree on residential loss amount 90 days 28 Tex. Admin. Code § 5.4211(f)
File breach-of-contract lawsuit 4 years Tex. Civ. Prac. & Rem. Code Sec. 16.051

💡 Pro Tip: Calendar your deadlines the moment you receive any insurer notice. Timelines can run from the date you receive a letter, not the date you read it.

Why a Houston Appraisal Disputes Lawyer Can Help

A knowledgeable appraisal disputes lawyer can help you invoke the process correctly and protect other remedies. Appraisal is powerful, but it is not always the complete answer. Under Texas law, an appraisal award resolves only the loss amount, but the prompt payment of an appraisal award generally bars a policyholder from pursuing Chapter 541 of the Texas Insurance Code and common-law bad-faith claims, unless the policyholder can demonstrate an independent injury beyond the lost policy benefits. Chapter 542 (Prompt Payment of Claims Act) claims, however, may still be pursued after payment of an appraisal award. An attorney can help you decide whether appraisal, litigation, or both best fit your facts.

Some property-damage disputes also carry pre-suit notice rules that are easy to overlook. When a claim overlaps with construction or repair work, a claimant seeking construction-defect damages must give the contractor written notice by certified mail specifying the construction defects before the 60th day preceding initiating an action under Tex. Prop. Code Sec. 27.004(a).

Working with counsel that focuses on policyholder recovery keeps the pressure where it belongs. A firm experienced in handling homeowners insurance dispute Texas matters can gather independent estimates, rebut insurer engineering reports, and document bad-faith conduct. If your carrier issued a denied insurance claim Houston homeowners recognize as unfair, learning about your options for denied home insurance claim representation is a practical first step.

💡 Pro Tip: If an insurer pressures you into appraisal to avoid a coverage fight, pause and get guidance. Pushing appraisal on what is really a causation dispute can work against you.

Frequently Asked Questions

  1. Can I demand appraisal if my whole claim was denied?

Appraisal generally applies when coverage is accepted but the payment amount is disputed. The process is intended solely to determine the loss amount when that amount is disputed. A full denial usually raises coverage questions that appraisal alone may not resolve.

  1. How long do I have to demand appraisal in Houston?

Deadlines can be short and vary by policy and program. In the TWIA context, a claimant may demand appraisal not later than the 60th day after receiving notice. Deadlines differ for standard residential policies, so confirm the specific deadline in your policy.

  1. Is an appraisal decision binding on me?

It can be. Texas requires policies to disclose the binding effect of appraisal under Section 2210.574. An appraisal award may bind both sides as to loss amount, subject to limited exceptions such as fraud or material mistake.

  1. Does appraisal replace my right to sue?

Not necessarily. An appraisal award generally resolves only valuation. While prompt payment of an appraisal award typically bars Chapter 541 and common-law bad-faith claims absent an independent injury beyond lost policy benefits, Chapter 542 (Prompt Payment of Claims Act) claims may still be available.

  1. What is the deadline to file a lawsuit over an underpaid claim?

A four-year contract deadline generally applies. Texas applies a four-year statute of limitations to lawsuits based on contractual obligations. Waiting too long can bar your claim entirely.

Protecting Your Home Claim Before Time Runs Out

Houston homeowners facing an underpaid claim have real, statute-backed tools, and appraisal is often the fastest path to a fair number. Texas law now requires appraisal provisions in residential policies issued or renewed on or after January 1, 2026, sets firm deadlines for each step, and preserves your ability to pursue bad-faith and breach-of-contract remedies when appropriate. The key is acting within the applicable windows and understanding which process fits your specific dispute.

If your insurer underpaid your storm, hail, wind, or roof claim, do not wait for a deadline to close your options. Reach out to Fitts Law Firm, PLLC through the firm’s homepage, call 713-871-1670, or submit the confidential contact form to have your underpaid home insurance claim reviewed today.

Texas Department of Insurance Consumer Protection office counter with staff assisting visitor

Homeowner Insurance Complaints Tripled in Texas: How TDI Filings Help

Why Texas Homeowners Are Filing More Insurance Complaints

Key Takeaways: Homeowner insurance complaints have tripled in Texas as policyholders challenge denied, delayed, and underpaid property claims after major Gulf Coast storms. A TDI complaint is a written grievance filed with the Texas Department of Insurance that documents insurer misconduct, prompts regulator review, and builds a paper trail supporting litigation. Texas law reinforces these rights through Chapter 541 of the Insurance Code, which prohibits unfair settlement practices, misrepresentation, and unreasonable delay. Houston homeowners also face coverage gaps for flood and windstorm damage that often spark disputes after a loss. Homeowners can pursue appraisal, a TDI complaint, or court action, and a two-year limitations period under Chapter 541 makes timely action essential. Careful documentation and early legal guidance strengthen your position when a claim goes sideways.

Homeowner insurance complaints have surged across Texas, reflecting policyholders pushing back against denied, delayed, and underpaid property claims. After major storm seasons along the Gulf Coast, more Houston families discovered that agreeing coverage applies is only half the battle, because disputes over payout amounts often follow. A TDI complaint gives homeowners a formal, documented way to hold an insurer accountable when a claim goes sideways.

If your homeowner claim was denied or shortchanged, the team at Fitts Law Firm, PLLC is ready to help you evaluate your next step. Call us at 713-871-1670 or reach out through our online contact page to discuss your situation. Early guidance can make a meaningful difference.

inspector examining brick home exterior with visible structural cracks and warning flags

What a TDI Complaint Is and Why It Matters

A TDI complaint is a written grievance filed with the Texas Department of Insurance when a homeowner believes an insurer mishandled a claim, cancellation, or nonrenewal. According to TDI’s homeowner guidance, you may complain if you think a company improperly denied, canceled, or nonrenewed your policy. The agency also lists a consumer Help Line at 800-252-3439.

Filing does not replace a lawsuit, the two processes are separate. A TDI complaint is an administrative step that documents the dispute and prompts regulator review, while a civil breach-of-contract or bad-faith case proceeds through the courts. A well-documented complaint creates a paper trail that supports later litigation if the insurer refuses to resolve a legitimate claim.

💡 Pro Tip: Keep every letter, email, and adjuster report in one organized file. A clear timeline of communications strengthens both a TDI complaint and any later court action.

Texas Laws That Protect Homeowners After a Denied Claim

Texas law gives homeowners statutory protection when an insurer fails to handle a claim fairly. Chapter 541 of the Insurance Code prohibits unfair methods of competition and deceptive acts, and Tex. Ins. Code § 541.003 provides that a person may not engage in a trade practice defined as an unfair or deceptive act in the business of insurance.

Unfair Settlement Practices Under Chapter 541

The most common violations involve unfair settlement conduct. Under Tex. Ins. Code § 541.060, it is an unfair practice to misrepresent policy provisions, to fail to attempt in good faith a prompt and equitable settlement when liability has become reasonably clear, to fail to provide a reasonable explanation for a denial, or to refuse to pay a claim without conducting a reasonable investigation. The statute also treats the failure to affirm or deny coverage within a reasonable time as prohibited conduct.

These provisions matter because insurers must act once the facts support payment. Whether liability is "reasonably clear" is fact-dependent and may turn on causation evidence, independent inspections, and documentation strength.

Misrepresentation and Broader Prohibited Conduct

Chapter 541 reaches beyond slow payments and covers insurer misconduct including misrepresentation of policy terms under § 541.051, false advertising under § 541.052, and boycott or coercion under § 541.054.

Texas also recognizes extracontractual and bad-faith damages arising under Chapter 541. Tex. Ins. Code § 2602.255 confirms this by listing exemplary, extracontractual, or bad-faith damages among claims not covered by the title insurance guaranty association, reminding us that bad-faith remedies are treated separately from ordinary policy benefits.

The Deadlines Insurers Must Meet on a Home Claim

Texas sets specific claim-handling deadlines that homeowners can point to when an insurer stalls. Under the Prompt Payment of Claims Act in Chapter 542, companies must acknowledge your claim, decide on it, and pay within defined windows. These timelines give policyholders concrete benchmarks for measuring delay.

Claim Stage General Deadline
Acknowledge the claim Within 15 days
Accept or deny after receiving needed information Within 15 business days
Send payment after agreeing to pay Within 5 business days

These deadlines are general rules, and specific policy language or unusual facts can affect how they apply. For claims arising from a commissioner-declared weather catastrophe, standard deadlines are extended by 15 additional days. Chapter 542A imposes pre-suit notice requirements and interest calculation for storm-related property claims. For amount-only disputes involving windstorm and hail coverage through the Texas Windstorm Insurance Association, Tex. Ins. Code § 2210.574 sets out a statutory process for resolving disagreements over the payout when coverage is accepted.

💡 Pro Tip: Note the date you submit each document to your insurer. If a decision or payment runs past the statutory window, that delay may support a prompt-pay or bad-faith argument.

How Filing Helps Resolve a Property Insurance Dispute in Houston

A TDI complaint triggers regulator attention, documents the dispute, and often nudges insurers toward resolution. TDI’s homeowner guidance outlines three broad options: requesting an appraisal, filing a written complaint through the Online Complaint Portal, and pursuing the matter in court. Many Houston homeowners use them in combination.

Coastal and Flood Realities for Houston Homeowners

Houston’s geography shapes why complaints cluster in the region. Standard home policies generally exclude flood, and TDI notes that more than half of homes flooded by Hurricane Harvey sat outside designated flood zones. Homes in Harris County on Galveston Bay are not covered for wind and hail damage, which typically requires separate windstorm coverage through the Texas Windstorm Insurance Association.

These coverage gaps often surface only after a loss. Reviewing your declarations page before storm season can help you avoid an unwelcome surprise.

Three Paths to Resolve a Dispute

Homeowners generally have several tools, and choosing among them depends on the disagreement:

  • Appraisal: Useful when you agree coverage applies but dispute the amount, typically invoked under the appraisal clause in most property policies.
  • TDI complaint: A written filing through the Online Complaint Portal that documents alleged misconduct and prompts agency review.
  • Court action: A civil lawsuit for breach of contract or statutory violations when the insurer will not resolve a valid claim.

Because appraisal and administrative complaints differ from litigation, timing and strategy matter. An insurer may push appraisal to sidestep coverage or causation questions. A tdi complaint lawyer can help you assess whether appraisal, a complaint, litigation, or a combination fits your facts.

💡 Pro Tip: Independent inspections and engineering reports can rebut an insurer’s causation findings. Strong expert evidence often carries significant weight in a property insurance dispute in Houston.

Texas imposes a two-year limitations period for actions under Chapter 541. The limitations provision generally requires an action before the second anniversary of the date the unfair or deceptive act occurred or was reasonably discovered, with a possible 180-day extension in specified circumstances. Courts interpret discovery and tolling exceptions narrowly, so you should not assume more time is available.

Enforcement can take several forms. Chapter 541 provides for private actions for damages, enforcement by the Attorney General, class actions, and department action for refund of premiums. On rate concerns, TDI does not pre-approve rates but can require refunds when rates are found excessive.

Frequently Asked Questions

1. What is the difference between a TDI complaint and a lawsuit?

A TDI complaint is an administrative filing with the Texas Department of Insurance, while a lawsuit is a civil court action. The two are separate, and a complaint does not award damages. A documented complaint supports a later breach-of-contract or bad-faith case if the insurer refuses to resolve a valid claim.

2. How long do I have to bring a claim under Chapter 541?

Texas generally sets a two-year limitations period. The clock typically runs from when the unfair act occurred or was reasonably discovered, with a possible 180-day extension in limited circumstances. Because courts read these exceptions narrowly, acting promptly is wise.

3. Does homeowner insurance cover flood and windstorm damage in Houston?

Standard home policies generally exclude flood, and Gulf Coast wind and hail coverage often requires separate protection. TDI notes that many Harvey-flooded homes were outside designated flood zones, and certain Harris County homes on Galveston Bay lack wind and hail coverage. Review your policy before a storm to identify gaps.

4. What deadlines must my insurer meet after I file a claim?

Insurers generally must acknowledge a claim within 15 days, decide within 15 business days of receiving needed information, and pay within 5 business days of agreeing to pay. These are general benchmarks, with a 15-day extension for declared weather catastrophes. Missed deadlines may support a prompt-pay or bad-faith argument.

5. Can I file a complaint if my policy was canceled or nonrenewed?

Yes, TDI’s guidance states you may complain if a company improperly denied, canceled, or nonrenewed your policy. Companies must generally provide advance notice. If you believe the action was improper, documenting the notice and reasons is an important first step.

Protecting Your Home Claim in a Rising Tide of Complaints

As Texas homeowner complaints climb, understanding your rights under Chapter 541 and TDI’s process is essential. A TDI complaint can document insurer misconduct, prompt regulator review, and lay groundwork for legal action. Statutory deadlines and unfair-practice rules give you concrete standards to hold an insurer to. Because every claim turns on its own facts, careful documentation and timely action serve homeowners best.

When a denied or underpaid home claim leaves you uncertain about your next move, Fitts Law Firm, PLLC is here to guide you. Reach the Houston property claim team by calling 713-871-1670 or by visiting our secure contact form today. Taking action now can help protect both your home and your rights.