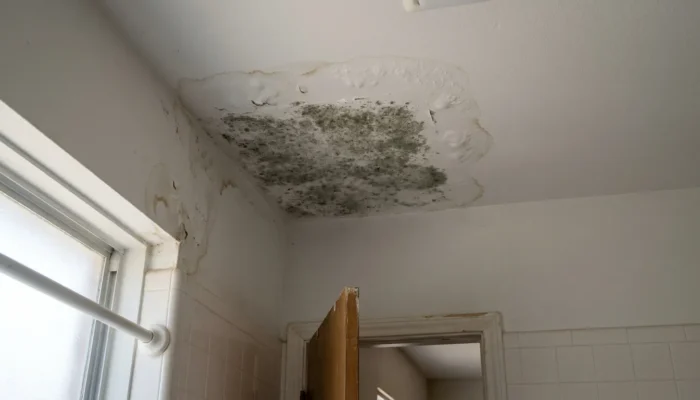
mold growth and water damage on interior ceiling of residential bathroom

What Is a Mold Remediation Coverage Limit on a Houston Homeowners Policy?

Understanding the Dollar Cap Insurers Place on Mold Cleanup in Houston Homes

Key Takeaways: A mold remediation coverage limit is the maximum amount a homeowners policy will pay to remove, clean, and treat mold after a covered loss, typically a small sublimit in Texas rather than your full dwelling limit. Texas Occupations Code § 1958.001(6) defines mold remediation broadly, covering removal, cleaning, sanitizing, demolition, and preventive work. After Texas Department of Insurance rulemaking reshaped homeowners forms, many policies now exclude mold generally, then carve back coverage for ensuing mold from sudden and accidental water discharge, while separately limiting or excluding remediation and testing costs. Baseline sublimits typically start near $5,000, while purchased endorsements can raise coverage to higher amounts or, on some forms, full policy limits. Coverage disputes turn on causation, policy wording, deductibles, and valuation method. Section 544.303 restricts how insurers use prior mold claims in underwriting when its conditions are met, though the subchapter’s definition of "insurer" excludes surplus lines carriers, TWIA, and the FAIR Plan. Careful documentation, a full policy copy with endorsements, and independent assessment are the most effective responses to denied or underpaid mold claims.

A mold remediation coverage limit is the maximum dollar amount your homeowners policy will pay to remove, clean, and treat mold after a covered loss, and in Texas that number is usually far smaller than your dwelling limit. Under Texas Occupations Code § 1958.001(6), "mold remediation" means the removal, cleaning, sanitizing, demolition, or other treatment, including preventive activities, of mold or mold-contaminated matter that was not purposely grown at that location. That definition matters because a policy cap written around that category reaches more than the visible patch of drywall, though what your policy covers depends on its defined terms. Many Houston policies pay for ensuing mold damage from sudden and accidental water discharge while separately capping, or excluding, remediation and testing costs.

If your insurer has denied, delayed, or underpaid a mold claim, the team at Fitts Law Firm, PLLC can review your policy language and the adjuster’s findings. Call 713-871-1670 or contact us now to discuss your options with a Houston insurance claim attorney.
Tyvek-suited inspector using moisture meter near mold-damaged wall with caution tape

How the Texas Department of Insurance Shaped Mold Coverage Limits

The caps on your policy did not appear at random. After costly mold litigation in the early 2000s, Texas regulators and the Legislature moved away from promulgated homeowners forms, allowing carriers to file their own forms rather than carry the broad water and mold exposure the standard forms had required. The Texas Department of Insurance acknowledged that consumers may be offered policies with substantially reduced water damage and mold damage coverage compared with what was previously available. That regulatory shift is why modern Houston homeowners policies commonly contain mold sublimits rather than full dwelling-limit protection.

Mandatory endorsement language does much of the work. The TDI mold endorsement language generally excludes loss caused by mold, then carves back coverage for ensuing mold damage from sudden and accidental discharge of water, while stating the policy does not cover remediation costs, including testing, unless remediation coverage is added. Reading those provisions together is where most disputes begin. A carrier may concede the water loss was covered yet argue the decontamination invoice falls outside the policy or above the sublimit.

What the Limit Typically Looks Like

Texas mold policy limits are usually expressed as a flat dollar figure or a percentage of Coverage A. Regulators developed approaches permitting insurers to provide a minimum level of mold remediation coverage, such as $5,000, unless the policyholder purchases broader coverage. Homeowners who want more protection buy it through an approved endorsement, with specific options varying by carrier and filed form.

Coverage Approach What It Generally Means
Baseline sublimit A modest built-in cap, often around $5,000
Purchased endorsement Higher selected caps, such as $15,000, $25,000, or $50,000
Full policy limits option Available on some approved forms, subject to underwriting
No remediation coverage Testing and decontamination excluded entirely

Why Your Mold Remediation Coverage Limit Texas Homeowners Rely On May Not Apply

A sublimit only helps if the underlying loss is covered. Mold that develops as a secondary problem from covered water damage may qualify for remediation payment, making the cause of loss the central battleground. Insurers frequently argue the moisture came from long-term seepage, maintenance failure, or flooding rather than a sudden pipe break. Our discussion of policy exclusions in Houston claims walks through the mechanics.

Policy type also influences the analysis. Some property policies are written on an all-risk basis, where the insured proves a covered loss and the insurer bears the burden of proving an exclusion applies. Most forms contain exclusion lists covering mold, rot, corrosion, wear and tear, and faulty workmanship. Many Texas homeowners forms also exclude perils such as sewer backup and dry rot absent an endorsement. Whether a particular exclusion defeats your claim depends on specific wording and causation evidence.

  • Sudden and accidental discharge: generally the strongest posture for ensuing mold coverage
  • Long-term leak: frequently disputed and often excluded, subject to policy wording
  • Flood or surface water: typically outside a standard homeowners policy altogether
  • Construction or repair defects: commonly excluded, though ensuing loss clauses may matter

💡 Pro Tip: Photograph and date every stage of the water intrusion before remediation begins. Once affected material is removed, proving the moisture was sudden rather than gradual becomes considerably harder.

Texas law limits how carriers may treat prior mold history. Under Tex. Ins. Code § 544.303, an insurer may not make an underwriting decision regarding a residential property insurance policy based on previous mold damage or a mold damage claim if all statutory conditions are met: the applicant has property eligible for coverage, the property had mold damage, mold remediation was performed, and the property was either remediated as evidenced by a certificate of mold remediation issued under § 1958.154 of the Occupations Code, or inspected by an independent assessor who determined the property does not contain evidence of mold damage. Because the test is conjunctive, missing documentation can defeat the protection.

That protection does not reach every carrier. Section 544.301 defines "insurer" for the subchapter in a way that excludes eligible surplus lines insurers under Chapter 981, the Texas Windstorm Insurance Association under Chapter 2210, and the FAIR Plan Association under Chapter 2211. Houston homeowners placed with those entities may not receive the same statutory shield. Confirming which type of insurer holds your policy is a practical first step.

Reading Your Renewal Documents Carefully

Limits can change at renewal. Consumer advocates advise reviewing your policy after renewal to see whether mold coverage limitations have been inserted. A carrier may reduce a $25,000 Texas mold endorsement to a baseline sublimit, subject to any notice requirements that apply to policy changes. Prior water damage claims can also make coverage harder or costlier to obtain, and Section 544.353 separately restricts how water damage claims history may be used.

Practical Steps When a Houston Mold Claim Is Denied or Underpaid

Documentation drives outcomes in mold disputes. Because causation is fact-dependent, independent evidence often carries the day. Consider the following before accepting a denial or a payment capped at the sublimit:

  • Request the full policy, including every endorsement and declarations page
  • Obtain the insurer’s engineering or industrial hygiene report in writing
  • Retain an independent moisture or mold assessor to evaluate causation
  • Keep dated invoices separating structural repair from remediation and testing
  • Preserve written communications, including claim-handling correspondence

💡 Pro Tip: Ask the adjuster in writing to identify the exact policy provision and sublimit relied upon. A vague denial is much harder to defend once specific language is demanded.

How Deductibles and Valuation Interact With the Sublimit

Your deductible generally applies before the mold cap is reached. A deductible is the amount you must absorb after a loss before the insurer’s payment obligation begins. Valuation matters too: replacement cost, actual cash value, and guaranteed replacement cost each produce different payouts, and replacement cost policies often pay actual cash value until repairs are completed. Consumer resources explaining homeowners insurance basics can help you place a sublimit in context. In many cases, homeowners recover less than expected because the deductible and mold cap both reduce payment on a single loss.

Frequently Asked Questions

1. Does every Houston homeowners policy include mold remediation insurance?

Not necessarily. Many Texas forms exclude remediation costs unless a mold endorsement was purchased, so the answer depends on your declarations page and attached endorsements.

2. Can I raise my mold coverage limit?

Generally yes, subject to underwriting and availability. TDI-approved endorsements permit homeowners to select higher amounts, and some forms allow coverage up to policy limits, though options vary by carrier.

3. My insurer paid the water damage but refused the remediation invoice. Is that allowed?

It may be, depending on wording. Common language covers ensuing mold from sudden and accidental discharge while separately limiting remediation and testing costs, so the distinction is often legitimate but also frequently applied too broadly.

4. Can an insurer refuse to renew because of an old mold claim in Houston?

Section 544.303 restricts underwriting decisions based on prior mold damage or claims when remediation was completed and documented as the statute requires. It does not apply to insurers excluded from the subchapter’s definition, such as surplus lines carriers, TWIA, and the FAIR Plan.

5. How long do I have to challenge a denial?

Deadlines depend on your policy’s suit limitation provision and applicable Texas statutes of limitations. Courts generally construe tolling exceptions narrowly. Prompt review by counsel is advisable rather than assuming an extension applies.

Protecting the Coverage You Actually Paid For

A mold remediation coverage limit in Texas is a regulated, negotiated sublimit that reflects how Texas law and Department of Insurance rulemaking reshaped the mold exposure carriers assume. Understanding your endorsement, the ensuing-loss language, and the causation evidence gives you a realistic view of what your policy should pay. Every claim turns on its own facts, policy wording, and documentation.

If a carrier has capped, delayed, or denied your remediation payment, a mold remediation coverage limit texas lawyer at Fitts Law Firm, PLLC can evaluate your claim. Call 713-871-1670 or reach out today to get started.
construction worker with tool belt inspecting residential brick home renovation framing

What Is Ordinance Or Law Coverage In A Houston Homeowners Policy?

Why Rebuilding to Current Code Can Cost More Than Your Policy Pays

Key Takeaways: Ordinance or law coverage is the portion of a Houston homeowners policy that pays the added expense of rebuilding a damaged home to current building codes, which standard dwelling coverage generally does not cover. It typically addresses three categories: the value of undamaged structure a city orders demolished, the demolition and debris removal cost for that portion, and the increased cost of code-compliant construction. In Texas, this protection usually arrives as an endorsement with a percentage sublimit, so its presence and limit depend entirely on the declarations page and attached forms. Houston-area homes face elevated exposure because Texas Insurance Code provisions tie windstorm insurability in the designated catastrophe area to code compliance, meaning a major post-storm repair can pull an older home into current standards. Denials commonly involve exhausted sublimits, "betterment" arguments, missing written code orders, or contested wind-versus-flood causation.

Ordinance or law coverage is the part of a Houston homeowners policy that helps pay the extra cost of rebuilding a damaged home to meet today’s building codes. Standard dwelling coverage generally pays to repair or replace what was there before the loss. It does not automatically pay for the upgraded wiring, elevated foundation, hurricane straps, or impact-rated windows a city inspector may now require. That gap is where many Houston claims stall after a hurricane, hailstorm, or fire.

If your carrier has refused to pay code-driven rebuilding costs, the attorneys at Fitts Law Firm, PLLC may be able to review your policy language and claim file. Call 713-871-1670 or contact us now to discuss what your policy may owe.

Houston Zoning Code booklet and building permit documents on wooden table

How Ordinance Or Law Coverage Texas Policies Actually Work

Ordinance or law coverage generally addresses three distinct categories of loss that standard dwelling limits do not reach. First, the value of the undamaged portion of a structure that a municipality orders demolished. Second, the actual cost of demolition and debris removal for that undamaged portion. Third, the increased cost of construction required to bring the rebuilt structure into compliance with current codes. Many Texas forms cap this coverage at a stated percentage of the dwelling limit, often far smaller than homeowners assume.

This coverage exists because code authority is independent of private agreements. The principle that a city’s rebuilding requirements apply independently of what a private insurer’s policy covers is a recognized concept in Texas insurance law. Your insurer’s obligation is defined by the policy, while the city’s rebuilding requirements are defined by the code in force at the time of permitting, and those two things frequently do not match.

Texas insurance regulation shapes how this endorsement reaches your policy. The Texas Department of Insurance oversees the market under the Texas Insurance Code, and insurers generally must file rates and policy forms with TDI. Since the 2003 move to a file-and-use system, Texas residential property insurers may largely use their own forms once filed and approved. Because of this layered framework, two Houston homeowners with similar homes can hold materially different code upgrade coverage.

The Endorsement Mechanism Under Texas Law

Texas law expressly contemplates that policy coverage may be added by endorsement. Chapter 2002 of the Texas Insurance Code governs standard forms for residential property policies, and building ordinance provisions are customarily delivered as endorsements rather than part of base coverage. The practical consequence is that presence, absence, and limit are determined by the declarations page and attached forms.

Reading the declarations page alongside every attached endorsement is the only reliable way to know whether code compliance coverage applies to your loss.

What a Standard Houston Home Insurance Policy Does and Does Not Cover

Understanding the baseline makes the code-upgrade gap easier to see. According to the Texas Department of Insurance home insurance guide, most home policies in Texas include six coverages: dwelling, other structures, personal property, liability, additional living expenses, and medical payments. Many cover damage from fire, wind and hail, theft, and sudden water damage, though wind and hail are excluded under some coastal policies and covered instead through TWIA.

Exclusions matter just as much as coverage grants. Texas policies commonly exclude flood damage, earthquake, and maintenance-related deterioration. For Houston homeowners, flood exclusions are particularly consequential given regional storm exposure, and disputes over whether damage came from wind or rising water remain common. For more on how carriers apply these provisions, see our discussion of policy exclusions in Houston claims.

Cost Category Typically Paid by Dwelling Coverage Typically Requires Ordinance or Law Coverage
Replacing damaged roof decking as-is Yes No
Adding code-required hurricane strapping Generally no Yes
Demolishing undamaged portions by city order Generally no Yes
Debris removal for code-ordered demolition Limited Often yes
Electrical or plumbing brought to current code Generally no Yes

💡 Pro Tip: Request a certified copy of your complete policy, including all endorsements, in writing at the start of a claim. Adjuster summaries are not the contract.

Why Houston-Area Homes Face Elevated Code Exposure

Coastal and near-coastal Texas construction is tied directly to building code compliance by statute. Texas Insurance Code Sec. 2210.258(a) provides that construction, alteration, remodeling, enlargement, and repair of structures in the designated catastrophe area must comply with applicable building code standards to be eligible for windstorm and hail insurance through TWIA. The Texas windstorm insurance statute also addresses certificates of compliance as a condition of TWIA insurability. These requirements govern TWIA eligibility specifically; they do not dictate what a private homeowners policy pays.

Older homes are not permanently insulated from these requirements. Texas Insurance Code Sec. 2210.251(e) addresses structures built before January 1, 1988 in areas not governed by a recognized building code, which may remain insurable without further inspection if the structure is in essentially the same condition and has undergone no structural change other than one made in accordance with code. In practice, a major post-storm repair can pull an otherwise exempt home into current standards. That is precisely when uncovered upgrade costs surface.

Common Ways Code Upgrade Claims Get Denied or Underpaid

Denials in this area tend to follow recognizable patterns. Homeowners researching a dispute frequently encounter one or more of the following:

  • The carrier pays repair costs but excludes the incremental cost of code-required upgrades, arguing the endorsement was never purchased.
  • The insurer applies a percentage sublimit that is exhausted long before the permitted rebuild is complete.
  • The adjuster characterizes required upgrades as betterment or improvement rather than a code obligation.
  • The carrier disputes that a local authority actually required the upgrade, absent a written correction notice or permit denial.
  • Causation is contested, with insurer-retained engineers attributing damage to wear, age, or an excluded peril.

Each of these positions is fact-dependent and may be contestable. Whether an insurer’s interpretation holds up depends on the specific endorsement language, the documented code requirement, and the evidence of causation. Texas courts construe policy language as written and, where a provision is genuinely ambiguous, may apply the rule favoring the insured’s reasonable construction.

Building the Record Before a Dispute Hardens

Documentation created early tends to carry more weight than reconstruction after the fact. Ask the permitting authority for written notice of any code requirement, keep the permit application and any correction notices, and photograph conditions before demolition. Independent estimates that separately line-item code-driven costs are far more persuasive than a lump sum figure.

Keep every communication in writing where possible. Texas policyholders benefit from clear timelines and a documented paper trail. Note that regulatory complaint processes are administrative and separate from any civil lawsuit for breach of contract or statutory violations, and filing one does not substitute for pursuing contractual remedies or preserve deadlines such as the policy’s suit-limitation provision.

Home insurance is not legally mandated in Texas, but it functions as a practical necessity. A lender will require it if you still owe money on your home. That lender requirement often drives homeowners to buy the minimum, which is one reason code upgrade coverage is so frequently missing or underlimited on Houston property insurance policies.

💡 Pro Tip: Review your endorsement schedule at each renewal. Code requirements change over time, and a limit that was adequate five years ago may not cover today’s rebuild standards.

Frequently Asked Questions

1. Is ordinance or law coverage automatically included in a Texas homeowners policy?

Generally, no. It is typically offered as an endorsement or a scheduled percentage of the dwelling limit. Check the declarations page and every attached form, because availability and limits vary by carrier and policy form.

2. Does this coverage apply if my city never issued a written order?

In many cases, insurers require documentation of the code requirement. Most forms are triggered by the enforcement of an ordinance or law, so a written correction notice, permit condition, or inspector determination generally strengthens the claim. Verbal statements from a contractor are usually insufficient standing alone.

3. Can an insurer deny code upgrade costs as "betterment"?

Carriers sometimes take that position, but it is not automatically correct. Whether a required upgrade constitutes betterment or a covered code obligation depends on the endorsement language and the applicable ordinance. This issue is frequently fact-sensitive.

4. What if my claim involves both flood and wind damage?

Concurrent causation disputes are common in the Houston area. Because flood is typically excluded from homeowners policies, allocation between covered and excluded perils often becomes the central dispute. Independent engineering evidence may be necessary to rebut an insurer’s causation report.

5. Does my percentage sublimit reset for each part of the rebuild?

Typically not, though the structure varies by policy form. Personal homeowners policy forms more commonly apply a single combined sublimit across demolition, debris removal, and increased construction cost, but endorsement forms vary, some commercial forms apply separate sublimits for demolition cost and increased cost of construction. Review the specific terms of your endorsement to understand how your sublimit applies.

Protecting Your Rebuild When the Code Bill Arrives

Ordinance or law coverage texas homeowners rely on exists because building codes and insurance contracts operate on separate tracks. Texas statutes governing insurance forms and local code authority reflect that local requirements apply regardless of what your policy pays. Reviewing your endorsements before a loss is far easier than litigating them after one, and every claim ultimately turns on its own facts, policy language, and evidence. This article is general information, not legal advice about any particular policy or claim.

If your carrier has denied, delayed, or underpaid code-driven rebuilding costs, Fitts Law Firm, PLLC handles denied insurance claims for Texas policyholders. Visit our firm website, call 713-871-1670, or request a case review to have your policy and claim file evaluated.

man standing on wooden deck outside brick home reviewing legal documents

Why Houston Homeowners Have Two Years to Contest a TWIA Denial

Understanding the Clock That Starts When TWIA Says No

Key Takeaways: Under Texas Insurance Code § 2301.010(b), a windstorm and hail policy issued in the catastrophe area generally cannot cut off suit before the earlier of two years from the insurer’s acceptance or rejection of the claim or three years from the date of loss. A denial typically starts a two-year countdown, separate from the one-year claim-filing rule in § 2210.205(a)(1), which may be extended up to 180 days on a showing of good cause. Harris County is a second tier coastal county in the seacoast territory, but TWIA coverage reaches only designated catastrophe areas. Policy language contrary to statutory minimums is void under § 2301.010(d), though § 2301.010(e) allows approved alternative provisions. Before filing suit, homeowners must satisfy Subchapter L-1 requirements, including notice of intent and, if requested, alternative dispute resolution.

A denial letter from the Texas Windstorm Insurance Association is not the end of your claim. Under Texas Insurance Code § 2301.010(b), a contractual limitations period in a windstorm and hail policy issued in the catastrophe area generally may not end before the earlier of two years from the date the insurer accepts or rejects the claim, or three years from the date of the loss. For most Houston homeowners in the catastrophe area, the denial starts a two-year countdown to file suit.

If your windstorm or hail claim was rejected and you are unsure how much time remains, the team at Fitts Law Firm, PLLC can review your denial letter and policy. Call 713-871-1670 or reach out to our Houston office to discuss your options before a deadline passes.

August calendar with Aug 20 2023 and 2025 circled beside legal document and clock

Why TWIA Operates Under Its Own Rulebook

TWIA is not an ordinary private carrier, and Texas law treats it differently. Chapter 2210 of the Texas Insurance Code governs the Association, and § 2210.001 describes it as a residual insurer of last resort for windstorm and hail insurance in the seacoast territory. Created by the Legislature in 1971 after hurricanes constricted the coastal market, TWIA provides wind and hail coverage to applicants who cannot obtain it privately.

That public origin explains why the dispute timeline is statutory rather than discretionary. TWIA operates under a Board of Directors appointed by the Commissioner of Insurance and follows a Plan of Operation and Texas Administrative Code provisions. The Association’s governing laws point policyholders to Chapter 2210 as the primary source of claim and dispute rules.

Statutory applicability provisions reinforce the separation. Section 2301.003(a)(1) makes Subchapter A of Chapter 2301 applicable to insurers "other than the Texas Windstorm Insurance Association," while Chapter 2210 separately dictates TWIA’s requirements. A Houston homeowner cannot assume advice about standard private carriers applies to a TWIA file, and deadlines should be confirmed against the policy form and Chapter 2210 itself.

Why Houston Falls Inside TWIA’s Territory

Harris County is statutorily part of the seacoast territory. Section 2210.003(11) lists Harris County as a "second tier coastal county," and § 2210.003(10) defines the seacoast territory as first and second tier coastal counties. However, under § 2210.003(3), a "catastrophe area" means a municipality, a part of a municipality, a county, or a part of a county designated by the commissioner under § 2210.005. The first tier counties are fully included because the commissioner has designated them, while only specific portions of Harris County east of Highway 146 have been designated, so only those designated portions of Harris County qualify for TWIA coverage. Eligibility also depends on windstorm certification and policy terms.

Coverage territory matters because it determines which limitations rule applies. Section 2301.010 applies to insurers issuing windstorm and hail insurance in the catastrophe area, so protections depend on property location and carrier. Homeowners with multiple policies may face different deadlines on each.

The TWIA Claim Denial Dispute Deadline in Plain Terms

Two different clocks control a TWIA dispute. The first is the claim-filing deadline. Under § 2210.205(a)(1), a TWIA policy must require the insured to file a claim no later than the first anniversary of the date the property damage occurs. The second is the deadline to bring suit, addressed by § 2301.010(b) for catastrophe-area windstorm policies and shaped by Subchapter L-1 procedures.

Deadline Governing Statute What Triggers It
One year to file the claim Tex. Ins. Code § 2210.205(a)(1) Date the property damage occurs
Possible 180-day extension Tex. Ins. Code § 2210.205(b) Commissioner’s finding of good cause
Two years to file suit Tex. Ins. Code § 2301.010(b) Insurer’s acceptance or rejection of the claim
Three-year outer limit Tex. Ins. Code § 2301.010(b) Date of the loss

The one-year filing rule is not entirely rigid, but relief is discretionary. Section 2210.205(b) permits an extension of up to 180 days on a showing of good cause. Relief is not automatic and should never be assumed.

What "Accepts or Rejects" Usually Means

The two-year window is generally triggered by the insurer’s decision on the claim. A formal TWIA denial most often starts the countdown for a windstorm claim lawsuit. Where the Association issues a partial payment, supplemental decision, or revised position, the triggering date becomes fact-dependent, and courts may examine correspondence to determine when a decision occurred.

Provisions That Try to Shorten the Window

Texas law places a floor under this protection. Section 2301.010(d) provides that a contractual provision contrary to Subsection (b) is void, and severable provisions remain in effect. Section 2301.010(e) permits the department to approve alternative provisions consistent with sound underwriting principles. If your declarations page recites a shorter suit deadline, that language does not necessarily control.

Written Notice of Your Deadline

Insurers using these provisions are required to tell you the applicable period in writing. Under § 2301.010(f), an insurer must disclose the contractual limitations or claims filing period when the policy is issued or renewed. Such notice is typically informational and not part of the contract. Review the full text of the Texas windstorm limitations statute to see how subsections fit together.

The Steps You May Have to Take Before Filing Suit

Contesting a TWIA denial is not simply a matter of walking into the courthouse. Section 2210.205(a)(2) requires TWIA policies to carry conspicuous notice describing processes and deadlines for appraisal under § 2210.574, alternative dispute resolution under § 2210.575, and compliance with Subchapter L-1 requirements. Subchapter L-1 requires claimants to give the Association notice of intent to bring an action, and § 2210.575(f) directs courts to abate a filed suit until notice is given and, if requested, the dispute has gone through alternative dispute resolution.

Practical steps that often matter include:

  • Preserving the denial letter, adjuster reports, and all correspondence
  • Photographing and documenting damage before repairs, when safely possible
  • Obtaining independent engineering or contractor opinions to rebut insurer-retained reports
  • Calendaring both the one-year filing date and the projected suit deadline
  • Confirming in writing what the Association considers its final decision

💡 Pro Tip: Ask TWIA in writing to identify the date it accepted or rejected your claim. A written answer can remove later ambiguity about when your two-year period began.

How Prompt Payment Rules Fit Into the Picture

Chapter 542 of the Texas Insurance Code sets separate timing obligations on insurers handling first-party claims. Subchapter B establishes deadlines to acknowledge, investigate, accept, reject, and pay claims, which shapes how and when a denial is formally issued. These prompt-pay provisions are distinct from limitations rules and address insurer conduct rather than your filing deadline.

Application to TWIA is limited. Chapter 2210 restricts the causes of action and damages available against the Association, so whether prompt-payment remedies reach a particular TWIA file depends on the facts and statutory carve-outs.

Common Traps for Houston Policyholders

Most missed deadlines trace back to avoidable errors. Homeowners frequently assume the clock runs from the storm date alone, or wait for contractor estimates before reporting damage. Others treat an adjuster’s informal statement as a denial, or negotiate for months without calendaring anything.

Ambiguity about the triggering event is the most litigated issue. If weighing whether timing supports a claim, understand when Houston homeowners can sue after a rejection. Outcomes depend on specific facts, policy language, and procedural history.

💡 Pro Tip: If repairs are urgent, document the pre-repair condition thoroughly and keep every invoice. Repairs should not be delayed for safety reasons, but undocumented repairs can complicate proof of causation later.

Frequently Asked Questions

1. Does the two-year period start on the date of the hurricane?

Generally, no. Section 2301.010(b) ties the two-year period to the date the insurer accepts or rejects the claim, with a separate outer limit from the loss date.

2. What happens if I missed the one-year claim-filing deadline?

Section 2210.205(b) allows extension of up to 180 days on a showing of good cause. Relief is discretionary, not automatic, so acting quickly and documenting delay reasons matters.

3. Do I have to go through appraisal before suing TWIA?

TWIA policies must give conspicuous notice of appraisal and ADR processes, along with Subchapter L-1 requirements. A suit filed before notice of intent or requested ADR completion is subject to abatement. Whether appraisal applies depends on the policy and dispute nature, since appraisal typically addresses loss amount rather than coverage.

4. Can my policy give me less than two years to sue?

Under § 2301.010(d), a provision contrary to the statutory minimum is void, and remaining severable terms stay in effect, though § 2301.010(e) allows approved alternative provisions. A court would interpret the specific language.

5. Where can I read the governing statute myself?

The full text of Chapter 2210 windstorm statutes is publicly available and sets out TWIA’s structure, claim requirements, and dispute procedures.

A Texas windstorm denial does not extinguish your claim, but it starts a limited period to act. Between the one-year claim-filing rule in § 2210.205(a)(1), the possible 180-day extension in § 2210.205(b), the Subchapter L-1 pre-suit steps, and the suit-filing protection in § 2301.010(b) for catastrophe-area windstorm policies, the timing framework rewards homeowners who move deliberately and keep thorough records. Because these rules interact with policy language and specific facts, a careful file review is usually the first step.

If TWIA has rejected or underpaid your storm damage claim, the attorneys at Fitts Law Firm, PLLC handle TWIA claim denial dispute deadline lawyer matters for policyholders across the Texas coast. Call 713-871-1670 or schedule a case review today so your deadlines are identified before they expire.

Home Insurance Policy document and house keys resting on brick wall outdoors

What Is the HO-145 Cosmetic Damage Exclusion in Houston Home Policies?

When a Hail-Damaged Roof Looks Fine to Your Insurer: The Texas Cosmetic Damage Endorsement Explained

Key Takeaways: The HO-145 is a Texas Department of Insurance prescribed endorsement titled "Exclusion of Cosmetic Damage to Roof Coverings Caused by Hail," allowing carriers to decline payment for hail damage that changes appearance without impairing water-shedding ability. Not all Houston policies include it, and many carriers use company-filed forms with similar language. The exclusion is narrow: it reaches appearance-only marring rather than damage affecting performance. Disputes turn on competing expert evidence about mat fracture, granule loss, and shortened service life, making independent inspections and documentation critical. Prompt payment deadlines under Chapter 542 apply even when carriers intend to deny, and separate valuation rules under Chapter 2210 govern Texas Windstorm Insurance Association policies.

If a Houston adjuster told you your dented roof is "only cosmetic," your policy may include an HO-145 endorsement or comparable company-filed exclusion. The HO-145, formally titled "Exclusion of Cosmetic Damage to Roof Coverings Caused by Hail," is a Texas Department of Insurance prescribed form for Texas Homeowners Forms (HO-A, HO-B, and HO-C). It allows carriers to decline payment for hail damage that alters roof appearance without impairing water-shedding ability. That single endorsement can turn a full roof replacement into a denial letter.

If your roof claim was denied or underpaid based on a cosmetic damage endorsement, the team at Fitts Law Firm, PLLC can review your policy language and the adjuster’s findings. Call 713-871-1670 or contact us now to discuss your options.

man holding clipboard and pen inspecting residential property interior wall

How the HO-145 Cosmetic Damage Exclusion Texas Homeowners Face Actually Works

The endorsement operates as a carve-out from otherwise covered wind and hail perils. Because the HO-145 is state-prescribed, its language is consistent wherever used. Since Texas insurers gained the ability to file their own forms, many companies write cosmetic damage exclusions with their own wording, so the controlling text is always the endorsement attached to your policy.

The endorsement is not universal. Homeowners insurance policies in Texas vary considerably. Some Houston policies contain the endorsement, some do not, and some added it at renewal. Reviewing your declarations page for a listed HO-145 form number, or similarly titled company form, is the fastest first step.

"Cosmetic" is a defined limitation, not a general aesthetic judgment. The exclusion targets appearance-only marring. As typically worded, it does not reach damage that shortens the roof’s service life, breaches the water barrier, or compromises system function, though the precise scope depends on the endorsement’s definitions. That distinction is where most disputes arise.

What Counts as a "Roof Covering" Under Texas Law

Texas statutory law defines the term more broadly than many adjusters apply. Under Texas Insurance Code § 2210.207(a), which governs Texas Windstorm Insurance Association policies, "roof covering" means the roofing material exposed to the weather, the underlayments applied for moisture protection, and all flashings required in replacement. That definition does not automatically control private carrier policies, but it illustrates that damage to underlayment or flashing is rarely "cosmetic."

An inspection that stops at surface granule loss may overlook:

  • Fractured shingle mats exposing underlayment
  • Displaced, split, or punctured flashings
  • Compromised sealant strips allowing uplift
  • Damage to vents, ridge caps, and other roof components

Cosmetic vs Functional Damage: The Line Insurers Draw

Functional damage impairs performance; cosmetic damage allegedly does not. Carriers and their engineers frequently classify hail strikes as cosmetic when a policyholder’s consultant would call them functional. Neither label is self-proving. Classification often comes down to competing expert opinion about mat fracture, granule displacement, and expected service life.

Commonly Labeled "Cosmetic" Commonly Argued "Functional"
Dents on metal roofing panels or vents Fractured shingle mat exposing underlayment
Granule scuffing without mat exposure Split or displaced flashing at penetrations
Discoloration or marring of surfaces Broken seal bonds permitting wind uplift
Minor surface indentation Damage shortening documented service life

Documentation is what moves a claim across that line. Dated photographs, a written roofing report identifying test squares, moisture readings, and manufacturer guidance on impact damage all carry weight. A short email from an adjuster stating "cosmetic only," with no supporting measurements, is a conclusion rather than evidence. Understanding what a policy exclusion is and how carriers apply it helps homeowners recognize when a denial rests on assumption rather than proof.

Replacement Cost, Actual Cash Value, and Why the Payout Shrinks

How your policy values the loss can matter as much as whether coverage applies. Many policies pay to repair or rebuild based on current costs, while others pay less through depreciation, and some apply actual cash value specifically to the roof. A cosmetic endorsement stacked on an actual cash value roof settlement can leave a Houston homeowner with a fraction of replacement cost.

Texas law addresses this valuation question directly in the windstorm context. For TWIA policies, Texas Insurance Code § 2210.207(c)-(d) provides that for qualifying dwellings insured at 80 percent or more of full replacement cost, coverage extends to full cost of repair or replacement without depreciation deduction; otherwise, liability is generally limited to replacement cost less depreciation. Section 2210.207(e) permits the Commissioner to adopt rules authorizing actual cash value coverage on roofs and to establish conditions, premium reductions, and disclosure.

💡 Pro Tip: Request a complete certified copy of your policy, including every endorsement and declarations page, in writing. Carriers generally provide it on request, and the endorsement list often reveals limitations the adjuster never mentioned.

Prompt Payment Deadlines Still Apply to Disputed Claims

An exclusion argument does not suspend a carrier’s statutory obligations. Chapter 542 of the Texas Insurance Code, Subchapter B, sets deadlines for acknowledging notice of a claim, requesting information, accepting or rejecting a claim, and paying it (§§ 542.055, 542.056, 542.057, and 542.058). Those obligations run even when the carrier intends to deny based on a cosmetic damage endorsement.

Violations carry statutory consequences. Texas Insurance Code § 542.060 provides that an insurer violating the subchapter may be liable for the claim amount plus statutory interest and reasonable attorney’s fees. Under § 542.060(a), the default penalty interest rate for most first-party property claims is 18 percent per year. For first-party property claims subject to Chapter 542A, generally weather- or forces-of-nature-related claims filed on or after September 1, 2017, the rate is instead five percent above the judgment interest rate established under Finance Code § 304.003, a floating rate that can effectively reach up to approximately 20 percent. Residential property claims are subject to additional procedural requirements under Chapter 542A, including presuit notice.

Roof Condition, Inspections, and Insurability in the Houston Area

Roof condition affects more than a single claim. After a hail loss, some homeowners find carriers reluctant to write or renew coverage. The Texas Department of Insurance describes alternatives including the Voluntary Inspection Program certificate of insurability and the Texas FAIR Plan Association, which offers policies to those unable to obtain coverage through regular companies.

Age and condition can also affect windstorm eligibility. Texas Insurance Code § 2210.251(e) provides that a structure built or altered before January 1, 1988 in an area not governed by a recognized building code may be eligible for TWIA coverage without meeting inspection requirements if it was insured for those perils within the prior 12 months and remains in essentially the same condition apart from normal wear and tear.

Practical Steps After a Roof Claim Denial in Houston

Move deliberately and keep everything in writing. A denial premised on a roof cosmetic exclusion is a position, not a final judgment.

  • Obtain the full denial letter and specific endorsement form cited
  • Commission an independent roofing or engineering inspection before repairs
  • Preserve damaged materials and photograph test squares
  • Log every call, adjuster name, and date
  • Confirm your policy’s suit limitation and appraisal provisions

Repair disputes can compound insurance disputes. The Residential Construction Liability Act governs certain claims against contractors, and under Texas Property Code § 27.004(q), its limitations on damages do not apply where a contractor fails to follow through on an accepted settlement or repair offer. Houston homeowners caught between a limited claim payment and a stalled contractor should document both tracks separately.

💡 Pro Tip: If an impact resistant roof endorsement or premium discount appears on your declarations page, flag it. A carrier that priced coverage around roof performance may face questions when it later characterizes hail strikes as purely cosmetic.

Frequently Asked Questions

1. How do I know whether my Houston home insurance policy contains the HO-145?

Check the declarations page for attached endorsement form numbers. If HO-145 or a similarly titled company form appears, request the full endorsement text. Not every Texas policy includes one.

2. Does the endorsement exclude all hail damage to my roof?

Generally, no. The endorsement is directed at appearance-only damage to roof coverings. Damage that impairs the roof’s ability to perform, including harm to underlayment or flashing, is typically outside the exclusion.

3. Can I challenge an engineer’s report that calls my damage cosmetic?

Yes. Policyholders commonly retain independent inspectors to rebut carrier reports. Courts may consider competing expert testimony on mat fracture, service life, and causation when classification is disputed.

4. Does a denial stop the prompt payment clock?

No. The deadlines in Chapter 542, Subchapter B apply to claim handling, and a rejection notice must still comply with the statute’s timing requirements.

5. What deadline applies to a lawsuit over a denied roof claim?

Limitations periods depend on the claim asserted, generally four years for breach of contract and two years for statutory claims. Policies may set a shorter suit provision within the limits Texas law allows. Confirming deadlines early is important.

Where Houston Homeowners Stand After a Cosmetic Damage Denial

The HO-145 cosmetic damage exclusion Texas carriers rely on is narrower than most denial letters suggest. It targets appearance, not performance, and underlayment and flashing rarely suffer purely cosmetic harm. Between valuation rules, prompt payment obligations under Chapter 542, and the evidentiary weight of independent inspection, a Houston insurance claim denial based on this endorsement is often worth a closer look.

If a carrier has denied or reduced your hail damage roof claim in Houston, Fitts Law Firm, PLLC is prepared to review the policy and the file. Speak with a ho-145 cosmetic damage exclusion texas lawyer by calling 713-871-1670 or reaching out through our contact page today.

man examining insurance check and envelope standing outside brick home

Can Houston Homeowners Demand Appraisal After an Underpaid Home Claim?

Understanding Your Right to Appraisal in Houston Home Insurance Disputes

Key Takeaways: Yes, Houston homeowners can demand appraisal after an underpaid home claim. Texas law gives policyholders the right to challenge the amount an insurer proposes to pay when coverage is accepted but the dollar amount is disputed, not when coverage is denied outright. Under new legislation, Texas residential policies issued or renewed on or after January 1, 2026 must include an appraisal provision with conspicuous notice of deadlines and binding effect of any award. The process follows strict deadlines, including a 60-day window to demand appraisal in the TWIA context and a four-year statute of limitations for breach-of-contract lawsuits. Homeowners retain remedies beyond appraisal, such as bad-faith and Chapter 541 claims. Acting quickly and identifying whether your dispute is about amount or coverage is essential.

Yes, Houston homeowners can generally demand appraisal after an underpaid home claim, and Texas law now makes that right clearer than ever. When your insurer accepts your claim but offers less than your loss is worth, appraisal provides a structured way to challenge that figure. This tool addresses disagreements over dollars, not whether coverage exists.

If your storm, hail, wind, or roof claim came back lower than expected, you do not have to accept the insurer’s number without a fight. Fitts Law Firm, PLLC helps policyholders across the region push back on lowball offers. Reach the firm through its main office website, by calling 713-871-1670, or by using the firm’s online case review form.

Texas Homeowner's Policy document, appraisal demand letter, and Houston Texas map on wooden table

When an Underpaid Claim Triggers the Appraisal Process

Appraisal applies when an insurer has accepted coverage but disputes the payment amount. Under the Texas Windstorm Insurance Association framework, appraisal applies when the association has accepted coverage for a claim, in full or in part, and the claimant disputes the amount of loss the association will pay. Appraisal resolves the "how much" question, not the "is it covered" question.

The scope of appraisal is intentionally narrow. Texas statute confirms the provision is intended to provide dispute resolution solely to determine the amount of loss when that amount is disputed between the policyholder and insurer. If your dispute concerns causation or a full denial, appraisal alone may not resolve it.

💡 Pro Tip: Before demanding appraisal, read your insurer’s decision letter closely. If it accepts the claim but pays too little, appraisal likely fits. If it denies coverage outright, you may need a different legal strategy.

Appraisal Is a Required Policy Provision in Texas

Texas now requires residential property insurance policies to include an appraisal provision. This applies to personal residential property policies delivered, issued for delivery, or renewed in Texas on or after January 1, 2026. Under Tex. Ins. Code Sec. 1813.003(a), an insurance policy described by Section 1813.001(a) must contain an appraisal provision that complies with this chapter. This chapter applies to personal automobile and residential property policies but does not reach commercial policies or the Texas Windstorm Insurance Association, which follows its own appraisal regime. You can review the full text through the Texas appraisal clause statute.

Policies must also provide conspicuous notice of these rights. In the TWIA context, Texas requires policies to contain conspicuous notice about dispute resolution, including processes and deadlines for appraisal under Section 2210.574 and the binding effect of appraisal. An appraisal outcome may bind both parties as to loss amount, subject to limited exceptions such as fraud or material mistake.

How the Texas Appraisal Framework Works

Once you demand appraisal, the process follows a defined, deadline-driven sequence. The steps below reflect the Texas Windstorm Insurance Association rules for TWIA policyholders; standard residential policies follow deadlines set under Chapter 1813. After a homeowner demands appraisal, the insurer must acknowledge the demand in writing not later than the 10th day after receipt, and both parties must each hire an independent, qualified appraiser.

The appraisers then work toward a valuation within bounded timelines. Appraisers must disclose fees and agree on an umpire within 15 days, and for residential claims agree on the loss amount within 90 days of the date by which both appraisers were named. This overview of the Houston home insurance appraisal process breaks down each step.

The insurer carries an affirmative duty to explain your options in writing. The association must include an explanation of the appraisal process and the process for requesting a supplemental payment with each acceptance/replacement-cost notice. You can read the current text in the published version of the Texas appraisal administrative rule.

💡 Pro Tip: Keep every letter, email, and estimate from your insurer in a dated folder. A clear paper trail often makes the difference when an appraisal or lawsuit turns on who said what and when.

These rules reflect current, recently updated Texas law. The Texas Windstorm Insurance Association appraisal rule reflects Texas legislation requiring a defined time period for completing appraisals, adopted by the Texas Department of Insurance to implement House Bill 3310, 88th Legislature, 2023, effective January 22, 2024. The broader appraisal requirement for personal residential and auto policies was added by Acts 2025, 89th Leg., R.S., Ch. 899 (S.B. 458), Sec. 1, creating Insurance Code Chapter 1813, which applies to policies issued or renewed on or after January 1, 2026.

Deadlines Every Houston Homeowner Should Track

Timing controls almost everything in an underpaid home insurance claim dispute. Under the TWIA framework, if a claimant disputes the loss amount the association will pay, the claimant may demand appraisal not later than the 60th day after receiving the notice. Deadlines to demand appraisal differ for standard residential policies under Chapter 1813, so always check your policy, but the practical takeaway is the same: act quickly.

A separate and longer clock governs lawsuits based on your policy. Texas applies a four-year statute of limitations to lawsuits based on contractual obligations under Texas Civil Practice and Remedies Code Sec. 16.051.

Letting a deadline pass generally forecloses your day in court. If a lawsuit is not filed during the statute of limitations period, a claimant will likely be unable to pursue the claim in court. Courts interpret tolling and discovery-rule exceptions narrowly, so no homeowner should assume a deadline will be extended.

Here are key deadlines Houston homeowners commonly encounter:

Action General Deadline Governing Authority
Demand appraisal after loss notice 60 days (TWIA context) Tex. Ins. Code Sec. 2210.574(b)
Insurer acknowledges appraisal demand 10 days 28 Tex. Admin. Code § 5.4211(c)
Appraisers agree on umpire 15 days 28 Tex. Admin. Code § 5.4211(e)
Agree on residential loss amount 90 days 28 Tex. Admin. Code § 5.4211(f)
File breach-of-contract lawsuit 4 years Tex. Civ. Prac. & Rem. Code Sec. 16.051

💡 Pro Tip: Calendar your deadlines the moment you receive any insurer notice. Timelines can run from the date you receive a letter, not the date you read it.

Why a Houston Appraisal Disputes Lawyer Can Help

A knowledgeable appraisal disputes lawyer can help you invoke the process correctly and protect other remedies. Appraisal is powerful, but it is not always the complete answer. Under Texas law, an appraisal award resolves only the loss amount, but the prompt payment of an appraisal award generally bars a policyholder from pursuing Chapter 541 of the Texas Insurance Code and common-law bad-faith claims, unless the policyholder can demonstrate an independent injury beyond the lost policy benefits. Chapter 542 (Prompt Payment of Claims Act) claims, however, may still be pursued after payment of an appraisal award. An attorney can help you decide whether appraisal, litigation, or both best fit your facts.

Some property-damage disputes also carry pre-suit notice rules that are easy to overlook. When a claim overlaps with construction or repair work, a claimant seeking construction-defect damages must give the contractor written notice by certified mail specifying the construction defects before the 60th day preceding initiating an action under Tex. Prop. Code Sec. 27.004(a).

Working with counsel that focuses on policyholder recovery keeps the pressure where it belongs. A firm experienced in handling homeowners insurance dispute Texas matters can gather independent estimates, rebut insurer engineering reports, and document bad-faith conduct. If your carrier issued a denied insurance claim Houston homeowners recognize as unfair, learning about your options for denied home insurance claim representation is a practical first step.

💡 Pro Tip: If an insurer pressures you into appraisal to avoid a coverage fight, pause and get guidance. Pushing appraisal on what is really a causation dispute can work against you.

Frequently Asked Questions

  1. Can I demand appraisal if my whole claim was denied?

Appraisal generally applies when coverage is accepted but the payment amount is disputed. The process is intended solely to determine the loss amount when that amount is disputed. A full denial usually raises coverage questions that appraisal alone may not resolve.

  1. How long do I have to demand appraisal in Houston?

Deadlines can be short and vary by policy and program. In the TWIA context, a claimant may demand appraisal not later than the 60th day after receiving notice. Deadlines differ for standard residential policies, so confirm the specific deadline in your policy.

  1. Is an appraisal decision binding on me?

It can be. Texas requires policies to disclose the binding effect of appraisal under Section 2210.574. An appraisal award may bind both sides as to loss amount, subject to limited exceptions such as fraud or material mistake.

  1. Does appraisal replace my right to sue?

Not necessarily. An appraisal award generally resolves only valuation. While prompt payment of an appraisal award typically bars Chapter 541 and common-law bad-faith claims absent an independent injury beyond lost policy benefits, Chapter 542 (Prompt Payment of Claims Act) claims may still be available.

  1. What is the deadline to file a lawsuit over an underpaid claim?

A four-year contract deadline generally applies. Texas applies a four-year statute of limitations to lawsuits based on contractual obligations. Waiting too long can bar your claim entirely.

Protecting Your Home Claim Before Time Runs Out

Houston homeowners facing an underpaid claim have real, statute-backed tools, and appraisal is often the fastest path to a fair number. Texas law now requires appraisal provisions in residential policies issued or renewed on or after January 1, 2026, sets firm deadlines for each step, and preserves your ability to pursue bad-faith and breach-of-contract remedies when appropriate. The key is acting within the applicable windows and understanding which process fits your specific dispute.

If your insurer underpaid your storm, hail, wind, or roof claim, do not wait for a deadline to close your options. Reach out to Fitts Law Firm, PLLC through the firm’s homepage, call 713-871-1670, or submit the confidential contact form to have your underpaid home insurance claim reviewed today.