Homeowner reading letter and envelope in front of partially repaired roof

Does a Reservation of Rights Letter Mean Your Home Claim Will Be Denied?

How Texas Homeowners Should Read a Reservation of Rights Letter

Key Takeaways: A reservation of rights letter does not mean your home claim has been denied. Under Texas law, it generally means your insurer is still deciding whether the policy covers the loss and wants to keep its coverage defenses while it investigates. Texas Insurance Code § 541.060 still requires a reasonable investigation and a good-faith, prompt, fair settlement effort once liability is reasonably clear. It also bars the insurer from enforcing a full release after only a partial payment, unless the payment settles a doubtful or disputed claim, and it requires a prompt, reasonable explanation for any denial. Keep detailed records, answer information requests promptly, and track deadlines, including the two-year limitations period under § 541.162 and any presuit notice or policy deadlines. Talking with an insurance lawyer early can help you avoid costly mistakes such as signing broad releases or missing deadlines.

A reservation of rights letter does not mean your home claim has been denied. Under Texas law, it generally means your insurer has not finished deciding whether the policy covers your loss and wants to keep its options open while it investigates. It is a warning sign worth taking seriously, but it is not a final decision, and Texas homeowners have specific legal protections while the insurer decides.

If your insurer has sent you a reservation of rights letter after a storm, roof failure, or other property loss, Fitts Law Firm, PLLC can review your policy and the insurer’s stated reasons with you. Call 713-871-1670 or contact us now to talk about your claim status and next steps.
Reservation of Rights letter beside insurance policy book, glasses, and claims adjuster business card

What a Reservation of Rights Letter Insurance Notice Actually Means

A reservation of rights letter insurance notice generally tells you the insurer is still evaluating coverage. Under Texas Insurance Code § 541.060(a)(4)(A)-(B), an insurer commits an unfair settlement practice if it fails, within a reasonable time, to affirm or deny coverage or submit a reservation of rights to the policyholder. The statute lists a reservation of rights as an acceptable response, so the letter is a recognized step in claim handling, not a denial.

Courts generally treat a reservation of rights as separate from a denial of coverage. The letter tells you the insurer may contest coverage later, usually by pointing to specific policy provisions such as exclusions, conditions, or limits. Your claim generally stays open. For a closer look, see our overview of reservation of rights letters in Houston.

Why Insurers Send These Letters

Insurers usually send these letters to protect defenses they may want to raise later. If an insurer keeps handling a claim without reserving its rights, a policyholder may argue it waived certain defenses. Texas courts, however, generally hold that waiver and estoppel cannot create coverage the policy does not provide, outside limited circumstances. Common triggers include questions about:

  • Whether wind, hail, or water caused the damage, or whether wear and tear did
  • When the damage happened and whether the policy was in force
  • Whether the loss was reported promptly under the policy’s notice terms
  • Whether an exclusion, such as flood or mold, might apply

When the Letter Usually Arrives

A reservation of rights letter often shows up early in the investigation. Under Texas Insurance Code § 542.055(a), an insurer generally must do three things within 15 days of receiving notice of a claim: acknowledge the claim, begin any investigation, and request the items, statements, and forms it reasonably believes it will need. Eligible surplus lines insurers get 30 business days. Many homeowners receive a reservation of rights during this window or soon after.

Texas Disclosure Rules for Residential Property Claims

Homeowners sometimes see references to a separate Texas statute on reservation of rights disclosures, but that citation does not apply to home claims. Texas Insurance Code § 1467.101 is part of Chapter 1467, which governs dispute resolution for out-of-network health benefit claims. Texas law does not prescribe a specific form for reservation of rights letters on residential property claims. The letter is generally expected to be timely and to identify the coverage issues the insurer is reserving.

For Houston homeowners, the letter should tell you what the insurer is questioning. If yours is vague, you can ask for clarification in writing.

Your Rights While the Insurer Investigates

Texas law limits how an insurer may behave while reviewing coverage. A reservation of rights generally does not give the insurer unlimited time or discretion. Several provisions of the Texas Unfair Claim Settlement Practices statute may apply when a claim sits in limbo, and Chapter 542 sets deadlines for accepting, rejecting, and paying claims.

Investigation and Settlement Obligations

Texas Insurance Code § 541.060(a)(1), (a)(2)(A), and (a)(7) set three limits on insurers. An insurer may not misrepresent a material fact or policy provision relating to coverage. It may not fail to attempt in good faith a prompt, fair, and equitable settlement once liability has become reasonably clear. And it may not refuse to pay a claim without a reasonable investigation. A good-faith coverage dispute alone generally does not establish a violation, and courts look at the specific facts.

The insurer may also send follow-up requests for information. Texas Insurance Code § 542.055(b) allows additional requests if the investigation makes them reasonably necessary. Answer them promptly and keep copies of everything you send.

💡 Pro Tip: Every time you send documents to your insurer, send a short cover email listing exactly what is attached and the date. That gives you a clear record if the insurer later says it never received something.

Partial Payments and Release Demands

Be careful if a partial payment arrives while your claim is under a reservation of rights. Texas Insurance Code § 541.060(a)(6) makes it an unfair practice for an insurer to try to enforce a full and final release when it has paid only part of the claim, unless the payment is a compromise settlement of a doubtful or disputed claim. Read any document that comes with a check before you sign it.

What Happens If the Insurer Eventually Denies the Claim

If the insurer denies the claim, Texas law requires it to explain why. Under Texas Insurance Code § 541.060(a)(3), an insurer must promptly give a reasonable explanation of the basis in the policy, in relation to the facts or applicable law, for denying a claim or offering a compromise settlement.

A policyholder who suffers actual damages from an unfair practice may be able to sue the insurer directly. Texas Insurance Code § 541.151 allows a person who sustains actual damages to bring an action for damages caused by an unfair or deceptive act, including those under § 541.060. For many weather-related residential property claims, Chapter 542A requires written presuit notice at least 61 days before filing suit. Whether you have a viable claim depends on your damages, your policy, and the insurer’s conduct.

Insurer Action What It Generally Means Relevant Texas Law
Acknowledges claim Investigation has begun Tex. Ins. Code § 542.055(a)
Sends reservation of rights Coverage still under review Tex. Ins. Code § 541.060(a)(4)(B)
Requests more documents Further investigation needed Tex. Ins. Code § 542.055(b)
Denies claim Must give a prompt, reasonable explanation Tex. Ins. Code § 541.060(a)(3)

Deadlines Texas Homeowners Cannot Ignore

A lawsuit under Chapter 541 generally must be filed within two years. Under Texas Insurance Code § 541.162(a), the two years run from the date the unfair act occurred, or if later, from the date the homeowner discovered it or should have with reasonable diligence. Under § 541.162(b), the court must extend this deadline by 180 days if the homeowner proves the late filing was caused by the insurer knowingly engaging in conduct meant solely to make the homeowner delay filing suit.

These exceptions do not apply automatically, and courts often read them narrowly. Breach of contract claims follow different timing rules. Texas generally allows four years, but a policy may shorten that period to no less than two years, and many homeowners policies do. Your policy may also have its own notice and proof of loss deadlines, and Chapter 542A presuit notice rules may apply. Track dates from the moment the letter arrives.

💡 Pro Tip: Keep a simple claim log with the date of the loss, the date you reported it, the date of the reservation of rights letter, and the date of every call or email with the adjuster.

Practical Steps After Receiving the Letter

Your best response is careful documentation and a clear understanding of what the insurer is questioning. Read the letter closely and identify every policy provision it cites. Compare those provisions with your full policy, including endorsements. If the insurer relies on its own engineer or adjuster to argue the damage came from something other than the storm, an independent inspection may give you evidence to respond. Your policy may also include an appraisal clause for disputes over the amount of the loss.

Talking with a reservation of rights letter insurance lawyer early can help you avoid mistakes. Common ones include signing broad releases, giving recorded statements without preparation, and missing deadlines while waiting for a decision.

Frequently Asked Questions

1. Does a reservation of rights letter mean my home claim is denied?

Generally, no. Texas Insurance Code § 541.060(a)(4) treats a reservation of rights as separate from affirming or denying coverage. It generally means the insurer is still investigating and wants to keep the right to raise coverage defenses later.

2. Can my insurer take as long as it wants after sending the letter?

No. Section 541.060(a)(4) requires the insurer to affirm or deny coverage, or reserve its rights, within a reasonable time. Sections 541.060(a)(2)(A) and (a)(7) prohibit failing to attempt a prompt, fair settlement once liability is reasonably clear and refusing to pay without a reasonable investigation. Chapter 542 also sets deadlines.

3. Should I cash a partial payment check during a reservation of rights?

Read any accompanying documents first. Under Texas Insurance Code § 541.060(a)(6), an insurer cannot try to enforce a full and final release for a partial payment unless the payment is a compromise settlement of a doubtful or disputed claim.

4. What if the insurer denies my claim without explaining why?

Texas Insurance Code § 541.060(a)(3) requires a prompt, reasonable explanation of the basis in the policy. If you suffered actual damages, § 541.151 may allow you to sue, though presuit notice requirements may apply first.

Chapter 541 claims generally must be filed within two years under Texas Insurance Code § 541.162, subject to a discovery rule and a 180-day extension in limited cases. Breach of contract claims and policy deadlines may follow different timing rules.

Protecting Your Houston Home Claim Moving Forward

A reservation of rights letter generally means your insurer is still deciding, not that your claim is lost. Texas law requires insurers to investigate reasonably, explain any denial, avoid improper release demands, and attempt in good faith to settle claims once liability is reasonably clear. Organized records, prompt answers to proper requests, and close attention to deadlines can strengthen your position.

If you are dealing with a reservation of rights letter or a home claim denial in Houston, Fitts Law Firm, PLLC can help you understand your rights under Texas law. Call 713-871-1670 or schedule a consultation today to talk through your situation.

Disclaimer: This content is for informational purposes only and is not legal advice. Every case is unique, and results may vary. Consult an attorney about your specific circumstances.
woman standing in kitchen looking inside open stainless steel refrigerator with food

Can Houston Homeowners Claim Spoiled Food After Beryl’s Power Outages?

Spoiled Food After Hurricane Beryl: What Your Policy May Cover

Key Takeaways: Many Houston homeowners may be able to recover the cost of food that spoiled during Hurricane Beryl’s power outages, depending on their policy language. Some policies include a food spoilage endorsement with its own limit. Others cover spoilage only if a covered peril, such as wind damage to the home, caused the outage, and off-premises power failure exclusions or high windstorm deductibles may limit recovery. Texas Insurance Code Chapter 542 sets deadlines for insurers to acknowledge, decide, and pay claims, and late payment can lead to interest and attorney’s fees. For hurricane claims, Chapter 542A may limit those fees. Chapter 541 bars unfair claim practices, including delaying settlement just because a third party, such as the utility, may be responsible, unless the policy specifically allows it. Strong documentation and attention to the two-year Chapter 541 limitations period can help homeowners protect their rights.

Many Houston homeowners may be able to recover the cost of spoiled food after Hurricane Beryl, but the answer depends on the language in their homeowners policy. Beryl knocked out power across the Houston area in July 2024, and many families lost full refrigerators and freezers. Some policies include food spoilage coverage, often as an endorsement with its own dollar limit. Others cover the loss only if the outage came from a covered peril, such as wind damage to the home. If your insurer denied, underpaid, or ignored your claim, Texas law sets deadlines and standards the insurer generally has to meet.

If your insurer has denied or stalled your claim, you do not have to sort it out by yourself. The team at Fitts Law Firm, PLLC works with Texas policyholders whose storm claims were disputed. Call 713-871-1670 or contact us now to talk about your situation.

Trash bags beside cooler with attached note sit curbside outside residence

How Power Outage Coverage Works in Houston Homeowners Insurance

Power outage coverage usually depends on three things: where the outage started, what caused it, and whether your policy includes a food spoilage provision. Many standard policies exclude losses caused by a power failure away from the insured property. Many make an exception when the off-site failure leads to a covered peril on your property, but then only the damage from that peril is covered. Because policy forms vary, the declarations page and endorsements usually decide the outcome.

Common Policy Provisions That Affect Your Claim

Several types of policy language may come up in a food spoilage claim. Homeowners may want to look for:

  • A food spoilage or "refrigerated property" endorsement, which often has a fairly low limit, such as $500
  • An "off-premises power failure" exclusion, along with any exceptions
  • Windstorm coverage that applies when storm damage to the home itself cut the power
  • A separate windstorm deductible, which may be larger than the value of the lost food
  • Personal property (Coverage C) provisions that may list food as covered contents

The deductible is often the practical obstacle. If a hurricane or named-storm deductible exceeds your food loss, the insurer may owe nothing for food alone. If the spoilage is part of a larger claim from the same covered loss, such as roof damage, it may count toward the total and help you exceed the deductible.

💡 Pro Tip: Ask your insurer for a certified copy of your full policy, including every endorsement. The summary in your online account may leave out the food spoilage endorsement that controls your claim.

Texas Deadlines That Apply to Hurricane Beryl Insurance Claims

Texas law generally requires insurers to move Hurricane Beryl insurance claims forward on a set timeline. The Texas Prompt Payment of Claims Act, found in Texas Insurance Code Chapter 542, lays out these duties. Subchapter B, beginning at Section 542.051, lists the insurer’s specific deadlines. After a weather-related catastrophe or major natural disaster, insurers may get an extra 15 days.

Stage General Deadline Statute
Acknowledge claim, begin investigation, request documents 15 days after notice (30 business days for eligible surplus lines insurers) Tex. Ins. Code § 542.055
Accept or reject claim in writing 15 business days after receiving all required items; a 30-day extension applies only where the insurer reasonably believes the loss resulted from arson Tex. Ins. Code § 542.056(a)-(c)
Extension if insurer needs more time Must notify you of its reasons within that period, then decide within 45 days after that notice Tex. Ins. Code § 542.056(d)
Payment after receiving all requested items Payment generally due within 5 business days after the insurer accepts the claim. The insurer may be liable for damages if payment comes more than 60 days after it received all requested items Tex. Ins. Code §§ 542.057, 542.058(a)

What the Insurer Must Do After Notice

Under Tex. Ins. Code § 542.055(a)-(c), the insurer generally has 15 days after notice of a claim to acknowledge it, start investigating, and ask for the documents it reasonably believes it needs. For eligible surplus lines insurers, this acknowledgment and investigation period extends to 30 business days. For a food spoilage claim, those might include photos, receipts, or an inventory of what spoiled. A rejection generally must explain the reasons, as required by Tex. Ins. Code § 542.056(c).

Penalties for Late Payment

When an insurer owes a claim and breaks these rules, Tex. Ins. Code § 542.060 provides for statutory damages. In general, the insurer must pay the claim plus interest at 18 percent per year, along with reasonable attorney’s fees. Claims governed by Chapter 542A, which covers property damage from forces of nature such as hurricanes, generally use a different rate: simple interest at the rate set under Tex. Fin. Code § 304.003 plus 5 percent. Chapter 542A may also limit or bar attorney’s fees, and it requires pre-suit notice.

When a Denial May Be an Unfair Claim Practice

Some denials may amount to unfair settlement practices under Texas law. Tex. Ins. Code § 541.060(a)(1)-(4) and (7) lists conduct that includes:

  • Misrepresenting a material fact or policy provision about coverage
  • Failing to try in good faith to settle promptly and fairly once liability is reasonably clear
  • Failing to promptly explain a denial or compromise offer
  • Failing to confirm or deny coverage within a reasonable time
  • Refusing to pay without a reasonable investigation

The "Blame the Utility" Response

After Hurricane Beryl, some insurers may point to the electric utility as the real cause of the outage. Tex. Ins. Code § 541.060(a)(5) generally bars an insurer from refusing, failing, or unreasonably delaying a first-party settlement offer because other coverage might exist or because third parties are responsible, unless the policy specifically allows it. This rule does not override a valid off-premises power failure exclusion. Whether it helps you depends on your policy wording and what actually caused the outage at your home.

Under Tex. Ins. Code § 541.151, a person who suffers actual damages from an unfair or deceptive insurance practice may sue the person responsible. The full text appears in Texas Insurance Code Chapter 541. Proving such a claim generally takes written records showing what the insurer did and how it harmed you.

Building a Stronger Food Spoilage Claim

Good documentation is often the deciding factor in a disputed spoilage claim. Insurers commonly question how much food was lost, what it was worth, and whether the outage caused the loss.

Start by putting together an itemized inventory with approximate purchase dates and prices. Add photos of the spoiled food taken before you threw it away, grocery receipts or loyalty-card purchase history, and any utility outage notices showing how long your power was off. Save every email, letter, and adjuster note, and write down the date of each phone call.

💡 Pro Tip: When an adjuster gives you a reason over the phone, send a short follow-up email summarizing what was said. That gives you a written record if the explanation changes later.

For more guidance on storm claims, you can find related articles on Houston homeowners insurance. They may help you understand related issues, such as wind damage and underpayment disputes after major storms.

Under Tex. Ins. Code § 541.162(a), a lawsuit under Chapter 541 generally must be filed within two years of the date the unfair practice happened, or the date you discovered it or reasonably should have discovered it. Section 541.162(b) allows a 180-day extension only if you prove that you sued late because the insurer knowingly acted solely to get you to put off suing. Courts generally read these exceptions narrowly. Other deadlines may also apply:

  • Breach-of-contract claims generally have a four-year limitations period, but a policy may shorten it to as little as two years.
  • Chapter 542A generally requires written notice at least 61 days before you sue.

Because Beryl struck in July 2024, some deadlines may already be close or may have passed.

A Hurricane Beryl insurance claims lawyer can review which deadlines may apply to your situation. The right timeline depends on your policy, how the claim was handled, and when the disputed conduct took place.

Frequently Asked Questions

  1. Does every Houston homeowners policy cover spoiled food?

No. Coverage depends on your policy form and endorsements. Some include a food spoilage endorsement with a set limit. Others cover spoilage only if a covered peril damaged your property and caused the outage.

  1. Can my insurer deny the claim because the utility caused the outage?

It depends on the policy. Tex. Ins. Code § 541.060(a)(5) generally bars an insurer from delaying a first-party settlement because a third party may be responsible, unless the policy specifically says otherwise. Off-premises power failure exclusions may still apply.

  1. How long does my insurer have to decide my claim?

In general, the insurer must accept or reject the claim in writing within 15 business days after receiving all required items, under Tex. Ins. Code § 542.056. If it needs more time, it must notify you of its reasons within that period, and then has up to 45 days to decide.

  1. What happens if my insurer pays late?

If the insurer owes the claim and violated the prompt payment rules, Tex. Ins. Code § 542.060 provides for interest damages and reasonable attorney’s fees. For hurricane-related claims governed by Chapter 542A, a lower interest rate generally applies and attorney’s fees may be limited.

  1. Is it too late to dispute a Hurricane Beryl claim?

It may not be, but timing matters. Chapter 541 claims generally carry a two-year limitations period under Tex. Ins. Code § 541.162. Contract claims and policy terms may set other deadlines.

Protecting Your Rights After Beryl’s Outages

Spoiled food claims can seem small, but they are generally subject to the same Texas laws that govern any other homeowners claim. Whether you can recover depends on your policy language, the cause of the outage, your deductible, and your documentation. Results depend on the specific facts of each case.

If your Hurricane Beryl claim was denied, delayed, or underpaid, getting a legal review may help you understand your options. Reach out to Fitts Law Firm, PLLC, call 713-871-1670, or schedule a consultation today.

Disclaimer: This content is for informational purposes only and is not legal advice. Every case is unique, and results may vary. Consult an attorney about your specific circumstances.
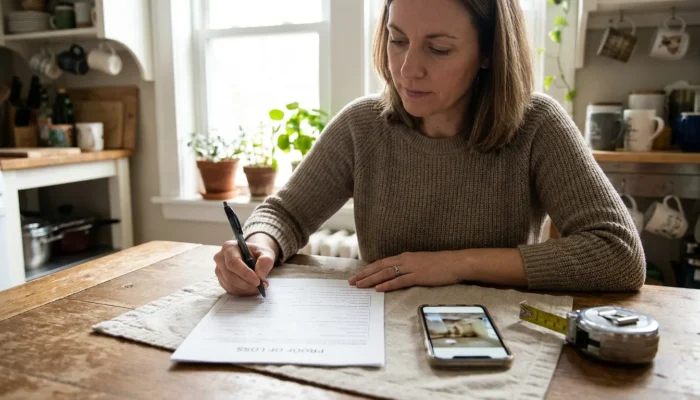
Woman filling out Proof of Loss form beside smartphone and tape measure

How to Fill Out a Proof of Loss Form Without Hurting Your Home Claim

What Houston Homeowners Should Know Before Signing a Sworn Proof of Loss

Key Takeaways: To fill out a proof of loss form without hurting your home claim, be accurate and complete, back every figure with documents, and never sign numbers you don’t understand or agree with, such as an adjuster’s lower estimate. The form is usually a sworn statement, so honest, well-supported estimates can help protect you, while knowingly false statements can carry serious consequences under Texas law. Under the Texas Prompt Payment of Claims Act, a complete submission can start statutory deadlines, and insurers generally must accept or reject a claim within 15 business days after receiving all requested items. Use the insurer’s written request list as your guide, note when figures are preliminary, send the form in a way that creates a delivery record, and log every conversation. If an insurer wrongly delays or denies a claim it owes, it may have to pay interest and attorney’s fees on top of the claim. Weather-related claims under Chapter 542A follow different interest, attorney’s fee, and pre-suit notice rules.

You fill out a proof of loss form well by being accurate, complete, and supported by documents, and by never signing numbers you do not understand. Insurers often treat the form as a sworn statement. A rushed answer, an underestimate, or a missing attachment can delay your claim or give the insurer a reason to dispute it. For Texas homeowners recovering from hail, wind, flooding, or hurricane damage, knowing how the form works and which deadlines it triggers may help protect the claim from the start.

If your insurer is pressing you to sign paperwork or has already denied your claim, Fitts Law Firm, PLLC can help you understand your rights. Call 713-871-1670 or contact us now to talk about your situation.

Proof of Loss form with pens resting on wooden dining table

Why the Proof of Loss Insurance Form Carries So Much Weight

A proof of loss is your formal, sworn account of what was damaged and how much you are claiming. Many homeowners policies require one after a loss, and the insurer generally relies on it to evaluate the claim. For background, see our guide explaining what a proof of loss is.

The form matters legally because it can start statutory deadlines. The Texas Prompt Payment of Claims Act, found in Texas Insurance Code Chapter 542, Subchapter B (Tex. Ins. Code §§ 542.051, 542.061), sets deadlines for insurers to acknowledge, investigate, and accept or reject claims. Under Tex. Ins. Code § 542.056(a), the insurer generally must accept or reject the claim in writing within 15 business days after it receives all the items, statements, and forms it required to secure final proof of loss. A complete submission, with proof of the delivery date, can therefore start that clock.

The Sworn Nature of the Statement

Because you usually sign the form under oath, accuracy matters more than speed. Insurers may challenge statements they believe are inflated or misleading, and knowingly false statements on insurance claims can carry serious consequences under Texas law, including Texas Penal Code Chapter 35. Honest estimates backed by documents generally protect you. Do not guess at figures you cannot support.

Step-by-Step Proof of Loss Instructions for Texas Homeowners

Start with the insurer’s own list of what it wants. Under Tex. Ins. Code § 542.055(a), (b), within 15 days of receiving notice of a claim, a Texas insurer generally must acknowledge it, begin investigating, and request every item, statement, and form it reasonably believes it will need. Eligible surplus lines insurers generally have 30 business days. The insurer may ask for more information later if the investigation requires it. That written request list generally defines a complete package, so keep it.

Filling In Each Section Carefully

Most proof of loss forms ask for similar core information:

  • Policy details: Your policy number, policy period, and the coverage limits on your declarations page.
  • Date and cause of loss: Use the actual storm date and describe the cause plainly, such as "hail" or "wind-driven rain," without guessing about technical causation.
  • Amount claimed: Base it on contractor estimates, receipts, and inventories rather than the adjuster’s figure alone.
  • Other insurance and interests: List any mortgage company or other policies that may cover the loss.
  • Supporting documents: Attach photos, videos, estimates, invoices, and contents lists.

💡 Pro Tip: If you don’t yet know the full extent of the damage, note in writing that the amount is preliminary and that you reserve the right to supplement it as hidden damage is found. Whether that language protects you can depend on your policy wording.

Common Mistakes That Can Hurt a Claim

One of the most common problems is signing an insurer-prepared form showing the adjuster’s lower number. Signing a figure you disagree with may later be used to suggest you agreed with it. Other mistakes include leaving sections blank, missing the policy deadline, and failing to keep a copy. Each can give an insurer a reason to delay or argue the claim is incomplete.

Key Texas Deadlines Your Claim Documentation Can Trigger

Several statutory clocks depend on when the insurer has what it asked for. The table below summarizes the main ones, though exceptions apply and the facts of each claim can change how they work.

Stage General Deadline Authority
Acknowledge claim and request documents 15 days after notice of claim (30 business days for eligible surplus lines insurers) Tex. Ins. Code § 542.055
Accept or reject after final proof of loss 15 business days (30 days if arson is reasonably suspected) Tex. Ins. Code § 542.056(a), (b)
Extension notice Must be sent within the original period; decision then due within 45 days after that notice Tex. Ins. Code § 542.056(d)
Payment after receiving requested items Period set by other statutes, or 60 days if none applies (payment generally due within 5 business days after the insurer notifies you it will pay) Tex. Ins. Code §§ 542.057, 542.058(a)

Denials generally must come with reasons. Under Tex. Ins. Code § 542.056(c), if the insurer rejects the claim, the written notice must state why. That explanation may matter if you later challenge a denial.

Protecting Your Rights When Submitting Insurance Paperwork

Texas law also prohibits unfair claim handling beyond the prompt-pay deadlines. Texas Insurance Code Chapter 541 addresses unfair practices, and the Texas Department of Insurance has adopted rules under 28 Tex. Admin. Code Chapter 21, Subchapter C (Sections 21.201-21.205), titled Unfair Claims Settlement Practices. The unfair claim settlement rules set minimum standards for how insurers investigate and settle claims in Texas, including in Houston, including how they request documentation. Repeated or unnecessary requests that delay a claim without good reason may raise concerns under these rules.

Documenting Every Contact

Keep a written record of every interaction with the insurer. Under Tex. Ins. Code § 542.055(c), if the insurer acknowledges your claim other than in writing, it must keep a record of the date, manner, and content of that acknowledgment. Keep your own log too: the date, the adjuster’s name, and what was said in every call, and send follow-up emails confirming important conversations.

💡 Pro Tip: Send your completed proof of loss using a method that creates a delivery record, such as certified mail or an email with attachments, and save the confirmation. That record can help show when statutory deadlines began.

What Happens If the Insurer Delays or Wrongly Denies the Claim

An insurer that is liable for a claim and violates the prompt-payment rules may owe more than the claim itself. Under Tex. Ins. Code § 542.060(a), it may owe the claim amount plus interest at 18 percent a year as damages, along with reasonable and necessary attorney’s fees. You can read the full Texas prompt payment statute for the complete text.

Weather-related claims often follow different interest rules. For lawsuits governed by Chapter 542A, which typically covers weather-related property claims like hail, wind, and hurricane damage common around Houston, Tex. Ins. Code § 542.060(c) instead provides simple interest at the rate determined under Texas Finance Code § 304.003 plus five percent. Attorney’s fees are governed and may be limited by Tex. Ins. Code § 542A.007. Chapter 542A also generally requires written notice at least 61 days before filing suit. Lawsuit deadlines in your policy and under Texas statutes of limitations are separate from these claim-handling deadlines and generally keep running while the claim is pending.

A homeowner may have claims for breach of contract and for violations of the Insurance Code. Whether those claims exist depends on the policy language, the evidence of causation and damages, and how the insurer handled the claim. A proof of loss insurance form lawyer can review whether the insurer’s conduct may support recovery.

Frequently Asked Questions

1. Do I have to accept the insurer’s numbers on the proof of loss form?

Generally, no. You can submit your own figures supported by contractor estimates and documentation. Signing the adjuster’s lower number may be treated as agreement, so review it carefully first.

2. What if I find more damage after I submit the form?

Many policies allow supplemental claims, but terms vary. Noting that your figures are preliminary and promptly reporting newly discovered damage may help protect your ability to recover more.

3. Can the insurer keep asking for more documents?

The insurer may request more information if its investigation reasonably requires it, under Tex. Ins. Code § 542.055(b). Unreasonable or repetitive requests that delay resolution may raise unfair claim settlement concerns.

4. How long does the insurer have to decide after I submit everything?

Generally, 15 business days after receiving all requested items under Tex. Ins. Code § 542.056(a), or 30 days if arson is reasonably suspected. If the insurer notifies you within that period that it needs more time and explains why, it must decide within 45 days after that notice under § 542.056(d).

5. Does a mistake on the form mean my claim will be denied?

Not necessarily. Honest mistakes can often be corrected, especially if you fix them quickly and in writing. Knowingly false statements, however, can create serious problems.

Submitting Your Claim With Confidence

A carefully completed proof of loss may help you avoid claim denial and start important Texas deadlines. Use the insurer’s written request list, back up every figure with documents, keep proof of delivery, and log every conversation. If the insurer delays, underpays, or denies the claim, Texas Insurance Code Chapter 542 may provide remedies, but outcomes depend on the facts of your claim.

If you are dealing with a delayed or denied homeowners claim, Fitts Law Firm, PLLC is ready to review your proof of loss and claim history. Call 713-871-1670 or schedule your consultation today.

Disclaimer: This content is for informational purposes only and is not legal advice. Every case is unique, and results may vary. Consult an attorney about your specific circumstances.
Rolling scaffolding beside dumpster filled with roofing debris and wood scraps

What Does Overhead and Profit Cover Besides Labor and Materials?

Understanding the Hidden Costs in Your Houston Home Repair Estimate

Key Takeaways: Besides labor and materials, overhead and profit (O&P) generally pays for a contractor’s business costs of managing your repair, such as supervision, scheduling subcontractors, permits, insurance, and office work. The profit portion pays the contractor for the risk of a multi-trade repair. It is often figured as "10 and 10," meaning 10% overhead plus 10% profit. Insurers often pay O&P when a loss is complex enough to reasonably need a general contractor, but no Texas statute requires it in every claim. Texas Insurance Code Chapter 541 bars insurers from misrepresenting coverage, refusing to pay without a reasonable investigation, or failing to promptly explain a denial or reduction. A policyholder who wins may recover actual damages, court costs, and attorney’s fees, and up to three times actual damages if the insurer acted knowingly. A policyholder generally must give 61 days’ written notice before suing, and some exceptions and limits apply. Keep careful records, make O&P requests in writing, and be careful about signing a release while O&P is still in dispute.

Overhead and profit (O&P) generally covers the business costs a general contractor incurs to manage your repair, beyond the raw price of labor and materials. These costs typically include supervision, scheduling subcontractors, pulling permits, carrying business insurance, and administrative work. The profit portion pays the contractor for the risk of running the job. For Houston homeowners recovering from hail, wind, or hurricane damage, understanding O&P can help you spot an underpaid claim before you accept a short settlement.

If your insurer left O&P out of your estimate or denied part of your claim, you can talk with a lawyer before you sign anything. Fitts Law Firm, PLLC helps Texas policyholders review disputed estimates and insurer conduct. Call 713-871-1670 or contact us now to discuss your situation.

construction worker in hard hat and safety vest walking past pickup truck jobsite

The Overhead and Profit Insurance Definition Explained

Overhead and profit are standard markups commonly added to a repair estimate to pay a general contractor for managing and coordinating subcontractors on complex jobs. These markups are separate from the direct cost of labor and materials. A roofer’s wage and the price of shingles show up as line items. The work of planning the job, keeping crews on schedule, and making sure the repair passes inspection generally does not.

Many estimates express O&P as a percentage of the repair cost. A common convention is 10% overhead and 10% profit, often called "10 and 10," though actual percentages can vary. Insurers and contractors often build estimates in software such as Xactimate, which lets the adjuster add O&P as a separate line. Whether that line appears often depends on how the adjuster views the job’s complexity.

What Overhead Covers

Overhead generally covers the costs of running a business and managing your specific project. Common components include:

  • Project supervision and on-site management
  • Scheduling and coordinating multiple trades, such as roofing, gutters, siding, and drywall
  • Obtaining permits and arranging inspections
  • General liability and workers’ compensation insurance
  • Office staff, accounting, and administrative tasks
  • Vehicles, equipment, and job-site cleanup

What Profit Covers

Profit is the contractor’s return for taking responsibility for the project and its risks. A general contractor managing a multi-trade repair typically takes on liability for subcontractors’ work quality, delays, and cost overruns. Without profit, few legitimate contractors would likely agree to manage a complex storm repair.

💡 Pro Tip: Ask your contractor for a written breakdown of which trades the project requires and who will coordinate them. A clear list can help show that a general contractor is reasonably needed.

When Insurers Are Expected to Pay O&P

Insurers often pay O&P when the complexity of the loss reasonably requires a general contractor. The Texas Department of Insurance’s roofing and insurance guidance offers consumers information on roofing claims and contractor practices. Adjusters generally look at whether multiple trades must be coordinated.

Consumer advocacy groups take a similar view. United Policyholders notes that many courts and state regulators treat O&P as a legitimate, payable cost when the loss reasonably requires the contractor to use subcontractors. This is advocacy guidance, not a statute requiring O&P in every claim. Your policy language and the facts of your loss carry significant weight.

Common Reasons Adjusters Leave O&P Out

Adjusters may exclude O&P for several reasons, and some hold up better than others. The table below compares common insurer positions with questions a homeowner might raise.

Insurer’s Position Questions to Raise
"The job involves only one trade." Does the repair actually require roofing, gutters, interior, or electrical work?
"O&P is never owed." Does the policy actually say that, or is the adjuster misstating it?
"O&P is paid only after repairs are done." What does the policy say about replacement cost holdback?
"You don’t need a general contractor." Who will pull permits and coordinate crews?

Texas Laws That Protect You When O&P Is Cut

Texas law prohibits certain unfair settlement practices, and several may apply when an insurer cuts O&P. Under Texas Insurance Code Chapter 541, an insurer may not engage in the conduct below. Whether any provision applies depends on the facts of your claim.

Key Provisions of Tex. Ins. Code § 541.060

Tex. Ins. Code § 541.060(a)(1) makes it an unfair practice to misrepresent a material fact or policy provision relating to coverage at issue. Under § 541.060(a)(2)(A), it is also unfair to fail to try in good faith to reach a prompt, fair, and equitable settlement once liability has become reasonably clear. A homeowner may raise these provisions if an adjuster wrongly says O&P is never owed.

Under Tex. Ins. Code § 541.060(a)(3), an insurer must promptly give a reasonable explanation for denying a claim or offering a compromise settlement. If your estimate leaves out O&P, you can ask the insurer in writing to explain the omission.

Tex. Ins. Code § 541.060(a)(4) and (a)(7) address delay and inadequate investigation. Under (a)(7), it is unfair to refuse to pay a claim without a reasonable investigation. Under (a)(4), it is unfair to fail, within a reasonable time, to affirm or deny coverage or to send a reservation of rights.

Tex. Ins. Code § 541.060(a)(6) bars an insurer from trying to get a release that covers more than the amount it actually paid as a condition of paying part of a claim. An exception applies when the payment is a compromise settlement of a doubtful or disputed claim. Be cautious about signing a release while O&P or other items remain in dispute. If you are weighing whether to accept a lowball claim offer, review any release language closely first.

Prompt Payment Deadlines

Texas prompt payment rules in Chapter 542 also set timing requirements. Under Tex. Ins. Code § 542.055(a), an insurer generally must acknowledge a claim, start investigating, and request needed items within 15 days of receiving notice. For an eligible surplus lines insurer, that deadline is 30 business days.

What Remedies May Be Available

A policyholder who prevails under Chapter 541 may recover actual damages, court costs, and reasonable and necessary attorney’s fees under Tex. Ins. Code § 541.152(a). If the insurer acted knowingly, the trier of fact may award up to three times actual damages under § 541.152(b). Under § 541.152(c), that provision does not apply to actions against the Texas Windstorm Insurance Association (TWIA), whose claims are governed by separate procedures under Insurance Code Chapter 2210.

Before filing suit, a claimant generally must give written notice at least 61 days in advance under Tex. Ins. Code § 541.154(a)-(b). The notice must state the specific complaint and the amount of actual damages and expenses, including attorney’s fees reasonably incurred. Under § 541.154(c), notice is not required if suit must be filed right away to prevent the limitations period from expiring, or if the claim is a counterclaim. Separate presuit notice rules under Chapter 542A may also apply to many weather-related property claims.

A settlement offer is not an admission of wrongdoing. Under Tex. Ins. Code § 541.160, an insurer’s settlement offer is not an admission that it committed an unfair or deceptive practice. A partial O&P supplement does not prove wrongdoing, and it does not necessarily resolve your claim either.

Protecting Your Claim and Avoiding Pitfalls

Strong documentation is often the most useful tool in an O&P dispute. Keep copies of every estimate, adjuster email, and letter. Write down the date and substance of every phone call. Get an independent contractor’s estimate that lists each trade involved.

Be wary of anyone who inflates O&P or offers to "cover your deductible." Under Texas law, a contractor who waives, absorbs, or rebates a homeowner’s deductible may be committing an offense, and inflated billing can amount to insurance fraud. Legitimate O&P should reflect real supervision and administrative costs, not padded profit.

💡 Pro Tip: Make all of your O&P requests to the insurer in writing. A written request creates a record of whether, and when, the insurer gave a reasonable explanation.

Outcomes in O&P disputes depend heavily on the policy wording and the facts of the repair. An overhead and profit insurance definition lawyer can review whether your estimate reflects what a real repair would cost and whether the insurer’s conduct raises concerns under Texas law.

Frequently Asked Questions

1. What is the O&P definition in a homeowners insurance claim?

O&P stands for overhead and profit. It is a markup, often around 20% combined, that generally pays a general contractor for supervising, coordinating, permitting, and managing the business side of a repair. It is separate from labor and materials.

2. Does my insurer have to pay O&P?

It depends on your policy and the facts. Insurers often pay O&P when the job is complex enough to reasonably require a general contractor to coordinate several trades. No Texas statute requires O&P in every claim.

3. Can my insurer withhold O&P until repairs are finished?

Some replacement cost policies let insurers hold back certain amounts until repairs are completed. Whether O&P can be held back depends on the policy wording and the facts. Review your policy’s loss settlement provisions and ask the insurer to explain its position in writing.

4. Should I sign a release if O&P is still in dispute?

Use caution. Tex. Ins. Code § 541.060(a)(6) bars an insurer from requiring a release broader than the amount paid as a condition of partial payment, with an exception for compromise settlements of disputed claims. Read any release carefully before signing.

5. How long does my insurer have to respond to my claim?

Under Tex. Ins. Code § 542.055(a), insurers generally must acknowledge a claim, begin investigating, and request needed information within 15 days of notice. Eligible surplus lines insurers have 30 business days. Later deadlines apply for accepting or rejecting the claim and for payment.

Getting the Full Value of Your Repair Estimate

Overhead and profit generally covers much more than profit margin; it pays for the supervision, permits, insurance, and coordination a complex repair requires. Understanding O&P helps Houston homeowners recognize when an estimate falls short. Texas law prohibits insurers from refusing to pay claims without a reasonable investigation, failing to promptly explain denials or compromise offers, and misrepresenting coverage. Careful documentation can help you hold your insurer to those standards.

If your insurer cut or denied O&P on your storm damage claim, you can get help reviewing your options. Fitts Law Firm, PLLC represents Texas policyholders in disputes with insurance companies. Call 713-871-1670 or schedule your consultation today.

Disclaimer: This content is for informational purposes only and is not legal advice. Every case is unique, and results may vary. Consult an attorney about your specific circumstances.
Cut floor section exposing pipes with shop vacuum and work lights nearby

Does Homeowners Insurance Cover Slab Leak Tear-Out in Texas?

Slab Leak Claims in Texas: What Your Policy May Actually Pay For

Key Takeaways: Many Texas homeowners insurance policies cover the cost of tearing out and replacing slabs, floors, or walls to reach a leaking pipe, even though repairing the pipe itself is often excluded as wear and tear. Coverage for the resulting water damage often depends on whether the leak was sudden and accidental or gradual, and insurers frequently deny claims by citing wear and tear, earth movement, or long-term seepage. Chapter 541 of the Texas Insurance Code prohibits insurers from misrepresenting coverage, refusing to pay without a reasonable investigation, failing to explain denials, and enforcing full releases after only partial payments. Homeowners harmed by unfair practices may recover actual damages, court costs, and reasonable and necessary attorney’s fees. If the insurer acted knowingly, they may recover up to three times actual damages. Filing deadlines vary by claim type and policy terms, so homeowners should act promptly and keep detailed records from their plumber and adjuster.

Many Texas homeowners insurance policies cover the cost of tearing out and replacing parts of a home to reach a leaking pipe under the slab, even when they won’t pay to fix the pipe itself. This "tear out and replace" or access cost coverage is often where slab leak claims are won or lost. Whether your policy pays depends on its wording, what caused the leak, and whether the water damage happened suddenly or over time. If your insurer has denied, delayed, or underpaid your claim, Texas law may give you specific protections.

If your insurer is refusing to pay for tear-out or access costs, you don’t have to sort it out by yourself. Fitts Law Firm, PLLC helps Houston homeowners review denied and underpaid property claims. Call 713-871-1670 or contact us now to talk about your situation.

service technician carrying tool bag and case from van toward residential home

How Slab Leak Insurance Coverage Generally Works

Slab leak coverage usually splits a loss into three parts: the broken pipe, the access work, and the resulting water damage. Most policies don’t pay to repair or replace the failed plumbing itself. Many do pay to break through the slab, flooring, or walls to reach the leak and then restore those areas. Coverage for water damage often depends on how and when it happened.

The Three Parts of a Typical Slab Leak Claim

Separating these parts can help you see which parts of a denial may be open to challenge. Insurers sometimes deny the whole claim when only part of it falls under an exclusion. The table below shows the general pattern, though your own policy language controls.

Claim Component Typical Treatment Common Insurer Argument
Repairing the broken pipe Often excluded Wear and tear or deterioration
Tear-out and replace (access) costs Often covered Leak wasn’t "sudden and accidental"
Resulting water damage Depends on the facts Gradual leakage or long-term seepage
Foundation movement damage Often excluded or sublimited Earth movement or settling exclusion

Sudden and Accidental vs. Gradual Leakage

The difference between sudden and gradual damage often decides a water damage dispute. Many Texas policies treat sudden and accidental discharges of water more favorably than slow, long-term leaks, though wording varies. Slab leaks are hidden under concrete, so you may not see signs for some time, and insurers may use that delay to argue the damage was gradual. You can find more in United Policyholders’ Texas homeowners claim FAQ.

Why Insurers Deny Slab Leak Tear-Out Coverage

Insurers usually deny tear-out coverage by relying on exclusions for wear and tear, earth movement, or gradual leakage. Some denials hold up under the policy. Others may misread the policy or skip a proper investigation. Common reasons include:

  • The leak resulted from deterioration or ordinary wear
  • Foundation movement, not plumbing failure, caused the damage
  • The water leaked over weeks or months
  • The homeowner reported the loss too late
  • Tear-out costs were "unnecessary" or overstated

Each reason depends on the facts, and the insurer’s engineer or plumber may not be the last word. Finding a slab leak’s source often takes leak detection, hydrostatic pressure tests, and qualified plumbers. An independent evaluation can give you evidence to answer an insurer’s causation findings.

💡 Pro Tip: Ask your plumber to document in writing where the leak was, how it was found, and why each area had to be opened. Detailed access documentation often makes an access cost claim harder to dispute.

Texas Laws That Protect Policyholders

Chapter 541 of the Texas Insurance Code bans specific unfair settlement practices that often come up in slab leak disputes. These rules apply to how insurers handle claims, not just whether coverage exists. You can read the full text of Texas unfair insurance practices law on the Texas Legislature’s website.

Misrepresenting Your Coverage

Under Tex. Ins. Code § 541.060(a)(1), an insurer may not misrepresent a material fact or policy provision about the coverage at issue. That can apply when an adjuster wrongly says your policy doesn’t pay for tearing out and replacing a slab, flooring, or walls to reach a leaking pipe. Tex. Ins. Code § 541.061(1), (3), and (4) separately ban misrepresenting a policy through untrue statements of material fact, statements that would mislead a reasonably prudent person, or material misstatements of law.

Investigation, Explanation, and Timing Duties

Texas law sets standards for how insurers investigate and explain their decisions. Under Tex. Ins. Code § 541.060(a)(4) and (a)(7), it is unfair to fail, within a reasonable time, to affirm or deny coverage or send a reservation of rights, or to refuse to pay a claim without a reasonable investigation. Tex. Ins. Code § 541.060(a)(3) also requires an insurer to promptly give a reasonable explanation, based on the policy, the facts, or applicable law, for denying a claim or offering a compromise. A vague denial letter may not meet that standard.

Lowball Offers and Partial Payment Releases

Once liability has become reasonably clear, Tex. Ins. Code § 541.060(a)(2)(A) requires a good faith attempt at a prompt, fair, and equitable settlement. This may matter if your insurer admits a covered leak but delays or underpays the tear-out work. Under Tex. Ins. Code § 541.060(a)(6), an insurer also cannot try to enforce a full and final release when it has made only a partial payment, unless that payment compromises a doubtful or disputed claim. Read any release carefully before you sign it.

What You May Recover and How Long You Have

Under Tex. Ins. Code § 541.151, a homeowner who suffers actual damages from an unfair practice may sue the insurer directly. Tex. Ins. Code § 541.152(a)-(c) allows a winning plaintiff to recover actual damages, court costs, and reasonable and necessary attorney’s fees. If the insurer acted knowingly, the judge or jury may award up to three times actual damages. That treble damages provision does not apply to suits against the Texas Windstorm Insurance Association.

Deadlines matter, and they depend on the type of claim. Texas generally allows four years for breach of written contract claims under Tex. Civ. Prac. & Rem. Code § 16.004, and two years for many property damage and tort claims under Tex. Civ. Prac. & Rem. Code § 16.003. Many policies also include shorter suit limitation periods, which Texas law generally allows if they are at least two years. Chapter 541 claims usually must be filed within two years of the unfair practice, or of when the homeowner discovered or reasonably should have discovered it, under Tex. Ins. Code § 541.162. Courts read exceptions such as the discovery rule narrowly, so don’t assume a deadline will be extended. A complaint to the Texas Department of Insurance is a separate administrative process and generally does not pause the deadline for a civil lawsuit.

💡 Pro Tip: Keep a written log of every call with your adjuster, including the date, the person’s name, and what was said. Follow up important calls with an email.

Practical Steps After a Slab Leak Denial

If your claim was denied or underpaid, start by getting the full policy and the written denial. Compare the insurer’s stated reasons with the policy’s actual wording, especially the access or tear-out provisions. Get your own repair estimates and leak detection reports. Our denied insurance claims page explains how these disputes often move forward, including appraisal and possible litigation.

Frequently Asked Questions

1. Does my policy pay to fix the broken pipe under my slab?

In many cases, no. Repairing the pipe itself is often excluded as wear and tear. Tear-out and access costs, however, may be covered depending on your policy wording.

2. What are access costs in a Texas slab leak claim?

Access costs are the expenses of breaking through floors, walls, or the slab to reach the leak, and then restoring those areas. Many Texas policies treat these separately from the plumbing repair. How much is covered depends on the policy wording and the facts.

3. Can my insurer deny the claim because the leak was gradual?

Insurers often make this argument, but it depends on the evidence and the policy wording. Hidden slab leaks may go unnoticed without any fault on your part. Independent leak detection and plumbing reports may help address the insurer’s causation theory.

4. Should I sign a release after a partial payment?

Think carefully first. Tex. Ins. Code § 541.060(a)(6) limits an insurer’s ability to enforce a full release after only a partial payment, although there is an exception for compromises of disputed claims. Having the document reviewed before you sign may protect your rights.

5. Where can I learn more about homeowners claim disputes?

You can read more about common property insurance issues on the Fitts Law Firm insurance claims blog. These articles cover general topics and don’t replace advice about your specific facts.

Protecting Your Right to a Fair Slab Leak Claim Payout

Slab leak claims often turn on the line between excluded plumbing repair and covered tear-out and replace work. Texas law requires insurers to investigate reasonably, explain denials, and avoid misrepresenting coverage. When they fail to do so, homeowners may have contract and statutory remedies, subject to filing deadlines and the facts of each case.

If you believe your insurer wrongly denied or underpaid your slab leak claim, Fitts Law Firm, PLLC can review your policy and denial letter. Call 713-871-1670 or schedule your consultation today to discuss your options.

Disclaimer: This content is for informational purposes only and is not legal advice. Every case is unique, and results may vary. Consult an attorney about your specific circumstances.