Author: fittslawfirm

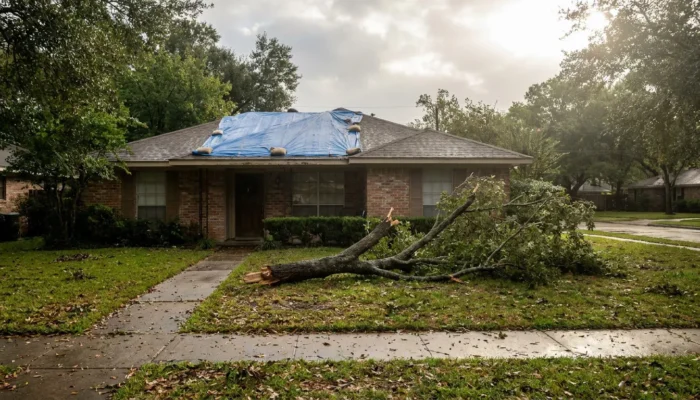
storm-damaged brick home with tarp-covered roof and fallen tree in yard

What Is an Act of God Clause in a Houston Homeowners Insurance Policy?

Storm Damage, Denied Claims, and the Fine Print Houston Homeowners Overlook

Key Takeaways: An "act of God" clause refers to policy language addressing losses from natural forces such as hurricanes, hail, windstorms, floods, lightning, and earthquakes. Under Texas law, the doctrine generally applies only when a loss is caused exclusively by natural forces without contributing human negligence. Many Houston denials labeled this way may actually stem from written policy exclusions, anti-concurrent causation provisions, or wind-versus-flood causation disputes rather than the common-law doctrine itself. A storm-related explanation generally does not suspend your insurer’s obligations under Chapter 542 of the Texas Insurance Code, which requires written denial notices with reasons and imposes prompt payment deadlines backed by statutory interest and attorney’s fees. Chapter 542A adds further requirements for most weather-related claims, including pre-suit notice and a modified interest calculation. Carriers still owe a reasonable investigation, and rushed inspections or conclusory denial letters may raise unfair settlement practice concerns. Important carve-outs exist: TWIA, NFIP flood, and personal umbrella policies are excluded from the prompt payment subchapter, meaning one hurricane can trigger three claims under three rulebooks. Preserving photographs, independent inspections, the full claim file, and written records, while tracking suit-limitation deadlines, can help Houston homeowners challenge a questionable denial.

An "act of God" clause addresses losses caused by natural forces such as hurricanes, hail, windstorms, floods, lightning, and earthquakes. Under Texas law, the doctrine generally refers to an event caused exclusively by natural forces, without human negligence contributing to the loss. Insurers sometimes invoke that concept to justify denying, delaying, or underpaying a claim. Understanding what the clause actually says, and what Texas law may still require of your insurer, can affect the outcome of a disputed claim.

If your carrier denied a Houston claim by pointing to storm or natural-disaster language, you do not have to accept that answer at face value. The policyholder attorneys at Fitts Law Firm, PLLC review denial letters, policy provisions, and adjuster reports for homeowners across the Houston area. Call 713-871-1670 or contact us now to discuss your situation.
homeowners insurance policy binder, flood zone map, and walkie-talkie on wooden table

What the Act of God Definition in Insurance Actually Means

Texas courts developed the "act of God" doctrine long before it appeared in modern property policies. Courts historically applied it in liability contexts to excuse responsibility for damage caused by unforeseeable natural events such as storms and floods. The act of God doctrine in Texas has been analyzed by Texas legal commentators, including a San Antonio law school examining how state courts apply the concept.

The legal test is narrower than most homeowners assume. For an event to qualify, damage generally must result exclusively from natural causes, with no human negligence contributing to the loss. That standard can matter in Houston, where hurricane damage often involves mixed causation: aging roof components, prior unrepaired damage, contractor workmanship, or deferred maintenance alongside genuine wind and water forces.

Here is the practical takeaway. A standard Texas homeowners policy is a first-party property contract rather than a general liability policy, so the common-law "act of God" defense may not map cleanly onto a homeowners claim. What the insurer calls an "act of God" may really be a named exclusion, an anti-concurrent causation provision, or a wind-versus-flood dispute dressed in older terminology. Coverage in a first-party dispute is determined primarily by the policy’s own language, not the common-law doctrine.

How an Act of God Clause Homeowners Insurance Dispute Usually Unfolds

Many Houston disputes begin with a causation fight rather than a coverage denial. A standard residential property policy typically covers windstorm and hail (subject to endorsements, exclusions, and separate deductibles) while excluding flood, surface water, and often earth movement. After a tropical system, the adjuster or a retained engineer may attribute the loss entirely to rising water, typically excluded, rather than wind-driven rain or wind-opened building envelopes, which may be covered depending on policy wording.

Texas law anticipates this confusion and requires advance warning. Under Texas Department of Insurance requirements, an insurer whose residential policy does not cover flooding must generally provide notice stating that the policy does not cover damage from flood even if hurricane winds and rain caused the flood to occur. This is a disclosure obligation, however, and failing to deliver it does not automatically create flood coverage.

Policy exclusions, rather than the common-law doctrine, tend to do most of the work in these denials. If your denial letter cites specific numbered provisions, you may be dealing with written exclusionary language rather than a general natural-forces defense. Texas courts generally enforce anti-concurrent causation clauses as written, and under the doctrine of concurrent causes, an insured typically bears the burden of segregating damage attributable to a covered peril from an excluded one. Our overview of what a policy exclusion means walks through how these provisions commonly drive Houston claim denials.

💡 Pro Tip: Photograph roof decking, soffits, and interior water lines before any repairs. Wind-versus-flood causation is often decided by physical evidence that disappears the moment a mitigation crew arrives.

What Texas Law Still Requires After a Storm Denial

A natural-disaster explanation generally does not suspend your insurer’s statutory obligations. Chapter 542 of the Texas Insurance Code sets deadlines and requirements governing how insurers must acknowledge, investigate, and pay or deny claims. Subchapter B generally applies to policies issued by insurers authorized to do business in Texas, including homeowners policies, subject to statutory exclusions discussed below. For claims arising from forces of nature such as hurricanes, windstorms, and hail, Chapter 542A also applies and adds requirements, including a pre-suit notice letter that generally must be sent before filing suit.

Written Explanations Are Mandatory

Your insurer is generally required to put the denial in writing. Tex. Ins. Code § 542.056 generally requires an insurer to notify the claimant in writing of its acceptance or rejection of a claim, typically within 15 business days after receiving all reasonably requested items, and to state the reasons for rejection. Longer periods apply in certain circumstances, including surplus lines claims and weather-related catastrophes. A vague phone call referencing "the storm exclusion" generally does not satisfy that obligation, and the written reasons given can become central in later litigation.

Prompt Payment Deadlines and Penalties

Once a claim is accepted, the payment clock generally runs. The prompt payment of claims provisions in Subchapter B set insurer deadlines for acknowledgment, investigation, and decisions, and § 542.060 provides for statutory interest plus reasonable attorney’s fees when an insurer is liable and fails to comply. For most weather-related claims under Chapter 542A, interest is calculated at five percent above the judgment interest rate rather than the older flat 18 percent, and Chapter 542A may also limit recoverable attorney’s fees based on the amount ultimately awarded. These remedies generally require that the insurer be liable on the claim, and may apply to accepted claims simply not paid on time.

The Catastrophe Extension Houston Homeowners Should Know

Texas law recognizes that major hurricanes can legitimately slow claim handling. Under Texas Insurance Code Section 542.059, claim-handling deadlines for property insurance claims are automatically extended by an additional 15 days in the event of a weather-related catastrophe or major natural disaster as defined by the commissioner. These extensions are limited in scope and duration, but they may explain why carriers stretch timelines after a major Houston storm instead of denying claims outright.

Unfair Settlement Practices That Often Accompany These Denials

An insurer invoking storm language generally still owes you a good-faith investigation. Chapter 541 of the Texas Insurance Code identifies certain conduct as unfair settlement practices, including refusing to pay a claim without a reasonable investigation. A drive-by inspection, a desk review of satellite imagery, or a denial issued before any meaningful roof inspection may raise serious questions.

Two additional practices appear frequently in Houston denial disputes:

  • Misrepresenting a material fact or policy provision relating to coverage at issue
  • Failing to promptly provide a reasonable explanation of the policy basis for denying a claim

Whether any of these apply depends heavily on the specific facts of your claim file. Courts evaluate the reasonableness of an investigation case by case, and not every causation disagreement rises to a statutory violation. Texas courts have also held that an insured generally must show an injury independent of the policy benefits themselves to recover extra-contractual damages, absent limited exceptions. Still, a rushed inspection followed by a conclusory denial letter is a pattern policyholder counsel sees repeatedly after Gulf Coast storms.

Not Every Houston Homeowners Insurance Policy Follows the Same Rules

Certain specialized policies are carved out from the prompt payment subchapter. Texas law provides that the subchapter does not apply to a Texas Windstorm Insurance Association policy, a National Flood Insurance Program policy, or a personal umbrella policy. Houston-area homeowners often carry more than one of these simultaneously. TWIA claims follow their own statutory dispute process under Chapter 2210, and NFIP flood claims are governed by federal law and must generally be litigated in federal court under the Standard Flood Insurance Policy’s own deadlines.

Coverage Type Typical Storm Losses Addressed Prompt Pay Subchapter Application
Standard residential property policy Wind, hail, lightning, falling objects Generally applies
TWIA windstorm policy Named-storm wind and hail in designated coastal areas Expressly excluded
NFIP flood policy Rising water, storm surge, surface flooding Expressly excluded
Personal umbrella policy Excess liability, not first-party property damage Expressly excluded

This matters because the same hurricane may trigger three different claims under three different rulebooks. A homeowner may receive a prompt, compliant response on one claim and slow, unexplained handling on another. Identifying which policy governs which portion of the loss is one of the first steps in evaluating a denial.

Practical Steps After an Act of God Coverage Denial in Texas

Documentation often drives outcomes more than argument does. Policyholders who preserve evidence early may be better positioned to rebut an insurer-retained engineer’s causation report. Consider these steps:

  • Request the complete claim file and the insurer’s engineering or adjuster reports in writing
  • Obtain an independent inspection from a licensed contractor or engineer of your own choosing
  • Preserve dated photographs, video, weather data, and repair estimates
  • Keep a written log of every call, adjuster visit, and payment or denial communication
  • Read your declarations page carefully to confirm deductibles, endorsements, and any windstorm exclusions

💡 Pro Tip: Send follow-up emails summarizing every phone conversation with your adjuster. A contemporaneous written record often carries more weight later than memory does.

Deadlines deserve particular attention, and they are not all the same. Contractual suit-limitation provisions, the Chapter 542A pre-suit notice requirement, policy conditions such as prompt notice of loss and sworn proof of loss, and the civil statute of limitations generally operate independently. Breach of contract claims in Texas ordinarily carry a four-year limitations period, but policies frequently contain shorter suit-limitation clauses, which Texas law generally will not enforce below two years. Courts generally construe tolling and discovery-rule exceptions narrowly, so waiting to act can carry real risk.

When Professional Review of Your Denial Makes Sense

Some denials are correct, and honest evaluation requires acknowledging that. If a policy plainly excludes flood and the loss was unambiguously caused by rising water with no covered wind component, the outcome may be difficult to change. Legitimate exclusions exist, and no attorney can guarantee a particular result.

Other denials may rest on incomplete investigation, misapplied policy language, or contested causation opinions. Those are the claims where a detailed policy review, independent expert evidence, and, where appropriate, litigation under Chapters 541, 542, and 542A could potentially change the picture. A Texas act of God clause attorney can assess which category your claim may fall into based on the actual documents.

Frequently Asked Questions

1. Is an "act of God" clause the same thing as a policy exclusion?

Not exactly, though the two overlap in practice. The act of God definition in insurance derives from common-law doctrine generally requiring that natural causes be the sole cause of loss, while exclusions are specific contractual provisions in your policy. In a first-party dispute, the policy language typically controls, and many modern Houston denials rely on written exclusions, with the doctrinal label serving as shorthand rather than the actual legal basis.

2. Can my insurer deny my claim just by saying a hurricane caused the damage?

Generally, no. A hurricane is a covered peril in part (wind and hail) and excluded in part (flood) under most standard policies. The insurer is generally expected to identify the policy provision supporting its position and, under § 542.056, to provide written reasons for rejecting the claim within the applicable statutory deadline.

3. What if my insurer is simply taking too long rather than denying my claim?

Delay has its own statutory framework. Chapter 542, Subchapter B governs acknowledgment, investigation, and payment deadlines, and § 542.060 provides for interest and attorney’s fees where the insurer is liable and fails to comply, with Chapter 542A modifying the interest calculation for weather-related claims. A catastrophe extension may lawfully change those timelines after a major storm.

4. Does the prompt payment law apply to my TWIA or flood policy?

Generally not in the same way. Texas law expressly excludes TWIA policies, NFIP flood policies, and personal umbrella policies from that subchapter. TWIA claims follow Chapter 2210 procedures and NFIP claims follow federal rules, which is why identifying the correct policy early is important.

5. How long do I have to challenge a denied homeowners claim in Texas?

It depends on your policy language and the claims asserted. Breach of contract claims generally carry a four-year limitations period, but policies frequently contain contractual suit-limitation clauses that shorten it, and Texas law generally does not permit shortening below two years. Chapter 542A also requires pre-suit notice before filing most weather-related claims. Because these deadlines are fact-specific and exceptions are often construed narrowly, prompt review of your documents is advisable.

Protecting Your Claim After a Houston Storm

An act of God clause homeowners insurance dispute rarely turns on the phrase itself. It generally turns on causation evidence, the precise exclusionary language in your Houston homeowners insurance policy, and whether your carrier met its statutory duties to investigate reasonably, explain its decision in writing, and pay covered claims promptly. Texas law provides meaningful protections, subject to important carve-outs for TWIA, NFIP, and umbrella coverage and the additional requirements of Chapter 542A, and outcomes always depend on the specific facts and documents involved.

If a denial letter left you with more questions than answers, a careful review of your policy and claim file is the right next step. Fitts Law Firm, PLLC represents Houston-area policyholders, never insurance companies. Call 713-871-1670 or reach out to our team to have your denied or delayed claim reviewed.

Disclaimer: This content is for informational purposes only and is not legal advice. Every case is unique, and results may vary. Consult an attorney about your specific circumstances.
ladder leaning against brick home roof with shingle packages on ground

What Is Recoverable Depreciation on a Houston Homeowners Claim?

Why Your Insurance Check Is Smaller Than the Estimate

Key Takeaways: Recoverable depreciation is the portion of a Houston homeowner’s replacement cost claim that the insurer withholds from the first payment and generally releases only after repairs are completed and documented. Replacement cost policies typically pay in two stages: an initial actual cash value payment (replacement cost minus depreciation, with the deductible applied), followed by the depreciation holdback. Texas Insurance Code Chapter 707 requires policyholders to pay their deductible and permits insurers to withhold the holdback until they receive reasonable proof the deductible was paid, including a canceled check, credit card statement, or financing contract. TWIA policyholders insured at 80 percent or more of full replacement cost may receive full repair costs without any depreciation deduction under § 2210.207, though TWIA coverage applies only in the designated catastrophe area, which includes just a small portion of Harris County. Not all depreciation is recoverable, so reviewing your declarations page, endorsements, and itemized statement of loss is essential. Disputes commonly involve excessive depreciation, refusal to release the holdback, or scope disagreements, and may be addressed through an independent estimate, appraisal, or legal action.

Recoverable depreciation is the portion of your claim payment your insurer generally holds back until you finish repairs and provide the required proof. If a Houston adjuster estimated $30,000 to replace your storm-damaged roof but the first check was only $19,000, the difference likely reflects depreciation withheld under a replacement cost policy, plus your deductible. That money isn’t necessarily lost, it may become payable once you complete the work and submit the required documentation.

If your carrier has withheld depreciation and now refuses to release it, the team at Fitts Law Firm, PLLC can review your policy and claim file. Call 713-871-1670 or contact our office today to discuss your options.

contractor documents, nail gun, work gloves, and material samples on truck tailgate

How a Replacement Cost Policy Splits Your Payment in Two

Most Texas homeowners policies written on a replacement cost basis pay claims in two stages. The first payment reflects actual cash value, replacement cost reduced by depreciation for age, wear, and condition, with the deductible then subtracted. The second payment, the depreciation holdback, is generally released after you repair or replace the property and submit proof.

This structure explains why many Harris County policyholders feel shortchanged after a hailstorm. The initial ACV payment can look far too small compared to a contractor’s bid, but it’s often incomplete rather than wrong, since the balance sits in the recoverable depreciation line item.

Not all depreciation is recoverable, and that distinction matters. If your policy insures a roof or other components on an actual cash value basis, or contains a roof payment schedule endorsement, the depreciation may be non-recoverable and permanently deducted. Reviewing your declarations page and endorsements is the most reliable way to determine which category applies.

Reading the Statement of Loss Line by Line

Your adjuster’s estimate should itemize replacement cost value, depreciation, the deductible, and the net ACV payment. Request a full itemized estimate rather than a summary page, and look for a column labeled "Depreciation" confirming whether it’s marked recoverable.

Common problems include excessive depreciation percentages, depreciated labor costs, and missing line items for code-required upgrades, all of which can shrink the ACV payment beyond what the policy supports. Documenting these concerns in writing creates a record if a dispute develops later.

The Texas Statutory Framework Behind Depreciation Holdbacks

Texas Insurance Code Chapter 707, Payment of Insurance Deductible, is the statute most often invoked when a carrier withholds recoverable depreciation. It requires policyholders to pay any deductible applicable to a first-party claim and sets out when an insurer may condition payment of a replacement cost holdback on proof of that payment. Chapter 707 doesn’t dictate how depreciation is calculated; how ACV is determined generally turns on the policy form, TDI requirements, and case law. Even so, homeowners can request a complete itemized estimate showing how the withheld amount was determined rather than accepting an unexplained lump-sum reduction.

Chapter 707 also conditions payment of the holdback on one specific homeowner obligation. Texas Insurance Code § 707.004 provides that "an insurer that issues a property insurance policy with replacement cost coverage may refuse to pay a claim for withheld recoverable depreciation or a replacement cost holdback under the policy until the insurer receives reasonable proof of payment by the policyholder of any deductible applicable to the claim." The Texas replacement cost coverage statute applies statewide, though application can depend on the policy and facts involved.

The statute also identifies examples of reasonable proof of deductible payment. Under § 707.004, this "includes a canceled check, money order receipt, credit card statement, or copy of an executed installment plan contract or other financing arrangement that requires full payment of the deductible over time." This provision, added by the 86th Legislature, took effect September 1, 2019, and because the list is inclusive rather than exclusive, a financed deductible may satisfy the requirement under certain circumstances.

💡 Pro Tip: Keep every canceled check, card statement, and signed financing contract related to your deductible in one folder. These documents are frequently the gatekeeper for releasing your depreciation holdback.

Windstorm Policies and the 80 Percent Replacement Cost Rule

Homeowners with Texas Windstorm Insurance Association coverage face a different depreciation analysis. TWIA is the state’s insurer of last resort for wind and hail damage in the Commissioner-designated catastrophe area, which includes the 14 first-tier coastal counties and only a limited part of Harris County, property inside the city limits of La Porte, Morgan’s Point, Pasadena, Seabrook, or Shoreacres and east of Highway 146. Most Houston-area homeowners instead carry wind and hail coverage under a standard homeowners policy. For those who do hold TWIA coverage, its claims materials explain that the initial payment reflects ACV and that additional recoverable depreciation may be issued upon repair completion.

The governing statute creates a meaningful advantage for adequately insured properties. Texas Insurance Code § 2210.207(c) provides that if, on the effective date of an association policy, total insurance on a dwelling "is equal to 80 percent or more of the full replacement cost of the dwelling or equal to the maximum amount of insurance otherwise available through the association, coverage applicable to the dwelling under the policy is extended to include the full cost of repair or replacement, without a deduction for depreciation." That extension remains subject to the policy’s limits, deductible, and other conditions.

Falling below that threshold changes the math significantly. Under § 2210.207(d), if total insurance on a dwelling "is equal to less than 80 percent of the full replacement cost of the dwelling and less than the maximum amount of insurance available through the association, liability for loss under the policy may not exceed the replacement cost of the part of the dwelling that is damaged or destroyed, less depreciation." TWIA’s published guidance on factors impacting claim payments identifies coverage type, depreciation, and the deductible as the key variables driving what an insured actually receives.

Payment Concept What It Represents When It Is Paid
Replacement Cost Value (RCV) Full cost to repair or replace with like kind and quality Total potential claim value
Actual Cash Value (ACV) RCV minus depreciation, with the deductible then applied Initial claim payment
Recoverable Depreciation The withheld difference between RCV and ACV After repairs and required proof
Non-Recoverable Depreciation Depreciation permanently deducted under policy terms Not released under the policy terms

Steps That Typically Unlock the Holdback

Releasing withheld depreciation usually requires a documented paper trail rather than a phone call. Requirements vary by policy and carrier, but homeowners generally strengthen their position by assembling:

  • Final invoices from licensed contractors showing work actually performed
  • Proof of deductible payment consistent with § 707.004
  • Before-and-after photographs of the damaged and repaired areas
  • Written confirmation of any supplemental damage discovered during repairs
  • A dated written request for release of the depreciation holdback

Timing also matters. Many replacement cost provisions require repairs to be completed within a defined period after the loss, and missing that window can jeopardize the holdback, though some policies allow extensions on request. Reviewing those deadlines early is wiser than discovering them after a contractor delay.

When a Recoverable Depreciation Homeowners Claim Texas Dispute Escalates

Disputes over depreciation typically fall into three categories: excessive depreciation, wrongful refusal to release the holdback, and disagreement over the scope of repair. Each may require a different response. Excessive depreciation often calls for an independent estimate rebutting the carrier’s figures, while a refusal to release funds after documented repairs may raise breach of contract and prompt payment concerns.

Texas policyholders also have rights regarding claim handling timelines. Guidance on insurance legal rights in Texas outlines the prompt payment provisions of Insurance Code Chapter 542 and insurer response deadlines that apply to property claims. How those deadlines apply to a depreciation holdback is fact-dependent, and certain claims are subject to the pre-suit notice and procedural requirements of Chapter 542A.

Many Texas policies also contain an appraisal clause as a dispute-resolution mechanism separate from litigation. When the disagreement concerns the amount of loss rather than coverage, appraisal may resolve valuation and depreciation questions, although appraisers generally cannot decide coverage or liability issues. Appraisal isn’t appropriate for every dispute, and invoking it can affect other claim rights, so the decision deserves careful analysis before you agree.

Homeowners who receive a settlement offer far below their contractor’s estimate should think carefully before signing anything. Our discussion of whether Houston homeowners should accept a lowball claim offer explains what is often at stake. If your carrier has denied the holdback outright, a recoverable depreciation homeowners claim Texas lawyer can evaluate whether the refusal is supported by the policy language.

💡 Pro Tip: Send every request for depreciation release by email or certified mail. Verbal requests are difficult to prove, and the date of your submission frequently determines whether prompt payment deadlines were triggered.

Frequently Asked Questions

1. Is recoverable depreciation the same as my deductible?

No, they are separate deductions. Your deductible is the amount you agreed to pay out of pocket on every covered loss, while recoverable depreciation reflects the value lost to age and wear on the damaged property. Both typically reduce your initial payment, but only the depreciation portion may become payable later.

2. What happens if I decide not to repair my home?

If you don’t complete repairs, the withheld depreciation generally remains unpaid. Replacement cost coverage is typically conditioned on actually repairing or replacing the property, so a homeowner who keeps the ACV payment and skips the work may forfeit the holdback. Some carriers permit recovery for partial repairs, subject to the specific policy terms.

3. Can my insurer refuse to release depreciation if I financed my deductible?

Not necessarily. Texas Insurance Code § 707.004 lists an executed installment plan contract or other financing arrangement requiring full payment of the deductible over time among the examples of reasonable proof of payment. Whether a particular arrangement satisfies the statute depends on its terms and documentation.

4. How much time do I have to act on an underpaid claim?

Deadlines vary depending on the claim and the legal theory involved. Texas property insurance disputes may be subject to contractual limitation provisions in the policy as well as statutory limitations periods, and courts generally apply exceptions such as tolling or the discovery rule narrowly. Because these deadlines can be shorter than homeowners expect, prompt review is advisable.

5. Does depreciation apply to labor as well as materials?

This remains a fact-sensitive and sometimes contested issue in Texas property claims. Carriers frequently depreciate labor costs, and policyholders often challenge that practice depending on the policy language at issue. The answer generally turns on how the specific contract defines actual cash value.

Protecting the Full Value of Your Claim Settlement in Houston

Recoverable depreciation is not a penalty, but it can become one when an insurer refuses to release funds a homeowner may be owed. Understanding your declarations page, identifying the depreciation line item, documenting completed repairs, and preserving proof of deductible payment are practical steps that can help convert a withheld balance into a payment. Texas Insurance Code Chapter 707 and, for eligible windstorm policyholders, § 2210.207 shape those rights, alongside the policy’s own replacement cost provisions. Outcomes always depend on the specific policy language and the facts of your loss.

If an insurer is stalling, underpaying, or denying your depreciation holdback, the attorneys at Fitts Law Firm, PLLC are prepared to help. Call 713-871-1670 or request a case review to discuss your Houston homeowners claim.

Disclaimer: This content is for informational purposes only and is not legal advice. Every case is unique, and results may vary. Consult an attorney about your specific circumstances.
residential exterior showing detached gutter, stained siding, and deteriorating window trim

What Is the Faulty Workmanship Exclusion in a Houston Homeowners Policy?

Why Houston Insurers Point to "Workmanship" When Denying Storm and Water Damage Claims

Key Takeaways: The faulty workmanship exclusion is a provision in most Texas homeowners policies that removes coverage for damage caused by defective, inadequate, or improper construction, repair, materials, design, or maintenance. Houston insurers frequently invoke it after hail, wind, or water losses, often relying on an engineering report attributing damage to installation error rather than the storm. The exclusion is legitimate and appears in policy forms filed with or promulgated by the Texas Department of Insurance, and under Texas law the insurer generally bears the burden of proving that an exclusion applies to the loss actually claimed. Concurrent causation language, ensuing loss exceptions, and differences among HO-A, HO-B, and Texas FAIR Plan policies can all change the outcome. Texas Insurance Code § 541.060(a) addresses denials made without a reasonable investigation or explanation of the policy basis, and § 542.058(a) sets out separate prompt payment deadlines. Because causation disputes are fact-intensive and limitations deadlines can be unforgiving, gathering the full policy, the insurer’s complete report, and independent documentation early is often critical.

The faulty workmanship exclusion removes coverage for damage caused by defective, inadequate, or improper construction, repair, or materials. Your insurer may pay for a sudden covered loss while refusing to pay for damage it attributes to a contractor’s mistake, a poorly installed roof, or substandard building work. Houston policyholders often encounter this after hail, wind, or water losses, when an insurer-retained engineer concludes the real cause was installation error rather than the storm. Whether that conclusion holds up generally depends on the policy language, the evidence of causation, and how thoroughly the insurer actually investigated the claim.

If a workmanship denial has left you holding the repair bill, the attorneys at Fitts Law Firm, PLLC are prepared to review your policy and the insurer’s findings. Call 713-871-1670 or contact us now to discuss your options.

residential room with damaged wall patch, desk lamp, and blank document

How the Exclusion Actually Reads in a Texas Policy

Standard Texas homeowners forms generally exclude loss caused by "faulty, inadequate, or defective" workmanship, materials, design, or maintenance. These aren’t phrases adjusters invent on the spot. TDI historically promulgated the standardized HO-A and HO-B forms sold in Houston. The TDI-promulgated HO-B form does not itself contain a workmanship exclusion; that exclusion appears in insurer-filed and TDI-approved forms, such as ISO HO 00 03 and various carrier-specific forms, that became more common after 2003 legislative changes allowing insurers to file their own policy forms subject to TDI approval. The operative question is what your particular form says, not what a "standard" policy once said.

That regulatory backdrop matters because it can change the argument. An insurer generally cannot simply assert that "we don’t cover contractor error" as a matter of custom; under Texas law it bears the burden of pleading and proving an exclusion applies, which requires identifying the exclusionary language and showing the facts fit it. Separate statutory protections govern related insurer conduct, including notice and justification requirements for cancellation, denial, and nonrenewal of residential property policies under Texas Insurance Code Chapter 551. Ambiguities in exclusionary language are generally construed in favor of coverage.

Texas law also treats construction quality as an insurance issue in certain settings. Texas Insurance Code § 2210.258 generally conditions eligibility for windstorm and hail coverage through the Texas Windstorm Insurance Association on certification that construction, alteration, remodeling, or repair in the catastrophe area complies with applicable building code standards described in TWIA’s plan of operation, with requirements depending on when the work was done. That statute doesn’t decide a homeowners claim, but it illustrates why carriers treat substandard work as a distinct risk category.

Where Carriers Overreach on a Faulty Workmanship Exclusion Homeowners Claim

A common problem is not that the exclusion exists, but that it may be applied too broadly. A roof may have been installed imperfectly and still have failed because of a hailstorm. Texas courts generally require the insurer to connect the excluded cause to the loss actually claimed, and causation is frequently fact-dependent and contested by competing experts. Where an insurer relies on a brief engineering report that never examines storm data or the interior water path, the conclusion may be vulnerable.

Denial letters also tend to be vague. Homeowners often receive a letter citing "faulty workmanship" with no identification of the specific policy provision, no explanation of what the inspection found, and no response to the homeowner’s own contractor documentation. Understanding what a policy exclusion is and how carriers deploy exclusions is often the first step toward recognizing a weak denial.

Concurrent Causation and Anti-Concurrent Language

Many disputes turn on what happens when a covered peril and an excluded peril combine. Some Texas forms include anti-concurrent causation language attempting to bar recovery whenever an excluded cause contributes to the loss, and Texas courts have enforced such language in some contexts while limiting it in others depending on wording. Absent that language, concurrent causation doctrine generally allows recovery only for damage attributable to the covered peril, and the policyholder bears the burden of segregating covered from excluded damage. Outcomes vary considerably based on the exact wording at issue.

Ensuing Loss Provisions

Workmanship exclusions frequently contain an exception for resulting or "ensuing" loss. If defective installation leads to a separate covered peril, such as sudden water discharge damaging drywall and flooring, the resulting damage may still be covered even though the defective component itself is not. These clauses are often narrowly construed and heavily litigated, and some forms omit them entirely, so availability generally depends on the precise language in your form.

Comparing Coverage Scope Across Texas Policy Types

Not every Texas property policy carries the same breadth of coverage. Homeowners who cannot obtain standard-market coverage may hold a Texas FAIR Plan policy, a residual market product that generally covers a narrower set of perils and commonly excludes faulty workmanship, maintenance-related damage, and gradual deterioration.

Policy Type General Coverage Scope Typical Treatment of Workmanship
HO-A (Texas) Named perils, limited Generally excluded, with narrow exceptions
HO-B / HO-B Modified Open-perils (all-risk) coverage for dwelling TDI-promulgated HO-B does not contain this exclusion; insurer-filed forms may exclude, with ensuing loss potentially applying
Texas FAIR Plan Narrow, basic perils Commonly excluded expressly

What the Texas Insurance Code Requires of Your Insurer

Even when a carrier believes an exclusion applies, it generally remains bound by statutory conduct standards. Under Texas Insurance Code § 541.060(a), it may be an unfair settlement practice to misrepresent a material fact or policy provision, fail to promptly provide a reasonable explanation of a denial, or refuse to pay a claim without a reasonable investigation. A denial letter reciting "faulty workmanship" without identifying the provision or investigation may raise questions under that section, although Texas courts generally require a policyholder to show independent injury or an underlying breach of the policy to recover on such a theory.

Deadlines may apply independently of the coverage dispute. Texas Insurance Code § 542.058(a) generally provides that an insurer delaying payment more than 60 days after receiving all reasonably requested items, statements, and forms, or beyond a different period specified by law, is liable for damages under § 542.060. Chapter 542 also contains separate deadlines for acknowledging, investigating, and accepting or rejecting a claim, subject to conditions and exceptions depending on when the insurer received complete documentation.

💡 Pro Tip: Send every supplemental document by a method that creates a written record, and note the date. Prompt payment arguments often rise or fall on proving exactly when the insurer received the last required item.

Practical Steps After a Workmanship Denial in Houston

Documentation often separates a frustrating denial from a provable claim. Before conceding that an exclusion applies, many policyholders may benefit from building an independent record rather than relying on the carrier’s file.

  • Request a complete copy of your policy, including all endorsements and the declarations page.
  • Obtain the insurer’s full engineering or inspection report, not just the denial letter’s summary.
  • Have a licensed contractor or independent engineer document the cause of damage in writing.
  • Preserve photographs, repair invoices, roof age records, and any prior inspection reports.
  • Keep a dated log of every call, adjuster visit, and written communication.

A regulatory complaint is a separate track from a civil lawsuit. Texas homeowners who believe a claim was wrongly denied may file a complaint with the Texas Department of Insurance, which reviews complaints and may take enforcement action against an insurer that violated Texas insurance law or its own policy terms. TDI generally cannot order a carrier to pay a disputed claim and does not act as your attorney, so a complaint generally supplements rather than replaces legal remedies. Useful items to include typically involve the policy number, the denial letter, and prior correspondence with the carrier.

A workmanship denial is often a conclusion, not a fact. If the insurer’s report is short on analysis, ignores storm evidence, or fails to address an ensuing loss, closer review may reveal that the exclusion was applied more broadly than the language allows. A faulty workmanship exclusion homeowners claim lawyer can evaluate the policy form, the causation evidence, and whether statutory deadlines were met.

Timing considerations apply and can be unforgiving. Contractual limitations provisions, the pre-suit notice requirement under Texas Insurance Code Chapter 542A for many property claims, and statutory limitations periods all operate on different clocks, and courts generally interpret extensions and discovery-based exceptions narrowly. Because these deadlines are fact-sensitive, policyholders may be better served by seeking review early rather than waiting to see whether an internal appeal succeeds.

Frequently Asked Questions

1. Does the faulty workmanship exclusion apply if a storm caused the damage?

Not necessarily. If a covered peril such as hail or windstorm caused the loss, the exclusion may not control, though the analysis depends on the policy’s causation language and the competing evidence about what actually caused the damage.

2. Can I recover if a contractor’s error led to a water leak?

Possibly, in part. The defective work itself is generally excluded, but any ensuing water damage may be covered under certain forms, subject to how narrowly the ensuing loss provision is written or whether the form includes one at all.

3. What if my denial letter does not explain which exclusion applies?

That may itself be significant. Texas Insurance Code § 541.060(a) addresses an insurer’s failure to promptly provide a reasonable explanation of the basis for a denial, and a written request for clarification may create a useful record.

4. Does filing a TDI complaint affect my right to sue?

Filing a regulatory complaint is an administrative process separate from a civil lawsuit. It generally does not substitute for legal claims, extend litigation deadlines, or satisfy any required pre-suit notice.

5. How long does the insurer have to pay once it accepts a claim?

Texas prompt payment provisions impose specific deadlines to acknowledge, investigate, and accept or reject a claim, and to pay once accepted, with additional statutory damages and interest potentially available under § 542.060 in qualifying circumstances. The exact deadline may depend on the policy, the type of claim, and the date complete documentation was received.

Protecting Your Position After a Houston Claim Denial

The faulty workmanship exclusion is real, appears in TDI-approved insurer-filed forms, and is present in many Texas homeowners policies, but it is generally not a blanket license to deny storm-related damage. Carriers generally bear the burden of proving the exclusion applies, and they remain obligated to investigate reasonably and honor prompt payment duties under the Texas Insurance Code. Because causation disputes are fact-intensive and outcomes may turn on the exact wording of your policy, the strength of any challenge generally depends on the specific evidence available in your claim file.

If your claim was denied or underpaid based on alleged defective construction, Fitts Law Firm, PLLC can review the denial and explain your policyholder rights. Call 713-871-1670 or schedule a case review today.

Disclaimer: This content is for informational purposes only and is not legal advice. Every case is unique, and results may vary. Consult an attorney about your specific circumstances.
neglected single-story brick home with overgrown lawn and rolled documents on driveway

What Is the Vacancy Exclusion in a Houston Homeowners Insurance Policy?

When an Empty House Turns Into a Denied Claim

Key Takeaways: The vacancy exclusion is a clause in many Texas homeowners policies that may suspend coverage for certain perils, such as vandalism, theft, glass breakage, and some water damage, once a home sits empty beyond a defined period, commonly 30 or 60 days. It generally does not eliminate all coverage, and fire or windstorm protection may still apply depending on the policy form and endorsements. Some policies distinguish between a vacant home, stripped of the property needed for living, and an unoccupied one that still holds furnishings; where that distinction appears, the exclusion may be triggered only by true vacancy. Homeowners displaced by hurricane repairs, probate, relocation, or renovation may have arguments that the clause was misapplied. Texas Insurance Code § 541.060 identifies certain insurer conduct as an unfair settlement practice, including failing to investigate reasonably, failing to explain a denial in relation to the facts, and failing to attempt a good-faith settlement once liability has become reasonably clear. Documentation such as utility bills, dated photos, and written correspondence can be significant to the outcome, and filing deadlines make early action important.

The vacancy exclusion is a provision in many Texas homeowners policies that may limit or suspend coverage for certain damage once a home has sat empty beyond a set number of days, often 30 or 60. If your Houston house was unoccupied during a renovation, probate transfer, job relocation, or post-storm repair, and a pipe burst or vandals broke in, your insurer may point to that clause and refuse to pay. The exclusion is real, but it can also be misapplied, and a denial citing it isn’t necessarily the end of the conversation.

If an insurer has used this language to deny or delay your payment, Fitts Law Firm, PLLC is prepared to review the policy wording and the carrier’s investigation file. Call 713-871-1670 or reach out to our team today to discuss your claim.

empty room with hardwood floors, window blinds, and single cardboard moving box

The Vacancy Exclusion Definition and Why Carriers Rely on It

A vacancy exclusion generally suspends coverage for specific perils after a dwelling has been empty for a continuous period defined in the policy. Insurers argue an unoccupied structure carries elevated risk because no one is present to notice a slow leak, shut off water, deter intruders, or report a fire early.

Homeowners policies sold in Texas often contain exclusions and conditions that can limit or suspend coverage for certain perils if a home is left vacant for an extended period. Because Texas policy forms are not uniform, the precise wording controls.

The perils most commonly affected are vandalism, malicious mischief, theft, glass breakage, and water damage from plumbing or appliances. Depending on the form, a Texas insurer may deny a vandalism claim where the home has been vacant beyond the stated period, frequently 30 or 60 days. Provisions like this appear in versions of the HO-A and HO-B forms historically used in the state, but carriers now file their own forms, so the threshold and affected perils vary. Fire and windstorm coverage may survive a vacancy period under some forms, depending on the policy and any endorsement.

This provision is only one of many carve-outs buried in a policy. For a broader picture of how these clauses operate, see our discussion of what is a policy exclusion and why it drives so many denials in the Houston market.

Vacancy Versus Unoccupancy: A Distinction That Changes Outcomes

Under many policies these terms are not interchangeable, and conflating them is a common error in a vacancy exclusion claim denial. A vacant home is generally stripped of the personal property necessary for living in it. An unoccupied home still contains furniture, appliances, and belongings, but nobody is living there. Some policy forms trigger the exclusion only for true vacancy, while others expressly reach unoccupancy, so your policy’s defined terms determine which rule applies.

The Texas Department of Insurance encourages homeowners to read their own definitions closely and, when a property will sit empty, to ask about an endorsement. Its guidance on homeowners policy exclusions discusses coverage limits for vacant or unoccupied homes and options for extended absences.

Facts That Often Cut Against the Insurer

Coverage disputes over vacancy issues often turn on details the adjuster may have skipped:

  • Furniture, clothing, and household goods remained in the home
  • Utilities, including water and electricity, stayed connected
  • You or a family member visited regularly to check on the property
  • The absence was caused by mandatory evacuation or storm repairs
  • You always intended to return and never listed the home for sale

Storm Repairs Complicate the Timeline

Gulf Coast homeowners frequently end up out of their houses through no choice of their own. After a hurricane or major hail event, remediation crews, permitting delays, and contractor backlogs can keep a family displaced for months. Carriers sometimes count those months toward a vacancy period even though the displacement flowed from the covered loss itself, a position worth challenging, though some forms expressly address buildings under construction or repair.

Endorsements and the Duty to Notify

Many Texas policies require notice of a change in occupancy or vacancy, and some carriers offer a vacant dwelling endorsement or separate vacancy policy that restores limited coverage. If the carrier declines, the Texas FAIR Plan Association may be an option for owners who cannot obtain coverage in the voluntary market, though eligibility rules apply and vacant or unoccupied dwellings aren’t always eligible. Property left uninsured during a gap may be exposed in ways difficult to address after a loss occurs.

Texas Law Limits How Insurers Use a Vacancy Exclusion Homeowners Insurance Claim Denial

A carrier generally cannot simply recite the clause and close the file. Under Tex. Ins. Code § 541.060(a), it may be an unfair settlement practice to misrepresent a material fact or policy provision relating to coverage, to fail to attempt in good faith a prompt and equitable settlement once liability has become reasonably clear, and to refuse payment without a reasonable investigation. The full text of the unfair settlement practices statute sets out these standards, and a policyholder generally must show both a statutory violation and resulting damages to recover.

The same statute also addresses an insurer’s failure to promptly provide a reasonable explanation for a denial, and separate prompt-payment provisions in Tex. Ins. Code ch. 542 set deadlines for accepting or rejecting a claim. A denial letter citing a vacancy clause without tying it to specific facts about how long the home was empty, whether utilities were running, and whether you intended to return may fall short of that standard. Whether it does is fact-dependent and generally a question a court or jury would evaluate on the full record.

Separately, Tex. Ins. Code ch. 551, subch. C governs cancellation, nonrenewal, and related notice requirements for certain residential property policies, and § 551.105 addresses nonrenewal of policies and the notice required. Vacancy is a common reason carriers give for nonrenewal, so a homeowner may face both a denied claim and a lost policy. Claim-handling rules adopted by the Texas Department of Insurance, including 28 Tex. Admin. Code § 21.1004, apply statewide, including Houston, and come from state authority rather than city ordinance.

Issue What the Insurer Must Show What You Can Document
Length of vacancy Continuous days meeting the policy definition Utility bills, security logs, mail records
Definition met Property lacked contents for habitation Photos, inventories, moving records
Peril excluded The specific loss falls within the clause Cause-of-loss reports, independent inspection
Investigation Reasonable inquiry before denial Adjuster notes, correspondence, timeline

💡 Pro Tip: Request the complete certified policy and the carrier’s claim file in writing. The declarations page alone rarely contains the operative vacancy language.

Building a Response After a Vacancy Exclusion Claim Denial

Documentation is often significant in these disputes. Because vacancy tends to turn on facts rather than opinion, contemporaneous records may carry substantial weight. Gather utility statements showing active service, dated photographs of interior contents, repair vendor receipts, and any written communication showing the carrier knew the home was under repair.

Independent evidence also matters when causation is contested. If an insurer-retained engineer concludes damage occurred during an alleged vacancy window, an independent inspection may support a different timeline. Statewide guidance from the Texas disaster insurance manual discusses claim denials and related insurance problems that can arise after a disaster.

💡 Pro Tip: Put every request in writing and keep copies. Phone conversations with adjusters are difficult to prove later.

Deadlines Deserve Early Attention

Contract and statutory claims in Texas carry filing deadlines, and many policies also contain their own suit-limitation provisions that may shorten the time available, subject to statutory minimums for certain property policies. Courts have often interpreted tolling arguments and discovery-rule exceptions narrowly, so no homeowner should assume an extension will apply. Tex. Ins. Code ch. 541 generally requires written pre-suit notice before filing certain claims. Administrative complaints to a regulator are separate from a civil lawsuit and generally do not, on their own, preserve litigation deadlines.

Anyone weighing options after a denial may benefit from consulting a vacancy exclusion homeowners insurance claim lawyer before those windows close. Outcomes depend heavily on the specific policy form, the facts of the loss, and the carrier’s conduct.

Frequently Asked Questions

1. How many days can a Houston home sit empty before coverage changes?

Many Texas forms use a 30 or 60 day threshold, but the exact number appears in your policy and can differ by carrier and endorsement. Read the definitions section rather than relying on a general rule.

2. Does the exclusion apply if I was displaced by hurricane damage?

Not necessarily. When the absence results from the covered loss and repairs are underway, homeowners may have arguments that the property was under repair rather than vacant, though the result depends on the policy wording and the facts.

3. Can an insurer deny every type of damage under a vacancy clause?

Often no. Many vacancy provisions suspend only enumerated perils such as vandalism, theft, glass breakage, and certain water losses, and other coverages may remain intact, but some forms are written more broadly.

4. What should I do the day I receive a denial letter?

Preserve the letter, request the full policy and claim file in writing, photograph the property’s current condition, and consider speaking with an attorney before giving a recorded statement, so you understand the exclusion being asserted.

5. Can I get vacant home coverage in Texas if my carrier drops me?

Possibly. A vacant dwelling endorsement or specialty vacancy policy may be available from some carriers, and property owners unable to obtain coverage in the standard market may qualify for a state-backed residual market option, subject to eligibility rules.

Where This Leaves Houston Homeowners

The vacancy exclusion is a narrow, fact-driven provision that insurers sometimes stretch past its intended reach. Whether it affects your claim generally depends on the policy’s own vacancy exclusion definition, the length and nature of the absence, the peril involved, and whether the carrier actually investigated before denying. Texas law imposes obligations on insurers regarding investigation, explanation, and timing, and those obligations may give policyholders meaningful ground to stand on.

If an empty house insurance Houston dispute has stalled your recovery, the team at Fitts Law Firm, PLLC can evaluate the denial and explain your available paths forward. Call 713-871-1670 or schedule your case review now to get started.

Disclaimer: This content is for informational purposes only and is not legal advice. Every case is unique, and results may vary. Consult an attorney about your specific circumstances.
adult and child carrying luggage toward illuminated Holiday Inn Express hotel entrance

What Is Coverage D Loss of Use on a Houston Homeowners Policy?

Understanding the Coverage That Pays for Somewhere Else to Live

Key Takeaways: Coverage D, or loss of use, is the part of a Houston homeowners policy that may pay additional living expenses when a covered peril makes your home unfit to live in, typically reimbursing the increase in living costs rather than every dollar spent. It often includes a second component, fair rental value, and is usually capped at a percentage of the dwelling limit with possible time restrictions and primary-residence requirements. Denials commonly rest on habitability disputes, claims that expenses were not truly additional, insufficient documentation, excluded perils such as flood, or late reporting. Texas Insurance Code § 541.060 prohibits unfair settlement practices, including failing to explain a denial, failing to investigate reasonably, or refusing to settle when liability is reasonably clear. Deadlines may come from multiple directions, including contractual limitations periods, policy provisions requiring a claim be filed within one year of the loss, and two-year statutory windows for consumer and insurance code claims. Careful documentation, independent inspections, and a written request for the specific policy provision cited are generally among the policyholder’s strongest tools after an ALE denial.

Coverage D on a Houston homeowners policy is the "loss of use" section, and it generally pays additional living expenses (ALE) when a covered loss makes your home unfit to live in. If a hurricane peels back your roof in Clear Lake or a burst pipe floods your Heights bungalow, Coverage D may reimburse hotel stays, short-term rentals, and the increase in ordinary costs you incur while displaced. Texas insurance statutes and standard policy forms treat loss of use as a recognized, separate category of coverage, distinct from dwelling or personal property protection. Yet this is also one of the coverages carriers most frequently trim, delay, or deny outright.

If your additional living expenses coverage denied letter arrived while you were still living out of a suitcase, the team at Fitts Law Firm, PLLC may be able to help you evaluate your options. Call 713-871-1670 to discuss what happened, or contact us now to request a review of your denial letter and policy language.

hotel room key card and metal key on wooden dresser beside folded clothing

What Coverage D Actually Promises Under a Texas Policy

Coverage D is generally triggered by uninhabitability caused by a covered peril, not merely by inconvenience. Standard Texas homeowners forms typically divide protection into four parts: Coverage A for the dwelling, Coverage B for other structures, Coverage C for personal property, and Coverage D for loss of use. Actual policy language varies by insurer, since Texas insurers may file their own forms rather than use one mandated form. The Texas Department of Insurance publishes consumer guidance on this structure, and the Texas FAIR Plan Association, the state-created insurer of last resort, issues comparable residential forms.

For coastal windstorm coverage, Texas law requires that policies issued by the Texas Windstorm Insurance Association include coverage for wind-driven rain damage under specified conditions, loss of use, and consequential losses, subject to the association’s policy terms.

The practical measure of ALE is usually the increase in your living costs, not your total costs. If your mortgage continues and you also pay $2,800 a month for a rental in Katy, the carrier generally owes the added expense rather than every dollar you spend. Groceries, laundry, pet boarding, and extra commuting mileage may qualify, subject to the policy’s own definitions and exclusions, and only to the extent they exceed your normal pre-loss spending.

Fair Rental Value and the Second Half of Coverage D

Coverage D often contains two components: additional living expense and fair rental value. If you rented out a garage apartment that is now unlivable, the lost rental income may fall under the fair rental value portion, generally measured net of expenses that do not continue during the loss. Some forms treat these as separate sublimits while others apply a single Coverage D limit to both, and homeowners sometimes leave money unclaimed simply because they never read past the first paragraph.

Limits, Time Caps, and Primary Residence Requirements

Most loss of use policies contain ceilings, and Houston readers should find theirs before a storm hits. Many Texas forms cap Coverage D at 10 to 20 percent of the dwelling limit, and some add a time restriction such as 12 or 24 months, while others instead pay for the reasonable time required to repair or replace.

Texas law also recognizes carve-outs for the residual market. The Texas Windstorm Insurance Association, for example, is not required to provide loss of use coverage for loss of rent, loss of rental value, or additional living expenses attributable to a secondary or nonprimary residence. A summary of TFPA residential coverages illustrates how those structures are typically presented.

Why Additional Living Expenses Coverage Denied Letters Show Up After Houston Storms

Most Coverage D denials trace back to a handful of recurring insurer positions. Understanding which one applies to you may shape much of what follows, because a habitability dispute is generally proven very differently from a documentation dispute.

Common Stated Reason What the Carrier Is Arguing What Often Rebuts It
Home was "habitable" Damage did not render the residence unfit Photos, code officials, mold or electrical reports
Expenses were not "additional" You would have spent the money anyway Pre-loss budget, receipts, rental comparison
Insufficient documentation Receipts or proof of displacement missing Organized ledger, dated invoices, lease
Underlying loss not covered Flood, wear and tear, or excluded peril Causation evidence from an independent engineer
Late reporting Claim filed outside policy deadlines Evidence of timely notice, or lack of prejudice to insurer

Houston’s mixed-peril losses can create particular friction. After a hurricane, an adjuster may attribute damage to storm surge rather than wind, shifting the analysis to a separate flood policy and stranding your ALE claim between two carriers. Under Texas law, the policyholder generally bears the burden of allocating damage between covered and excluded causes, so causation evidence, rather than argument, often decides those disputes.

When a Denial May Cross Into an Unfair Settlement Practice

Texas law sets standards for how insurers must handle claims, and Coverage D is not exempt.

Under the Texas Insurance Code, it is an unfair method of competition or an unfair or deceptive act or practice to engage in unfair settlement practices such as misrepresenting a material fact or policy provision relating to coverage at issue, or failing to attempt in good faith to effectuate a prompt, fair, and equitable settlement of a claim with respect to which the insurer’s liability has become reasonably clear. These standards appear in the unfair settlement practices statute at Texas Insurance Code § 541.060.

Carriers are also generally required to explain themselves and to investigate. It is likewise an unfair settlement practice to fail to promptly provide a reasonable explanation of the basis for denial, to fail within a reasonable time to affirm or deny coverage, or to refuse to pay a claim without conducting a reasonable investigation. Whether any particular denial meets that threshold is fact-dependent, and Texas courts have generally held that a bona fide coverage dispute alone does not establish a violation. Separate prompt-payment deadlines under Chapter 542 may also apply. A one-line rejection with no policy citation may, at minimum, be worth questioning in writing.

Documentation is often the policyholder’s strongest leverage. Keep every receipt, log every phone call with the date and adjuster name, and send follow-ups by email so there is a written trail. Independent estimates and engineering reports may carry weight when a carrier’s own consultant reaches a convenient conclusion.

Deadlines That Quietly Shape a Coverage D Dispute

Timing rules in Texas may come from several directions at once, and they are not interchangeable. Breach of contract suits on an insurance policy are generally governed by a four-year limitations period, but policies themselves may shorten that. Under Texas Insurance Code § 2301.010, which applies to certain filed or department-adopted property forms, a policy form may provide a contractual limitations period for filing suit on a first-party claim, but that period may not end before the earlier of two years from the date the insurer accepts or rejects the claim, or three years from the date of the loss.

Reporting deadlines generally operate separately from suit deadlines. Under that same provision, a policy or endorsement may require that a claim be filed with the insurer no later than one year after the date of the loss. A separate statutory good-cause mechanism exists for Texas Windstorm Insurance Association policies, where the commissioner may extend the one-year claim-filing deadline, by regulation for up to 180 days, on a showing of objective facts beyond the insured’s control. Outside that context, whether a late-reported claim is barred usually turns on the policy’s notice condition and whether the insurer was prejudiced by the delay.

Statutory consumer claims carry their own clock. Actions under the Deceptive Trade Practices, Consumer Protection Act must generally be commenced within two years after the deceptive act occurred, or within two years after the consumer discovered or should have discovered it, with a limited 180-day extension where the defendant knowingly concealed facts. Claims under Chapter 541 of the Insurance Code are likewise subject to a two-year period. Discovery-based timing is not automatic, so treating the earliest possible deadline as the real one is generally the safer approach.

💡 Pro Tip: Ask your carrier in writing for the specific policy provision supporting the Coverage D denial. A written request creates a record and may reveal whether the decision rests on policy language or on an adjuster’s assumption.

Practical Steps After an ALE Denial

A denial is a position, not a final judgment, and policyholders may have several avenues. Consider the following before deadlines narrow your options:

  • Request the complete claim file and the adjuster’s habitability findings in writing.
  • Rebuild your expense record with dated receipts, leases, and bank statements.
  • Obtain an independent inspection addressing habitability and causation.
  • Compare your declarations page limits against what was actually paid.
  • Review whether appraisal, if invoked, would even reach a Coverage D dispute.

Appraisal deserves particular caution. Appraisal panels typically resolve the amount of loss, not coverage or liability questions, so a carrier pushing appraisal on a denied ALE claim may not be offering the remedy it appears to offer. Chapter 542A also requires specific pre-suit notice before filing many first-party property claims. Reading more insurance claim guidance for Texans can help you recognize these patterns early.

Frequently Asked Questions

1. Does Coverage D apply if I stay with family instead of a hotel?

Possibly, though the reimbursement analysis may change. If you incur no additional lodging cost, there may be little to claim for housing, but increased food, commuting, or storage costs may still qualify depending on your policy wording.

2. How long does temporary housing coverage in Texas typically last?

It depends on your specific form. Many policies pay for the reasonable time required to repair or replace the home, sometimes bounded by a stated number of months or by the Coverage D dollar limit, whichever is reached first. Repair delays caused by the carrier itself may factor into that analysis.

3. Can my claim be denied because the damage came from flooding?

A standard homeowners policy generally excludes flood, which can affect the ALE claim built on it. If wind and water both contributed, causation evidence may become central, and concurrent-cause analysis is highly fact-specific, with the insured generally responsible for segregating covered from excluded damage.

4. Is a rental property eligible for loss of use benefits?

Coverage for nonprimary residences is frequently limited or excluded in Texas forms. Fair rental value provisions may apply to a rented portion of your own residence, but a separate investment property generally requires a landlord or dwelling policy with its own loss of rents coverage.

5. What should I do first after receiving a denial letter?

Preserve everything and note the date. The denial date may start contractual and statutory clocks, and an attorney reviewing additional living expenses coverage denied lawyer matters can assess whether the stated grounds hold up.

Bringing the Pieces Together

Coverage D is a meaningful part of a Houston homeowners policy, and it exists precisely for the weeks or months when your house cannot shelter you. Texas statutes recognize loss of use as its own coverage category, set minimum floors for contractual deadlines to challenge a denial, and prohibit specified unfair settlement practices by insurers. Outcomes, however, always depend on the particular policy language, the cause of loss, and the quality of the documentation assembled. A denial letter reflects the carrier’s view of those facts, not necessarily the correct one.

If your temporary housing benefits were cut off or refused, Fitts Law Firm, PLLC is available to review your situation and explain the options that may remain. Call 713-871-1670 or schedule a consultation before contractual or statutory deadlines limit what you can pursue.

Disclaimer: This content is for informational purposes only and is not legal advice. Every case is unique, and results may vary. Consult an attorney about your specific circumstances.